A fund can make a dividend withholding tax reclaim whenever a country withheld tax on a dividend or interest payment at a higher rate than the fund was entitled to under a tax treaty or that country's own law, and the fund can prove its residence, its ownership of the shares on the right date and the tax actually taken, in that country's form and before its deadline. The hard part is not the law but the volume: one global fund can earn dividends in dozens of countries, each with its own rate, form, language and clock, and money that is not claimed in time is lost to the fund's shareholders. Botminds' Withholding Tax Reclaims gives a fund tax team agents that find every over-withheld payment, assemble the evidence, draft each country's form and watch each deadline, while named people accept the findings and sign.
The worked example on this page uses fictional sample data: Quillfield Capital, an invented manager with 120 funds, and the German claim of its Global Equity Fund. The rules and figures that frame it come from tax authorities, statutes and the European Commission, linked where they appear.
Reclaims are slow and paper-heavy even for professionals
56%
of businesses and business associations answering the EU consultation waited more than two years for a refund
83%
said assembling the documents for one refund claim takes more than three weeks
EUR 6.62bn
a year: the Commission's estimate of what withholding tax procedures cost investors in EU companies
When can a fund reclaim withholding tax on dividends? When three things are true
A fund can reclaim withholding tax on dividends when the tax taken exceeds the rate it was entitled to, it is the person entitled to the income, and it can prove both inside the country's time limit. The entitlement usually comes from a tax treaty. Under the US treaties with Germany, France, Switzerland, Denmark and most of Western Europe, a portfolio dividend paid to a US resident may be taxed at no more than 15%, according to the IRS treaty rate table. The domestic rates are higher: Germany withholds 26.375%, Switzerland 35%.
Sometimes the entitlement comes from the source country's own law instead. Germany's investment tax act sets a 15% rate for funds that hold a German status certificate (§7 InvStG), and EU free-movement-of-capital law can support a claim for the whole tax where a country exempts its own funds but taxes foreign ones. Those routes have their own forms and deadlines, and the EU-law claims known as Fokus Bank claims are a different piece of work from a treaty reclaim.
The IRS puts the mechanics in one sentence in its instructions for Form 8802: "Some foreign countries will withhold at the treaty-reduced rate at the time of payment, and other foreign countries will initially withhold tax at their statutory rate and will refund the amount that is more than the treaty-reduced rate on receiving proof of U.S. residency" (IRS, Instructions for Form 8802). The second group is where reclaims come from.
How does a fund reclaim withholding tax? Four steps, on every claim
Every reclaim runs the same four steps: find the excess, prove the entitlement, file in the country's form, and chase the money to the fund's account. What changes from country to country is the evidence each step needs and the clock it runs against. The figure shows the steps as they run in Withholding Tax Reclaims, with the step that stays with a person marked.
Four steps from an over-withheld dividend to cash in the fund
Agent
Find the excessCompare each dividend booked in portfolio accounting with the treaty rate for the fund's residence and with the custodian's tax voucher, and leave out shares that were on loan over the record date.
Never: Opens a claim on its own; a person accepts or dismisses each finding.
Agent
Prove the entitlementCheck the residence certificate, beneficial-ownership statement, power of attorney and vouchers for the right entity, tax ID and period.
Never: Signs or dates a statement for the fund.
A person decides
File in the country's formAn agent drafts the form in the country's language beside English and a second agent re-derives every figure; the fund tax manager reviews and signs.
Agent
Chase to cashRead the authority's letters, draft replies for approval, and match the refund to the claim when the custodian credits it.
Never: Sends a reply or posts a refund without a person's approval.
Finding the excess is where most money is lost. A custodian's reclaim report covers the assets that custodian holds and the claims its service files. Shares held in another account, relief at source that failed, and pension or special rates fall outside it. In the sample, Quillfield's Germany 2023 claim for the Global Equity Fund was EUR 212,400 that the custodian's report missed, because the 16 dividends sat in a securities-lending sub-account its reclaim service did not cover.
Proving the entitlement is where claims are rejected. Filing is where language and form versions matter: Switzerland accepts "only the latest version" of its refund forms and rejects a form that does not comply (Swiss Federal Tax Administration). Chasing is where claims stall, because a query from a tax authority comes with a short reply window, in the authority's language.
Relief at source or a reclaim: which one does the country use?
Relief at source means the treaty rate is applied when the dividend is paid; a reclaim means the full domestic rate is taken and the excess is refunded later. Whether a fund can get relief at source depends on the country and on paperwork reaching the paying agent before the payment date. Where the paperwork is late, or the country does not offer relief at source to the fund, the only route left is a reclaim.
Five tax authorities, five ways of giving treaty relief
| Country | Relief at source | Otherwise |
|---|---|---|
| Germany | An exemption certificate for treaty relief is issued only to a company holding at least 10% of the payer (§50c(2) EStG). A fund can bear 15% at source under the investment tax act if the withholding agent holds its status certificate. | Refund application to the Federal Central Tax Office, filed electronically. |
| France | Simplified procedure: Form 5000 must reach the paying institution before the dividend is paid. | Form 5000 with Appendix 5001, to reclaim. |
| Switzerland | None for foreign residents: the 35% tax is a final charge unless a treaty gives a refund. | Refund form for the residence country; for US regulated investment companies, Form 82 R. |
| Denmark | Net withholding at the treaty rate needs the agency's prior approval, and its guidance describes it for individual principal shareholders; other foreign companies are withheld at 27%. | Online refund claim, up to 20 distributions per claim. |
| Canada | Form NR301 to the payer, so the treaty rate is withheld. | Form NR7-R refund application to the Canada Revenue Agency. |
The German row explains why funds reclaim so much German tax. The exemption certificate route in the Income Tax Act is closed to a portfolio holder, so unless the investment tax route is working, every German dividend arrives at 26.375% and the 11.375 points above the treaty rate have to be claimed back. The German reclaim, route by route, sets out both statutes.
What documents does a fund need to reclaim withholding tax?
Most reclaims need four kinds of document: proof of residence for the right entity and year, proof of the tax taken on each payment, proof of ownership on the date that matters, and authority for whoever files. Countries add their own. The checklist is what a fund tax analyst should hold before a claim goes to a signer.
The evidence file for one country-year claim
- A residence certificate for the right entity and period
For a US fund, IRS Form 6166, requested on Form 8802. The legal name must match the fund, including "a series of" where the fund is a series of a trust.
- The custodian's tax voucher for every payment
Switzerland requires the bank's tax vouchers where the securities are held at a foreign bank; Denmark asks for the dividend advice showing Danish tax withheld.
- Proof of holding on the date that counts
Denmark asks for a custody statement on the date the dividend was adopted, with changes from six months before to six months after.
- A beneficial-ownership statement
The IRS says it "cannot certify whether you are the beneficial owner"; the source country asks the fund to state it.
- Powers of attorney down the chain
Denmark requires one from each representative between the filer and the shareholder.
- The country's current form, in its language
An out-of-date Swiss form is rejected; France needs Form 5000 and Appendix 5001 together.
The residence certificate is the document most often wrong in ways that matter: the wrong year, the umbrella instead of the sub-fund, a tax ID with two digits swapped. Form 6166 and how to keep it valid covers the US certificate, its fees from October 2026 and its timing.
How long does a fund have to reclaim withholding tax?
Each country sets its own time limit and counts it from a different event, so the deadline for one fund's claims can fall in a different month in every country. Germany counts four years from the end of the year the dividend was received; Italy counts 48 months from the day the tax was withheld. The table gives the rule in each authority's own terms.
Seven time limits, counted seven ways
| Country | Time limit, in the authority's terms | A 2023 dividend lapses |
|---|---|---|
| Germany | Four years from the end of the calendar year the income was received, and not before one year after the tax was paid | End of 2027 |
| Switzerland | Three years after the end of the calendar year in which the payment fell due | End of 2026 |
| France | By 31 December of the second year following the year the income was paid, unless the treaty says otherwise | End of 2025 |
| Denmark | 5 years from the time the dividend tax was withheld | Five years after the payment |
| Italy | 48 months from the date the tax was paid or withheld at source | Four years after the payment |
| Netherlands | 3 or 5 years after the year the dividend was made available, depending on the basis of the claim | End of 2026 or 2028 |
| Canada | Two years from the end of the calendar year the tax was sent to the Canada Revenue Agency | End of 2025, if remitted in 2023 |
Two things in the table catch teams out. A French 2023 claim had already lapsed by the end of 2025, while the German claim for the same year is open until the end of 2027. And deadlines move: the Danish Tax Agency says its limit "has been changed from 3 to 5 years based on a decision made by the Danish Supreme Court" in June 2026, and that it will reopen claims it rejected under the old three-year rule (Danish Tax Agency). A team that keeps its deadlines in a spreadsheet has to notice that change and apply it to every Danish claim.
Who files the reclaim: the fund, the custodian or an agent?
The claim belongs to the fund, but most claims are filed for it by its custodian, a reclaim service or the fund's own tax team, under a power of attorney. Who files matters less than who checks. A custodian's service files standard claims on the assets it holds; it does not see the fund's other custodians, and it may not file pension-rate or EU-law claims at all.
The Commission's impact assessment lists why investors leave money unclaimed: "lack of awareness (custodian and beneficial owner); choice of non-disclosure; failure to meet deadlines, particularly where documentation is very specific and time delimited; claims falling outside statute; lack of service offering; incorrectly filed claims" (SWD(2023) 216). Every item on that list is a gap between what the custodian files and what the fund is owed.
The fund tax team's job is to close that gap: compare what was owed, payment by payment, with what each custodian filed, and file the rest. That comparison is the first thing to automate, and how tax reclaim services compare sets out what each kind of filer covers.
How long does a withholding tax refund take?
A withholding tax refund takes from a few months to several years after filing, depending on the country and on whether the authority queries the claim. The Swiss Federal Tax Administration says "Processing can take up to several months" and that it does not confirm receipt. Denmark has told claimants who filed before 1 January 2026 that their "expected processing time has been extended by 18 months", which it attributes to "the extensive fraudulent claim of dividend tax prior to 2015".
What a fund waits for, from dividend to refund
- Paid 2023, found 2026about 3 years to find
- Filing to refund9 months, median
- Refund≈4 mo
The top lane is the more common shape of a lost or late claim: the time goes on finding it, not on the authority. The bottom lane is the EU's answer, and it is still years away; what the FASTER directive changes, and when explains which funds it will help.
Shares on loan, manufactured dividends and who the owner is
Whether a fund can reclaim tax on shares it had lent out depends on the country's rules on beneficial ownership, so a reclaim has to know where every share was on the record date. On a typical securities loan the borrower receives the dividend and pays the lender a manufactured payment, and the lender cannot reclaim tax that was not withheld from it. In the sample, 52,000 German shares were on loan over two record dates, and the Income Finder left out EUR 82,800 of manufactured payments, which would have added EUR 9,418.50 the fund was not owed.
The rule is not the same everywhere. The Danish Tax Agency says that under a share loan agreement "the lender will still be the beneficial owner of the shares for tax purposes", and asks every claim to state whether shares were lent or borrowed on the date the dividend was adopted. A reclaim engine that applies one rule to every country will be wrong in one of them.
Where Withholding Tax Reclaims fits
Withholding Tax Reclaims does the volume work in the four steps and leaves the decisions with the fund tax team. The Income Finder checks every dividend against the treaty rate the night it is booked; the Evidence agent checks certificates and statements; the Forms agent drafts each country's form in its language; a separate Checker agent re-derives every figure before anyone signs; the Statute Watcher dates every claim from its country's rule.
What the reclaim search found that the custodian's report did not
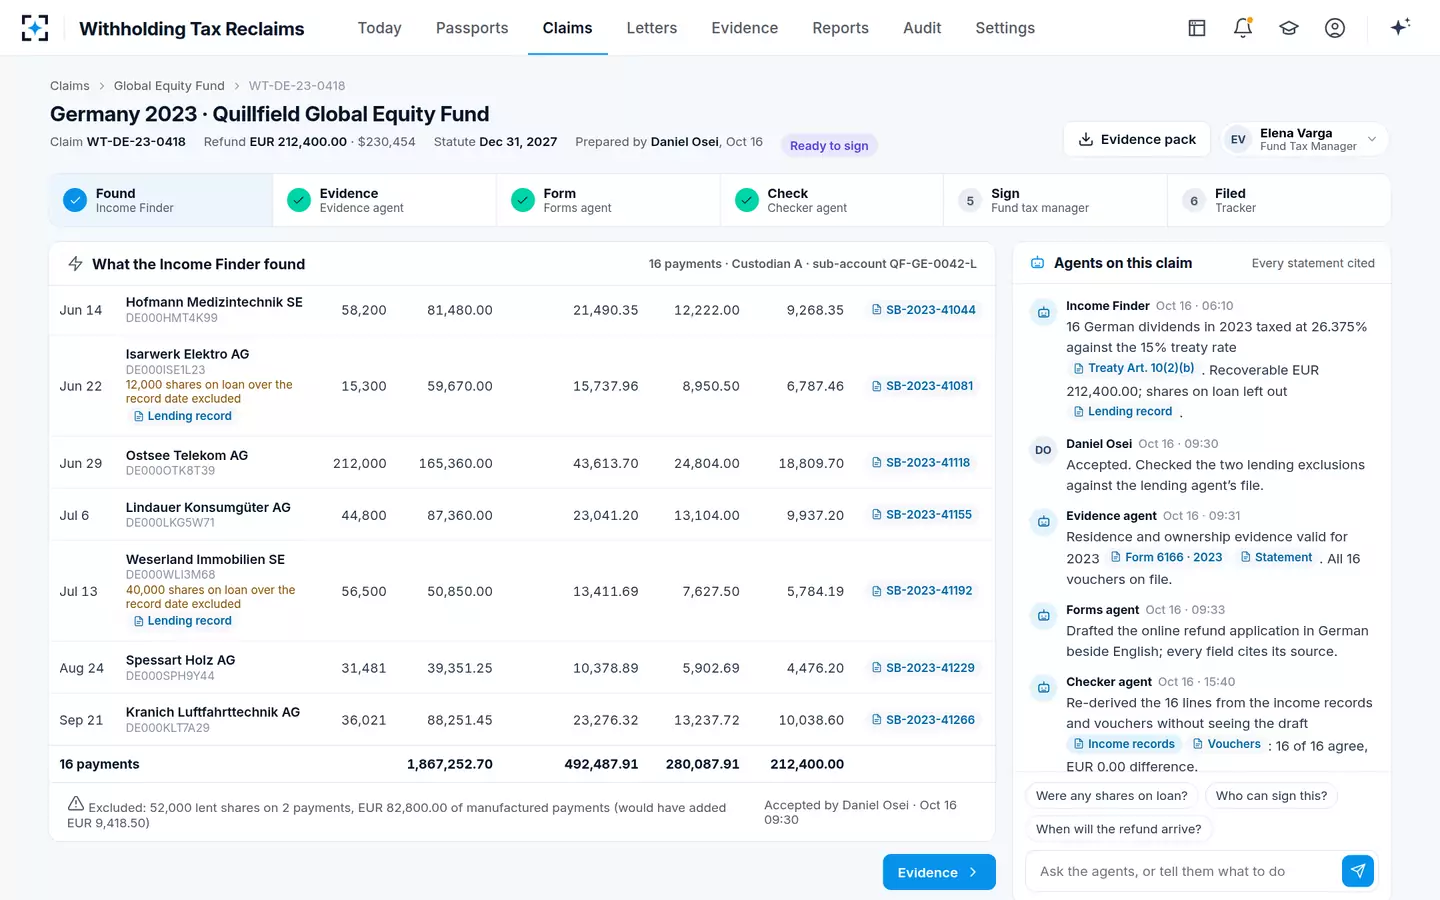
It does not decide whether the fund is entitled to a treaty rate in a contested case, or whether to pursue an EU-law claim; it shows the finding, its reasons and its confidence, and a person decides. The Withholding Tax Reclaims page shows the whole claim, from the overnight find to the filing.
One fund's countries, rates and deadlines on one screen
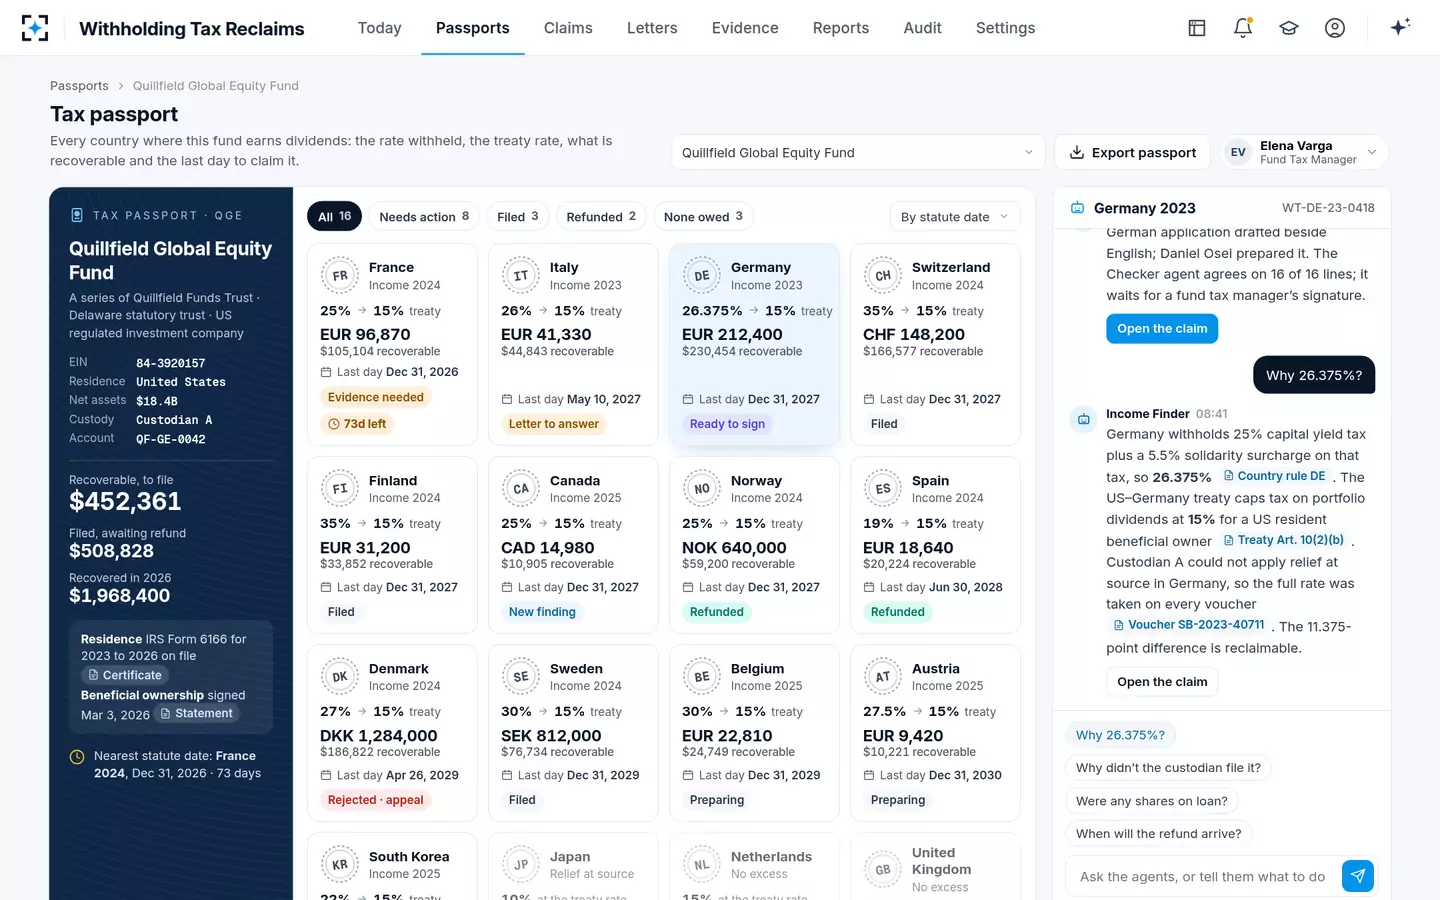
Questions people ask
Can a foreign fund claim back withholding tax on US dividends?
The US withholds at 30% on dividends to foreign persons unless a treaty rate applies, which is 15% on portfolio dividends for most European treaty partners according to the IRS treaty table. The usual route is relief at source: the fund gives the US withholding agent a valid Form W-8BEN-E, the same form its brokers ask for when they open its accounts (see the broker's KYC questionnaire, section by section). The IRS instructions give its life as the year of signing plus three full calendar years, cut short by any change in circumstances.
Is withholding tax refundable if the treaty rate is the same as the domestic rate?
No. A reclaim recovers the difference between what was withheld and what the fund was entitled to, so where the two rates match there is nothing to reclaim. Such countries still belong in the fund's monitoring, because a payment withheld above the domestic rate, or a domestic exemption for funds, can create a claim.
Can a reclaim be filed after the deadline?
Generally not: beyond one narrow extension, Germany's investment-tax refund route says its two-year deadline "kann nicht verlängert werden", cannot be extended. Where a deadline is near and evidence is missing, some teams file a protective claim with what they have and complete it later, where the country's procedure allows.
Does a fund need a new residence certificate every year?
Usually yes, because most certificates cover one tax year and the claim must match the year of the payment. Form 6166 is issued for the period requested on Form 8802, and the IRS will not process a current-year request postmarked before 1 December of the prior year.
Does the custodian reclaim withholding tax automatically?
Many custodians offer a reclaim service, but it covers the assets they hold and the claim types they support. Claims on assets in other accounts, failed relief at source, pension rates and EU-law routes often fall outside it, so the fund still needs its own check of what was owed against what was filed.