Form 6166 is a letter from the IRS certifying that a person or entity is a US resident for federal income tax purposes, which foreign tax authorities require before they give a US fund its treaty rate or refund the tax they withheld above it. A fund requests it on Form 8802, Application for United States Residency Certification, with a user fee that rises to $230 for business applicants from 1 October 2026, and the IRS asks for the application at least 45 days before the certificate is needed. For a withholding tax reclaim, the certificate has to name the right entity for the right year, and it is only one part of an evidence file that decides whether the claim is paid. Botminds' Withholding Tax Reclaims checks every certificate, statement and voucher against the claim it supports before anyone signs.
The rules here are the IRS's own and the foreign tax authorities', linked where they appear. Where the guide shows the solution at work, it uses fictional sample data from Quillfield Capital, an invented US manager with 120 funds.
A reclaim's evidence file, and when each document goes stale
- Form 6166 for the year of the dividend
Certifies US residence for the period requested on Form 8802. A 2023 dividend needs a certificate covering 2023.
- The source country's own residence form, if it has one
France's Form 5000 must be certified, or accompanied by a residence certificate; it goes to the paying bank before the dividend for relief at source.
- A beneficial-ownership statement
The IRS "cannot certify whether you are the beneficial owner of an item of income"; the fund states it, usually once a year, and must update it if circumstances change.
- The tax certificate or voucher for every payment
In Germany, from the German paying agent; a foreign custodian's dividend advice is not sufficient.
- Proof of the holding on the date that counts
Denmark asks for a custody statement on the date the dividend was adopted, with changes six months either side.
- Powers of attorney for each representative
Denmark requires one from every representative between the filer and the shareholder.
What is Form 6166?
Form 6166 is the IRS's letter of US residency certification. In the IRS's words, "Form 6166 is a letter printed on U.S. Department of Treasury stationery certifying that the individuals or entities listed are residents of the United States for purposes of the income tax laws of the United States", and "You may use this form to claim income tax treaty benefits and certain other tax benefits in foreign countries" (IRS, Form 6166). It is issued by the IRS's Philadelphia office.
The IRS issues it only when it can verify residence from the applicant's filings. In general it needs to see that, for the certification year, the applicant filed an appropriate return, or for a year whose return is not yet due, a return for the most recent year that was due. It will not certify an applicant that filed as a nonresident, or a fiscally transparent entity in its own name: a domestic partnership "is not considered a U.S. resident, even if all partners are U.S. residents", and its certificate lists the partners who are (IRS, Instructions for Form 8802).
How do I apply for Form 6166?
You apply for Form 6166 by filing Form 8802, which the IRS says is mandatory: "The Internal Revenue Service (IRS) procedure for requesting a certificate of residency (Form 6166) from the Philadelphia Accounts Management Center is the submission of Form 8802 ... Use of the Form 8802 is mandatory." You pay the user fee first, on Pay.gov, and write the payment confirmation number on page 1; the IRS "will not process Form 8802 if the application does not include the e-payment confirmation number".
Applications go by mail, private delivery service or fax, and up to ten Forms 8802 can be faxed at once, to a maximum of 100 pages. A form for the current year must be signed under penalties of perjury, and "will not be considered complete and valid if the application is not signed and dated by an individual who has the authority to sign" (IRS). One Form 8802 can ask for certificates for several countries and years, which matters because the fee is per application.
How much does Form 6166 cost?
From 1 October 2026, Form 6166 costs $230 per Form 8802 for a business applicant such as a fund, up from $185, and $105 for an individual, up from $85. The IRS announced: "User fees for Form 8802 increase from $85 to $105 for individual applicants and from $185 to $230 for business applicants starting Oct. 1, 2026" (IRS, About Form 8802).
Form 6166 by the numbers, from October 2026
$230
user fee per Form 8802 for a business applicant, up from $185
45days
the IRS asks you to allow before the date you need the certificate
30days
after which the IRS will contact you if processing is delayed
1 Dec
earliest postmark for a request for the following year's certificate
The fee "is for the number of applications submitted, not the number of certifications requested", so a fund that needs certificates for twelve countries pays once if it asks for all twelve on one form. A fund family with many series pays per applicant, because each fund files its own Form 8802.
How long does Form 6166 take?
Plan on at least 45 days. The IRS instructions say: "You should mail your application, including full payment of the user fee, at least 45 days before the date you need to submit Form 6166. We will contact you after 30 days if there will be a delay in processing your application" (IRS, Instructions for Form 8802). Applications for a year whose return the IRS has not yet posted can need a signed copy of the most recent return.
When a fund can get its certificate for 2027, and when it should ask
- Too early: returnedbefore 1 Dec 2026
- Apply1 Dec +45 d
- Use for 2027 relief at source and claims2027
The December rule shapes the calendar. A request for 2027 "cannot be processed" if postmarked before 1 December 2026. A fund that needs its 2027 certificate for relief at source on January and February dividends, France's Form 5000 for example, has a few weeks to file and receive it. Certificates for past years can be requested at any time, which is what a fund does when it finds an old claim.
How long is Form 6166 valid?
Form 6166 certifies residence for the period requested on Form 8802, normally a tax year, so a certificate is valid evidence for dividends paid in that year and not for others. A 2023 claim needs a 2023 certificate. A reclaim found three years late needs three years of certificates, each requested for its own year.
Some applicants can cover three years with one set of statements. The IRS's "3-year procedure" lets estates, employee benefit plans and trusts, and exempt organisations "submit a Form 8802 that covers up to a 3-year period (the current year and the following 2 tax years)", attaching the year 1 form in years 2 and 3 if nothing material has changed. A fund that is not in those groups requests each year separately.
Validity also depends on the receiving country. Germany wants a residence certificate "inkl. Gültigkeitszeitraum", with its period of validity (BZSt), confirming residence when the dividend was received. Italy's instructions let the foreign authority's statement cover several years where the refund concerns tax withheld in different years. Under the EU's FASTER directive, a source Member State may treat a third-country certificate as appropriate proof if its content is equivalent to the EU's digital certificate (Directive (EU) 2025/50, Article 12).
What is the difference between Form 8802 and Form 6166?
Form 8802 is the application; Form 6166 is the certificate the IRS issues in response. A fund files Form 8802 with the IRS; it sends Form 6166, or the foreign form the IRS has stamped, to the foreign withholding agent or tax authority. Neither is the same as Form W-8BEN-E, which a foreign entity gives a US withholding agent to claim treaty relief on US-source income.
Three US forms a fund tax team meets, and which direction each faces
| Form | Who signs it | Who receives it | What it does | How long it lasts |
|---|---|---|---|---|
| Form 8802 | The US fund or its authorised officer | IRS, Philadelphia | Applies for US residency certification | One application, any number of countries and years |
| Form 6166 | Issued by the IRS | Foreign withholding agents and tax authorities | Certifies US residence for treaty claims abroad | The period certified, normally a tax year |
| Form W-8BEN-E | A foreign entity | A US withholding agent | Claims foreign status and treaty rates on US-source income | Generally to the end of the third calendar year after signing, unless circumstances change |
A fund's own investors' W-8 and W-9 forms are a separate job again, owned by investor services; FATCA and CRS self-certification covers that side.
What does a fund's certificate have to match?
The certificate has to match the claim in four things: the entity's legal name, its taxpayer identification number, the period, and its status as a resident. Each is a common reason for a query. A fund that is a series of a trust must apply, and appear, as that series; a certificate naming the trust when the claim is in the series's name invites a letter.
In the sample, the Evidence agent checked the Global Equity Fund's 2023 Form 6166 against the fund administrator's data before the German claim was drafted: the legal name "Quillfield Global Equity Fund, a series of Quillfield Funds Trust", the employer identification number, a period covering every payment date, and the signature. The Forms agent then cited the certificate on the applicant, residence and tax ID fields of the German application. The German reclaim shows the finished application.
Why are withholding tax reclaims rejected?
Most reclaims that fail do so on evidence, not arithmetic: a certificate for the wrong year or entity, a missing beneficial-ownership statement, a voucher from the wrong institution, an outdated form, or no reply to the authority's query in time. Each authority states its own conditions. Denmark lists five that a claim must document, including that the shareholder was the beneficial owner on the date the dividend was adopted (Danish Tax Agency). Switzerland rejects a form that is not the latest version.
Tax authorities have reasons to be strict. In Skatteforvaltningen v Solo Capital Partners, the English High Court held that not one of the 4,170 dividend tax refund claims the Danish tax authority had paid between 2012 and 2015, for just under DKK 12.1 billion, was valid under Danish law, and it described the authority's controls at the time as barely there ([2025] EWHC 2364 (Comm)). Denmark now tells claimants that its long processing times are a legacy of the large-scale refund fraud before 2015 (the four-step reclaim guide has its exact words and the 18-month extension). A genuine fund's claim is read by an authority that has learned to doubt.
A query for three documents, answered from the evidence on file
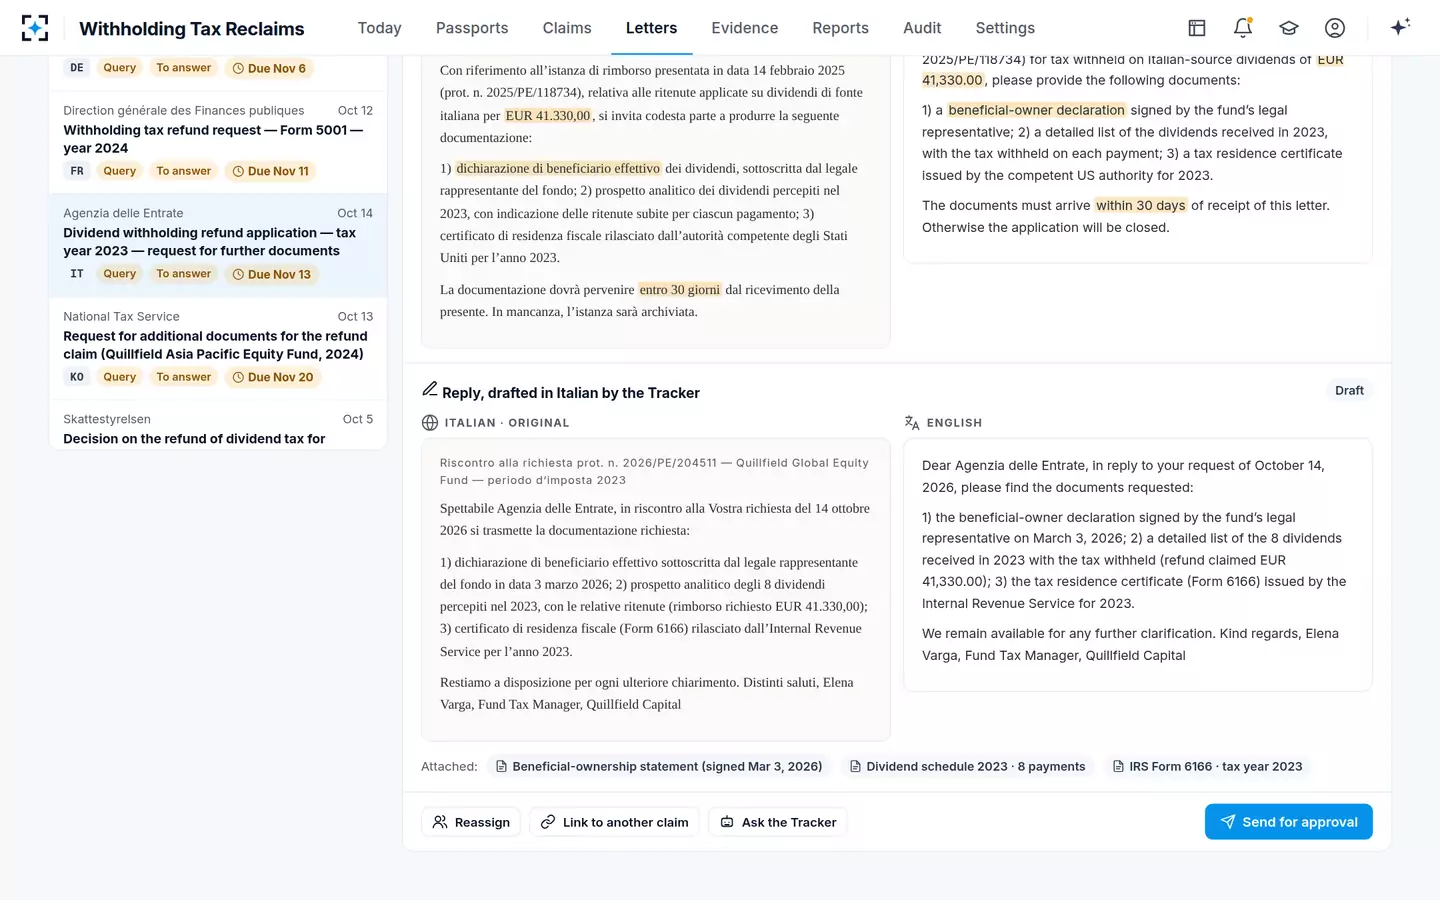
How Withholding Tax Reclaims checks the evidence
In Withholding Tax Reclaims, the Evidence agent checks each residence certificate, ownership statement, power of attorney and voucher for entity name, tax ID, period, signature and stamp, and prepares certificate requests such as Form 8802 packages for US funds. It never signs or dates a statement and never edits a certificate. It flags, for example, a certificate that names an umbrella instead of the sub-fund, or a tax ID with two digits swapped.
When an authority's letter asks for evidence, the Tracker finds what is already on file and drafts the reply in the authority's language for a manager to approve. The Statute Watcher counts each claim's deadline and escalates where evidence is late. The four-step dividend withholding tax reclaim sets the evidence in the four steps of a claim, and the tax reclaim process for a small team shows how the certificate calendar fits a year's work. The Withholding Tax Reclaims page shows the evidence step on one German claim.
Questions people ask
Can I check the status of my Form 6166 application?
The IRS says it will contact you after 30 days if processing will be delayed, and gives a telephone number in the Form 8802 instructions for questions about an application. It asks applicants to allow at least 45 days before the date the certificate is needed.
Does Form 6166 prove beneficial ownership?
No. The IRS says it "cannot certify whether you are the beneficial owner of an item of income or that you meet the limitation on benefits article, if any, in the treaty". The fund establishes those directly with the foreign withholding agent or tax authority, usually with a signed statement.
Can a partnership get Form 6166?
Not as a resident in its own right: the IRS says a domestic partnership is not a US resident for treaty purposes, even if all its partners are. The Form 6166 it receives lists the partners who are US residents, and the partnership must give the withholding agent their ownership shares, which the IRS does not certify.
Is Form 6166 enough for a French reclaim?
France works with its own Form 5000, which the residence country's tax office certifies, or which is accompanied by a paper or electronic residence certificate. For dividends, a reclaim adds Appendix 5001; for a US resident whose account is with a US financial institution, the DGFiP notice says that institution's affidavit can replace certification.
Can Form 6166 be used for VAT?
Yes, as proof of US tax residence when claiming a foreign VAT exemption, but the IRS says it can certify only matters relating to US federal income tax status, not that the applicant meets any other condition of the foreign exemption.