The difference between a written and a signed line is the difference between an offer of capacity and the share finally taken. A written line is the percentage of a layer a reinsurer agrees to write when it authorises its participation on the firm order terms. A signed line is the percentage it actually takes once the placement is complete: if reinsurers together wrote more than 100% of the layer, the broker signs the lines down, by the method the client agreed, until they total exactly 100%, and each reinsurer's signed line is smaller than its written line. A line written "to stand", usually the lead's, is not reduced. In a 2005 English case one insurer "wrote a 47.5% line which later signed down to 45.238%"; on a layer written to 118% with a 20% lead line standing, a 10% written line signs at about 8.16%. Botminds' Reinsurance Placement Management is an agentic solution for treaty brokers that keeps written and signed lines side by side for every layer, and works out the signing down whenever a line changes.
The worked layer below is from a fictional sample program in the solution, Ashgrove Mutual's 2027 property catastrophe excess of loss placed by Northmoor Re Partners; the reinsurers named are invented. The court cases are real and linked.
What is the difference between a written line and a signed line?
A written line is a maximum; a signed line is the result. When a reinsurer writes 10% of a layer it commits to take up to 10% on the agreed terms, knowing that if the layer is over-placed its share will be reduced. The signed line is set when the broker closes the order and applies the signing: it is the share on which the reinsurer's premium, its liability and every future account are calculated.
Two numbers on the same line can therefore differ for good reasons, and the size of the difference is set by the whole layer, not by the reinsurer. In the 2005 case, the insurer's 47.5% written line signed at 45.238%: the ratio, 0.95238, is exactly 100 ÷ 105, which is what a slip written to 105% would produce if every line were cut by the same factor. That is our arithmetic on the judgment's figures; the court did not need to say how the slip was signed (Allianz Marine Aviation v GE Frankona [2005] EWHC 101 (Comm)).
Written and signed lines on one over-placed layer: the lead stands, every other line shrinks by the same factor
Why brokers over-place a reinsurance layer
Over-placement means the written lines on a layer add up to more than 100%. It arises in subscription placements because a broker collecting lines cannot know in advance which will hold: a line may come with a subjectivity that is never cleared, a condition the client will not accept, or a reinsurer that fails the client's security rules. A layer closed at exactly 100% has no room for any of that; a layer written to 105% or 118% can lose a line and still be complete.
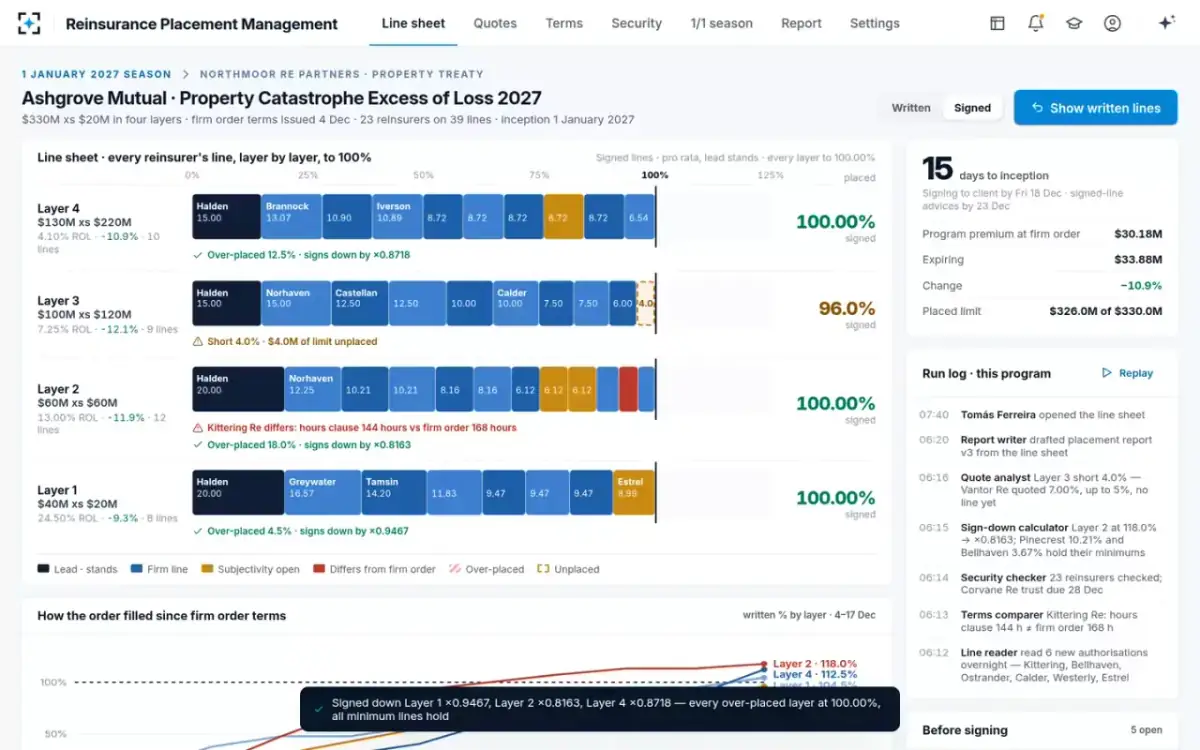
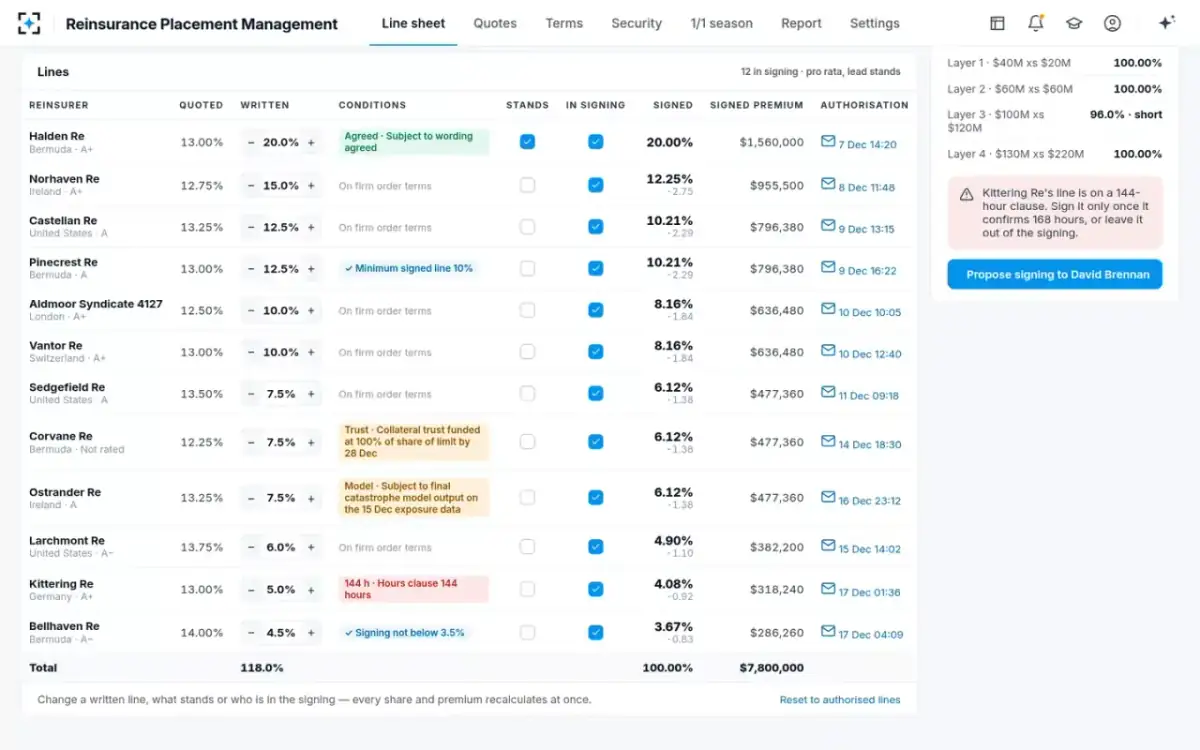
The sample program shows the pattern. Fifteen days before inception, three of its four layers were over-placed (Layer 1 at 104.5%, Layer 4 at 112.5%, Layer 2 at 118.0%) and one was 4.0% short. On Layer 2, one of the twelve lines had been written subject to a 144-hour hours clause where the firm order said 168, another subject to final catastrophe model output, and a third subject to a collateral trust being funded. Over-placement is what lets a broker deal with those lines without leaving the layer short.
For reinsurers, a written line is a statement of appetite as much as a commitment. A reinsurer that writes 10% on a layer it expects to be over-placed knows it will probably sign lower; one that wants a guaranteed share asks for its line to stand or attaches a minimum signed line, as two of the sample's reinsurers did (a minimum signed line of 10%, and "signing not below 3.5%").
What is signing down?
Signing down is the reduction of written lines on an over-placed layer to signed lines that total exactly 100%. Under the most common method, pro rata with the lead standing, the lines that stand keep their full share and every other line is multiplied by the same factor: (100% − standing lines) ÷ (total written − standing lines). On the sample's Layer 1, that is 80 ÷ 84.5 = ×0.9467; on its Layer 2, written to 118% with the same 20% lead standing, it is 80 ÷ 98 = ×0.8163. The results are rounded, and the layer must still total exactly 100.00%, which simple rounding often fails to achieve.
The method is the client's choice and belongs in its buying instructions. The sample client signs pro rata with the lead standing; others sign every line pro rata, or fill the layer in a preferred order and cut the rest. Every method then has to be checked against each reinsurer's minimum line and the client's own minimum. The full calculation, with rounding, minimums and ten test cases, is worked line by line in its own guide.
Written to signed in one switch, in Reinsurance Placement Management
Lines written to stand, and the lead line
A line written "to stand" is excluded from signing down: it keeps its full written share however far the layer is over-placed. A lead may write to stand: it sets the terms the others follow, and a client may want it at full size. In a 1998 placement examined by the Commercial Court in 2011, the leading underwriter crossed out 25% on the slip and wrote "30% to stand. As per L/S no overrider", and the placement's lines "added up to 101.5%, which later signed down to 100%" (Beazley Underwriting v Travelers [2011] EWHC 1520 (Comm)).
Every standing line makes the cut deeper for the rest. On the sample's Layer 2, if the 20% lead were signed pro rata like everyone else, every line, the lead included, would be multiplied by 100 ÷ 118 and the lead would sign at 16.95%. With the lead standing, the other eleven lines share 80% instead of 83.05%, so each signs lower. That trade is the client's to make, which is why the sample client's buying instructions name the lines that stand.
Written line and signed line, side by side
Written line: When the reinsurer authorises its participation on the firm order terms.
Signed line: When the broker closes the order and the client approves the signing.
Written line: The most the reinsurer agreed to take, on those terms.
Signed line: The share it actually takes: premium, liability and accounts follow it.
Written line: The reinsurer.
Signed line: The signing method in the client's instructions, applied by the broker.
Written line: Only by a new authorisation from the reinsurer.
Signed line: Whenever any line on the layer changes, until the signing is approved.
Written line: The reinsurer's authorisation or scratch on the slip.
Signed line: The signing, and the signed line advice to each reinsurer.
Written and signed lines in the court record
Courts meet signed lines when something else has gone wrong, which is why their judgments are a useful record of how the market works. Three English cases show the range: an insurer whose signed share became the measure of a reinsurance dispute, a placement whose lead line was written to stand, and a broker sued for failing to achieve the signing it had indicated.
Signed lines in three English judgments
| Case | What the record shows | Why it matters |
|---|---|---|
| Allianz Marine Aviation v GE Frankona [2005] EWHC 101 (Comm) | An insurer of a floating casino damaged by tropical storm Isidore "wrote a 47.5% line which later signed down to 45.238%"; its reinsurer agreed it had reinsured that whole signed share, and the trial was about how the reinsurance excess applied. | The signed share, not the written one, is what a claim and its reinsurance are measured on. |
| Beazley Underwriting v Travelers [2011] EWHC 1520 (Comm) | The lead wrote "30% to stand"; the placement "added up to 101.5%, which later signed down to 100%". | A standing line is written on the slip, and over-placement of a point or two is ordinary. |
| The Zephyr, as explained in Goshawk Dedicated v Tyser [2006] EWCA Civ 54 and Lejonvarn v Burgess [2017] EWCA Civ 254 | A broker indicated a signing down that was only partly achieved; the first-instance judge found a duty of care, and the Court of Appeal reversed on the law of negligence. | Without the signing, reinsurers are held to their lines "as written". |
What is a signed line advice?
A signed line advice tells each reinsurer the share it has finally been signed at, so its books, its premium and its liability match the broker's. It goes to every reinsurer on every layer once the signing is settled, and it is the point after which a correction becomes expensive: an error in one signed line usually means the layer's other lines are wrong too, and each reinsurer has to be told again.
The order of events is what protects it. In Reinsurance Placement Management the broker proposes the signing to the client, the client approves it with any open point stated, and only then do the advices, one per reinsurer, become ready to send. In the sample program that meant 23 advices after the client's approval, with one line signed "subject to" its reinsurer confirming the firm order's 168-hour clause. Under the NAIC's model act, the broker's ten-year file must hold the names of the assuming reinsurers and written evidence that each agreed to assume the risk (NAIC Model Act #790); the advice and the authorisation behind it are that evidence for the signed share.
When a signing indication is not met
If an over-placed layer is never signed down, the reinsurers can be held to their full written lines. That was the position in The Zephyr, a 1980s Lloyd's case in which a broker had given syndicates a signing down indication and the slip was only partially signed down. The first-instance judge "held … that an insurance broker owed a duty of reasonable care to use best endeavours to achieve an indicated signing down" (as described in Lejonvarn v Burgess [2017] EWCA Civ 254), in a market where, in his words, the broker's role was "one where he is the servant of the market" (Goshawk Dedicated v Tyser [2006] EWCA Civ 54). The Court of Appeal allowed the broker's appeal, holding that failing to perform a positive undertaking of that kind was not the subject matter of the law of negligence.
The syndicates were held to the terms of their contracts with the reassured as written, rather than in the attenuated form which would have resulted from a signing-down.
Mustill LJ in The Zephyr [1985], as quoted by the Court of Appeal in Lejonvarn v Burgess [2017] EWCA Civ 254
The lesson for a placement team is in the facts, not the tort law. A written line is a real commitment; the signing is what reduces it, and until the signing is done and advised, every reinsurer on an over-placed layer is exposed for more than it expects to keep. A signing that is late, partial or built on a stale list of lines leaves that exposure in place. The broker's responsibilities in the fortnight before inception follow the signing from proposal to advices.
Signed lines, the lead's signature and the nine-month rule
The signing settles the shares; the contract still has to be signed, and U.S. statutory accounting puts a clock on it. A reinsurance contract not finalized, written and signed within nine months of the start of the period it covers is presumed retroactive. For contracts with more than one reinsurer, the presumption does not apply if the lead reinsurer, the one that set the terms the others follow, signs within those nine months (NAIC Issue Paper No. 75, the rule carried into SSAP No. 62R; the 9 month rule in plain words).
That makes the lead special twice over. Its line often stands at full size in the signing, and its signature can carry the whole contract's accounting status. A broker tracking signed lines should track the lead's contract signature with them, and the firm order terms the lead set, annotated line by line, are the standard every other line is checked against.
One layer's written and signed lines, with every condition, in Reinsurance Placement Management
To see written and signed lines kept together for every layer of a program, with the signing worked out on each change, start from the solution page.
Questions people ask
What is over-placement in reinsurance?
Over-placement is when the written lines on a layer add up to more than 100%. It gives the broker room to lose a line that fails a condition or the client's security rules without leaving the layer short, and it is resolved by signing the lines down to exactly 100%.
Does a reinsurer always get less than its written line?
Only if the layer is over-placed and its line does not stand. A line written to stand keeps its full share, a layer placed at exactly 100% signs every line as written, and a reinsurer's minimum signed line sets a floor below which its line cannot be signed.
Is the signed line binding on the reinsurer?
The reinsurer is bound by its written line on the agreed terms, subject to the signing down it accepted when it wrote. In The Zephyr, where an indicated signing was not achieved, the syndicates were held to their contracts "as written". Once the signing is applied and advised, the signed line is the share its premium and liability follow.
Who decides how lines are signed down?
The client, through its buying instructions: which lines stand, whether the rest are cut pro rata or in a preferred order, the minimum signed line and the rounding. The broker applies the method and proposes the signing; the client approves it before signed line advices go out.
What is the difference between a written line and a line slip?
A written line is one reinsurer's share of one layer. A line slip is a different instrument: an arrangement under which named leading underwriters can accept individual risks for a group of underwriters, each declaration then carrying the participants' lines. The 2011 Beazley case concerned a placement under such a line slip.