A notice of nonrenewal of insurance is the insurer's written notice that it will not renew a policy when the current term ends. It must reach the named insured at the address shown in the policy a set number of days before expiry (45 for a Florida commercial policy and 120 for a Florida home, 60 in Texas, 75 in California plus mailing days, 45 to 60 for New York personal lines and 60 to 120 for New York commercial); state the specific reason; carry the wording the state requires; go to the agent or broker and any mortgagee or loss payee; and be provably mailed. A nonrenewal ends cover at expiry, unlike a cancellation, which ends it mid-term. Botminds' Cancellation & Nonrenewal Compliance reads every nonrenewal in a day's mail run and checks each of those lines against the state's rule before the letter prints; this guide takes one sample letter apart line by line.
The letter is from a fictional sample carrier, Kestrel Point Insurance Group, as it appears in the solution after a re-date on 12 October 2026; the rules are quoted from state statutes and exam reports, linked where they appear.
A notice of nonrenewal of insurance, annotated: five lines that carry the law
Kestrel Point Insurance Group · Form KP-NR-FL-03 (06/24)
NOTICE OF NONRENEWAL
Date mailed: October 12, 2026 · Your coverage ends at 12:01 a.m. on November 26, 2026
Dates
Days are counted from the mailing date to the date cover ends: 45 for this Florida commercial policy. The original date, 11 November, gave 30; the notice was re-dated before mailing, and the letter says cover continues on the same terms and premium until then.
Mangrove Key Marina & Boatyard, LLC · 2280 Tarpon Basin Road, Punta Gorda, FL 33950 · Policy CPP 4471902, commercial package
Named insured and address
The first-named insured, at the address shown in the policy: the address the proof of mailing must match.
Three water-intrusion claims in the past 24 months totalling $412,600, and the roof over dry-storage building B rated poor at the July 2026 inspection.
The specific reason
Florida requires the reason or reasons on a nonrenewal; a reason the insured can check names events, dates, amounts and the source.
A sentence that the law requires the insurer to give the reason, and where to direct questions: the agent, and the state's consumer services division.
State wording and contacts
Required wording varies most by state: California's Department review statement and Home Insurance Finder notice, New York's loss-information line on commercial notices.
Copies: agent, Clay Haddon at Tarpon Bay Insurance Agency · mortgagee, Gulfshore Community Bank
Copies
Everyone the law or the policy names: the agent or broker, and each mortgagee or loss payee, each with its own proof of mailing.
What is a notice of non renewal in insurance?
It is the written notice an insurer must give before letting a policy lapse at the end of its term, and it is required because the insured otherwise expects renewal. Every state on this page makes the notice a condition of nonrenewal and attaches a consequence to getting it wrong: in New York a personal-lines insured who did not get timely notice may renew by paying the premium; in Texas a personal-lines insurer that did not mail it in time must renew if the insured asks; in Florida and California cover continues for a set period after a late notice.
The notice is also a regulated document. In New York's commercial statute, “Every notice of nonrenewal issued pursuant to this section shall set forth or be accompanied by the reason for nonrenewal”, and a notice missing any required provision is not effective. Florida's says that if the policy is not to be renewed, “the written notice shall state the reason or reasons as to why the policy is not to be renewed”. The letter's content, not only its date, decides whether it works.
What does non renewal mean in insurance, and how is it different from cancellation?
Non renewal means the insurer will not offer a new term when the current one expires; cancellation ends a policy before its expiry date. The difference matters because states restrict cancellations far more tightly: after a policy has been in force about 60 days, Florida, New York and California allow cancellation only on grounds the statute lists, while a nonrenewal can rest on any lawful, specific reason, with longer notice. An insurer that re-evaluates a risk mid-term therefore has to wait for the renewal date unless a cancellation ground applies.
There are limits even so. New York requires a homeowners nonrenewal in a policy's first three years to rest on a ground for which it could have been cancelled. Texas forbids nonrenewing personal auto or homeowners policies on the basis of a customer inquiry that did not lead to a claim, and Florida bars using a claim from an act of God as a cause unless the insured failed to take reasonable steps the insurer asked for. The reasons insurers give, and how a homeowner can contest them, are covered in why insurers are non renewing homeowners policies.
Line one: the dates, counted from mailing
The notice needs two dates, the mailing date and the date cover ends, and the gap between them is the clock every state measures. California's rule is written in terms of mailing: “At least 75 days before the policy expiration, the insurer shall deliver the notice of nonrenewal to the named insured or mail the notice of nonrenewal to the named insured at the address shown in the policy.” Since July 2022 a mailed notice also gets the extra days of California's Code of Civil Procedure §1013(a), five within the state.
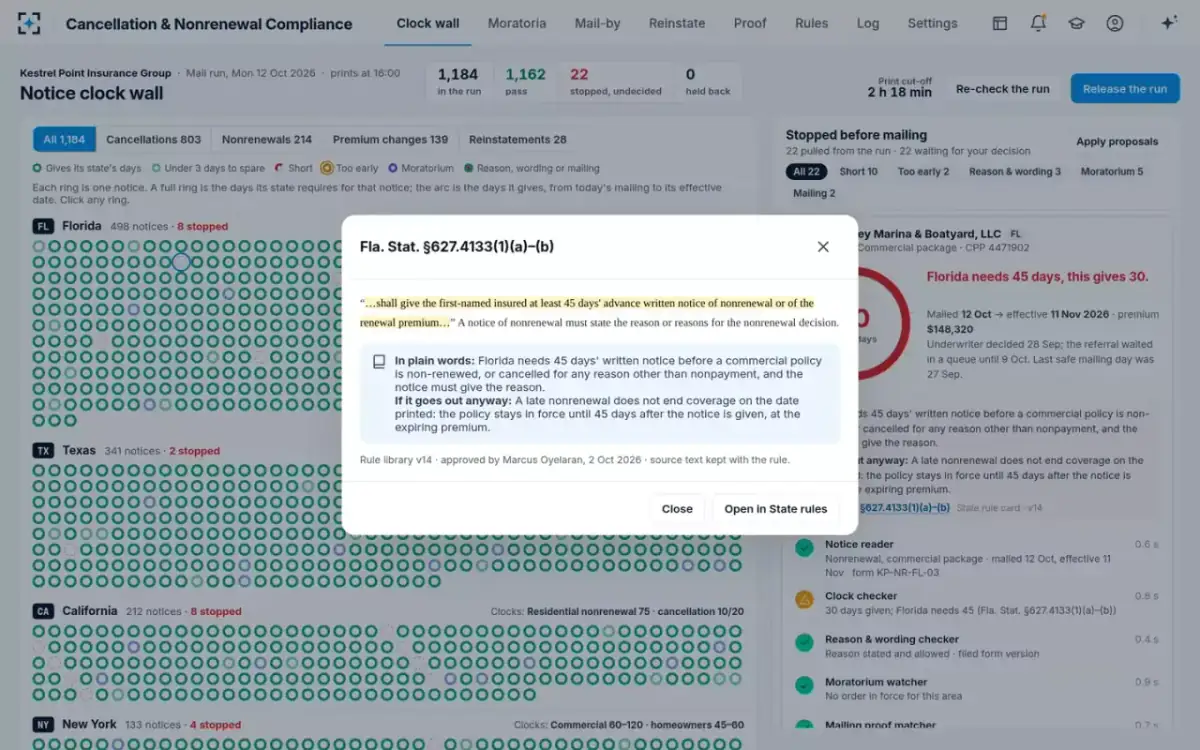
The sample letter's dates show a common repair. As first drafted, the notice gave 30 days against Florida's 45 for a commercial nonrenewal. It was re-dated before mailing so that cover ends on 26 November, 45 days after the 12 October mailing, and it tells the insured plainly that current cover continues on the same terms and at the same premium until then. Mailing the original date would have printed a date the statute had already overridden.
The clock behind line one in Cancellation & Nonrenewal Compliance, with the statute a click away
Line two: the reason, specific enough to check
The reason is the line examiners read most closely, because a category is not a reason. Texas requires a written statement of the reasons for a nonrenewal that names the precise incident, circumstance or risk factor and the source of the information relied on. California's nonrenewal notice must state “The specific reason or reasons for the nonrenewal.” New York's personal-lines statute requires the specific reason or reasons to be stated in or to accompany the notice.
Illinois's 2025 examination of American Freedom Insurance Company shows what fails: four of 86 nonrenewal notices, 4.65%, either cited a claim number with no date of loss or named claims experience or operator history and stopped there. The sample letter's reason passes because it names three claims, a period, a total and a dated inspection of a named building. Who owns that sentence, and who checks it, is the subject of insurance cancelled for underwriting reasons.
Line three: the state's own wording
Required wording is where nonrenewal letters differ most by state, and a single national letter will miss some of it. California is the most prescriptive for residential policies. Its notice must display the insurer's telephone number for consumer inquiries prominently and include a statement that if the consumer has contacted the insurer and remains unsatisfied the Department of Insurance may review the matter, with the Department's website, telephone number and Consumer Services Division address. From July 2021 it must also carry the Department's notice about the California Home Insurance Finder and the FAIR Plan. And a late California nonrenewal must tell the insured, with the notice, that the existing policy continues for 75 days from its delivery or mailing.
New York's commercial nonrenewal must tell the first-named insured and the broker that loss information is available on written request, and Tokio Marine America's $360,000 consent order in 2023 included notices that left it out. Florida's private passenger auto nonrenewal must tell the insured of possible eligibility for the state's Automobile Joint Underwriting Association, and say that the notice of availability is given under the statute. A letter template should carry each state's block as a variable, as set out in the insurance cancellation notice template.
Line four: who the notice goes to
The notice goes to the named or first-named insured at the address shown in the policy, and to everyone else the law or the policy names. Florida's auto statute sends it to the first-named insured at the policy address and to the insurance agent at the agent's business address. New York's commercial statute sends it to the first-named insured and the authorized agent or broker; its personal-lines statute requires a copy or summary to reach the agent or broker within seven days of mailing to the insured.
Mortgagees and loss payees are the copies most often forgotten. The NAIC Market Regulation Handbook's property and casualty procedures (2017 edition) have examiners check that adequate notice reached the insured and any mortgagees or lienholders, and California deems a lienholder's copy of a cancellation notice mailed if, with the lienholder's consent, it is sent electronically, by fax or by hand. In the sample letter both copies are named on its face: the agent at Tarpon Bay Insurance Agency and the mortgagee bank.
Line five: the proof that it was mailed
The fifth line is not printed on the letter at all: it is the postal receipt the carrier keeps. New York makes proof of mailing to the named insured at the address in the policy sufficient proof of notice, and Florida's auto statute lists the postal methods it accepts. Which receipts show that a particular notice went to a particular address, and which only count envelopes, is set out in certificate of mailing vs certified mail. A notice without a matching receipt is, for an examiner, a notice that cannot be shown to have been given.
Notice of non renewal homeowners insurance: what a homeowner can check
A homeowner who receives a nonrenewal notice can test it against the same five lines. Did it arrive in time for the state (120 days in Florida, 60 in Texas, 75 plus mailing days in California, 45 to 60 in New York)? Does it give a specific reason the homeowner can check? Does it carry the state's required statements, such as California's Department review line? Did the agent hear of it? If the answer to any of these is no, the notice may not be effective, and the state insurance department is the place to ask.
Complaints about nonrenewals are fewer than complaints about many other servicing problems, but each one asks the regulator to read the notice. In our count of the Texas Department of Insurance's complaints closed in 2025, nonrenewal was cited in 246, against 926 for cancellation and 1,724 for refunds of premium.
Texas complaints closed in 2025, by servicing reason cited
Nonrenewal notice must include what? The checklist
Put together, the five lines make a short checklist that a cancellation lead, a new compliance analyst or a homeowner can apply in a minute. The sample carrier's agents apply the same list to every nonrenewal in the day's run, and stop any letter that fails one line for a person to decide.
A notice of nonrenewal must include
- The mailing date and the date cover ends
Far enough apart for the state, line and policy, counted from mailing, with California's mailing days added.
- The named insured and the address in the policy
The address the postal receipt must match.
- The specific reason
Events, dates, amounts and source; never a category such as “underwriting reasons” or “claims experience”.
- The state's required wording
For example California's Department review statement and Home Insurance Finder notice; New York's loss-information line on commercial notices.
- The copies
Agent or broker, and each mortgagee or loss payee the policy names.
- A receipt in the file
Postal proof of mailing for this letter, to this address, on the date printed.
Cancellation & Nonrenewal Compliance checks every nonrenewal in the run against its state's lines
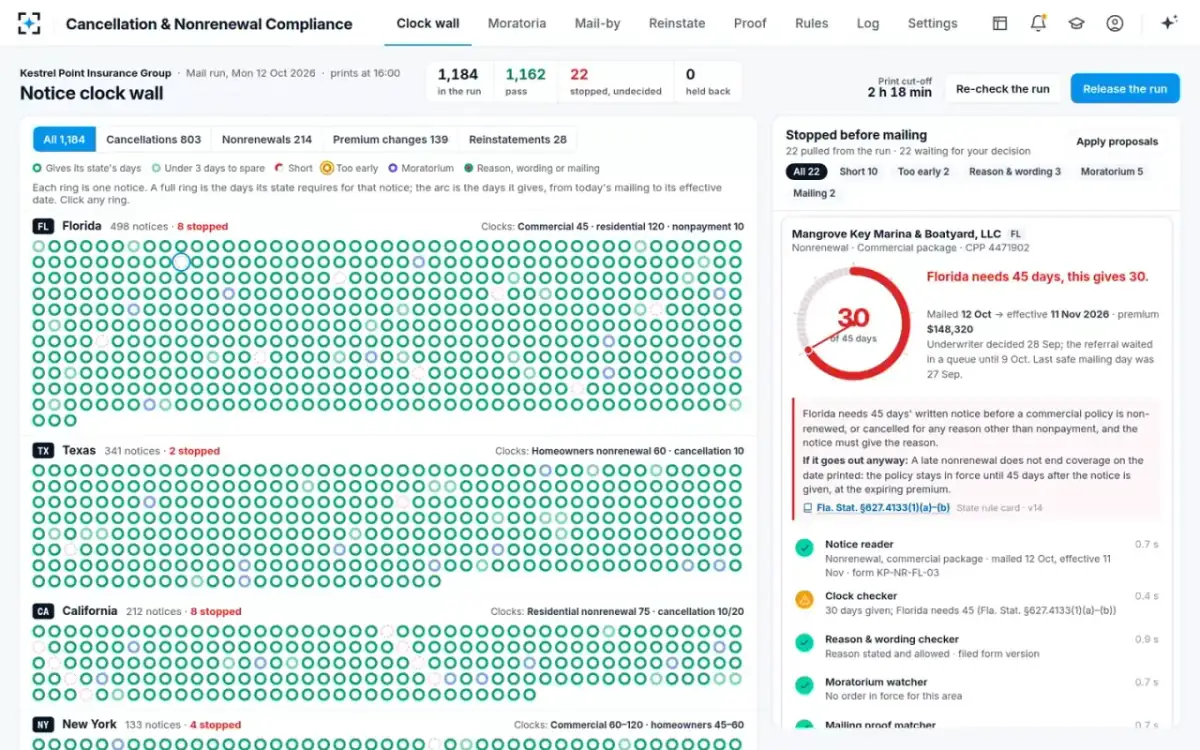
The sample letter's five lines before the re-date: one failed
30of 45
days given on the first draft: line one failed
4of 5
lines passed: reason, wording, address and copies
15days
of extra cover the re-date made explicit, at the expiring premium
To see every nonrenewal in a day's run checked line by line before it prints, start from Cancellation & Nonrenewal Compliance.
Questions people ask
How far in advance must a notice of nonrenewal be sent?
It depends on the state and line. Florida requires 45 days for commercial policies and 120 for residential property; Texas 60 days; California 75 days for residential policies, plus five days for a notice mailed within the state; New York 45 to 60 days for personal lines and 60 to 120 for commercial.
Does an insurance company have to tell you why it is not renewing?
In the four states covered here, yes. Florida, California and New York require the reasons on or with the notice, and Texas requires a written statement of the reasons that names the precise incident or risk factor and the source of the information.
What if I never received the nonrenewal notice?
The insurer generally needs proof that it mailed the notice, not that you received it. New York makes proof of mailing to the address in the policy sufficient proof of notice, so an insurer with a receipt can show notice was given; one without it may be held to renew or extend cover.
Can I appeal a notice of nonrenewal?
You can complain to the state insurance department, and some states build that into the notice: a California residential nonrenewal must say the Department of Insurance may review the matter if the insurer has not resolved it. Florida's formal appeal right in its auto statute applies to cancellations, not nonrenewals.
Is non renewal the same as being dropped by your insurer?
In everyday terms, yes: the insurer will not offer another term. Legally it differs from cancellation, which ends cover mid-term and is far more restricted. A nonrenewed policy runs to its expiry date, or longer if the notice was late.