A premium bordereaux example is easiest to understand as a real month. A premium bordereau is the schedule a managing general agent or coverholder sends its insurer for each period, listing every policy, endorsement, cancellation and instalment it bound or processed under the binding authority, with the premium on each line split into gross, commission, taxes and fees, and net, in the policy's currency. The insurer uses it to know what was written in its name and what money it is owed. Below are nine lines from one fictional delegate's September bordereau, read column by column, with the arithmetic from gross to net and the way each line ties to the cash and the broker's statement of account. Botminds' Premium Bordereaux Reconciliation reads bordereaux like this one in whatever layout the delegate sends, ties them to their totals, and joins every line to the money that paid it.
The example comes from a fictional sample: Northbeam Underwriting Managers in Toronto, which writes Canadian commercial property for a fictional carrier, Cavendale Specialty, in Canadian dollars settled in US dollars at a binder rate of 0.7255 for September 2026 and a commission of 27.5%.
Premium bordereaux example: nine lines from Northbeam's September bordereau
| Insured · policy | Transaction · province | Gross CAD | Commission 27.5% | Net CAD | Net USD at 0.7255 |
|---|---|---|---|---|---|
| Harrow Lake Marina Inc. · NBM-CP-26-04391 | Renewal · ON | 22,400.00 | 6,160.00 | 16,240.00 | 11,782.12 |
| Pinecastle Dental Group · NBM-CP-26-04398 | New business · ON | 9,850.00 | 2,708.75 | 7,141.25 | 5,180.98 |
| Ridgeback Cold Storage Ltd. · NBM-CP-26-04402 | Renewal · AB | 61,200.00 | 16,830.00 | 44,370.00 | 32,190.44 |
| Gannet Bay Seafoods · NBM-CP-26-04405 | New business · BC | 17,300.00 | 4,757.50 | 12,542.50 | 9,099.58 |
| Fairlight Montessori School · NBM-CP-26-04409 | Renewal · ON | 6,940.00 | 1,908.50 | 5,031.50 | 3,650.35 |
| Copperkettle Brewing Co. · NBM-CP-26-04411 | New business · BC | 28,750.00 | 7,906.25 | 20,843.75 | 15,122.14 |
| Kettle Valley Timber Frame Ltd. · NBM-CP-26-04417 | New business · BC | 48,600.00 | 13,365.00 | 35,235.00 | 25,562.99 |
| Lindqvist Auto Body · NBM-CP-26-04420 | Renewal · ON | 12,180.00 | 3,349.50 | 8,830.50 | 6,406.53 |
| Marigold Seniors Residence · NBM-CP-26-04424 | New business · MB | 6,180.00 | 1,699.50 | 4,480.50 | 3,250.60 |
What is a premium bordereau? A definition from statute and court records
A premium bordereau is a delegate's periodic report to its insurer of the premium transactions it bound under a binding authority, line by line, with the totals due. It is the insurer's main window onto business written in its name by someone else, and the basis of the monthly settlement.
US law does not use the word, but it requires the thing. The NAIC's model act requires the MGA contract to provide for accounts "detailing all transactions" at least monthly and for separate records of business written by the MGA (Model #225 §4B, §4D). Texas specifies a quarterly account report covering written, earned and unearned premiums, losses paid, outstanding and incurred but not reported, and management fees (Tex. Ins. Code §4053.103). In the London market the binder names it: the binders in XL v IPORS required monthly premium bordereaux within 15 days of month end, in a format agreed with the insurers, and a summary account of premium gross and net of commission, taxes and other deductions ([2022] EWHC 2093 (Comm), ¶¶9–11).
"Bordereau" is the singular and "bordereaux" the plural, from the French for a schedule or slip. A delegate usually sends a premium bordereau and, if it handles claims, a separate claims bordereau. This guide is about the premium one. What bordereaux processing is covers how carriers load and check both kinds as data.
What columns are on a premium bordereau?
A premium bordereau carries five families of columns: who and what was insured, the transaction, the period, the money, and where the risk is. Binders name the exact fields; the families below are what a carrier needs to apply cash and check the business against the binding authority.
The five families of columns on a premium bordereau, and what each is for
| Family | Typical columns | What the carrier uses it for |
|---|---|---|
| Identification | Policy or certificate reference, insured's name, endorsement number | Joining the line to cash and to the broker's statement; finding unidentified receipts |
| Transaction | New business, renewal, endorsement, cancellation, instalment | Knowing whether cash should arrive, reverse, or arrive later |
| Period | Inception, expiry and transaction dates; bordereau month | Settlement dates, earned premium and the statutory ageing of what is owed |
| Money | Gross premium, commission, taxes and fees, net premium, currency | The settlement figure, the commission check and the exchange rate |
| Risk location and limits | Province or state, sum insured or limit, class of business | Checking territory, limits and classes against the binder's underwriting guidelines |
The last family is where premium bordereaux most often fail as evidence. In Markel v Surety Guarantee Consultants, the bordereaux were the means by which the carrier's manager was meant to check business against the binding authority's limits, and the court found they stated exposures as within limits when bonds had exceeded them ([2008] EWHC 1135 (Comm), ¶¶29, 85). A premium column can be right while the limit column is false.
How is net premium calculated on a bordereau?
Net premium is gross premium less the commission the binder allows, less any taxes and fees the binder lets the delegate deduct or that are collected for someone else; the carrier then converts it at the binder's rate of exchange if the policy and settlement currencies differ. Every step uses a figure from the binder, so the bordereau's net can be recomputed by anyone holding the binder.
From gross premium to the amount the carrier is owed, one line
Gross premium
The premium charged to the insured, in the policy currency
Ridgeback Cold Storage: CAD 61,200.00
Bordereau
Commission
Gross × the binder's commission rate
61,200.00 × 27.5% = CAD 16,830.00
Binder schedule
Taxes and fees
Amounts the binder lets the delegate deduct or that belong to others
None on this line; a CAD 350 inspection fee on another line belonged to the delegate
Binder schedule
Net, at the binder rate
Net premium × the binder's rate of exchange
CAD 44,370.00 × 0.7255 = USD 32,190.44
Settlement
That line is also where the example went wrong. The bordereau showed commission at the binder's 27.5%, but the cash and the broker's statement both showed $31,050.43, not $32,190.44. Northbeam had deducted 30.0% when it remitted: CAD 1,530.00 more than the binder allows, or $1,110.02 at the binder rate; the rest of the $1,140.01 gap came from the wire converting at 0.7248 rather than 0.7255. Two commission lines in the month came to $3,912.50 over-deducted, recovered through the settlement.
Ridgeback Cold Storage's gross premium: as the binder splits it, and as it was remitted
Bordereau, at the binder's 27.5%
- Commission · 27.5%
- Net to the carrier · 72.5%
Cash, at the 30.0% the delegate deducted
- Commission · 30%
- Net to the carrier · 70%
The lines that cause trouble: endorsements, cancellations, instalments and currency
Four kinds of line cause most premium bordereau differences, and each appears in Northbeam's month. None is an error in itself; each becomes one if the bordereau, the cash and the statement treat it differently.
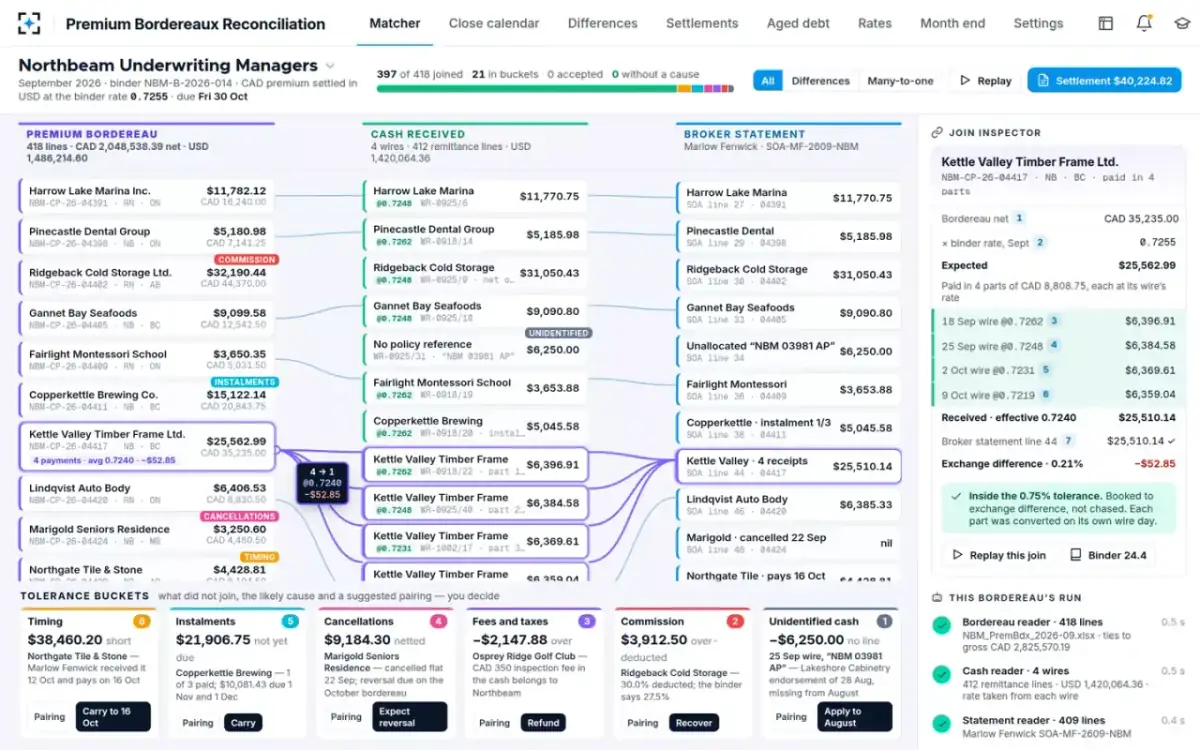
Endorsements. An additional-premium endorsement on Lakeshore Cabinetry's policy, bound on 28 August, never appeared on the August bordereau; its $6,250.00 arrived on 25 September with only "NBM 03981 AP" as a reference. Cancellations. Marigold Seniors Residence was cancelled flat on 22 September, notice CN-0922: nil on the broker's statement, and a reversal due on October's bordereau, so its $3,250.60 line should never be chased. Instalments. Copperkettle Brewing pays in three instalments of CAD 6,947.92; one was paid in September and the other two fall due on 1 November and 1 December. Currency. Kettle Valley Timber Frame was paid in four wires at four rates, $52.85 short of the line at the binder rate, inside the carrier's exchange tolerance.
Premium Bordereaux Reconciliation's matcher: bordereau, cash and broker's statement side by side
How does a premium bordereau tie to cash and the broker's statement?
A premium bordereau ties to cash line by line, through the remittance advice, and to the broker's statement through the same policy references; the totals agree only after timing, instalments, cancellations, fees, commission and exchange differences are accounted for. Tying totals first hides the lines that cancel out.
Northbeam's September bordereau declared net premium of $1,486,214.60 at the binder rate. Four wires brought $1,420,064.36, about 95.6% of it. The rest was explained line by line: $38,460.20 of premium in transit at the cut-off on six lines, $21,906.75 of instalments not yet due, $9,184.30 of cancellations to reverse, $3,912.50 of over-deducted commission and $1,084.37 of exchange difference, less $2,147.88 of fees that came in with the cash and the $6,250.00 receipt that belonged to August. After setting aside what was not yet owed, the settlement was $40,224.82, due on 30 October.
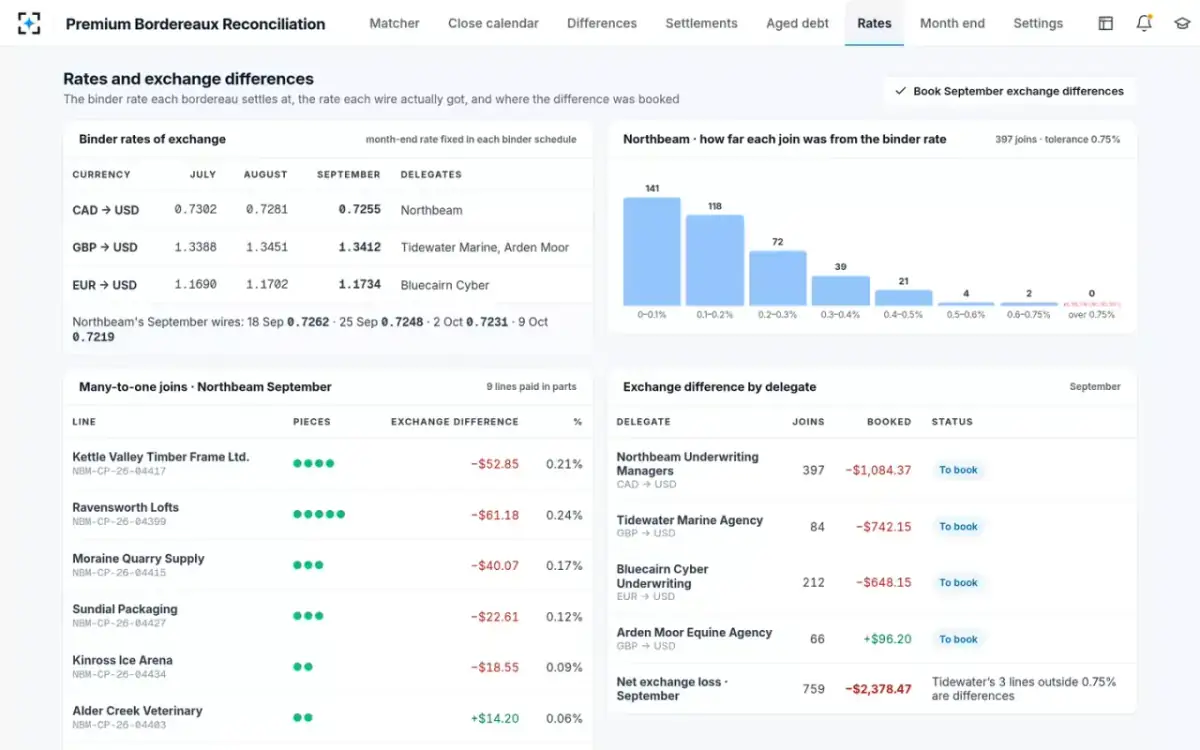
Binder rates by month in Premium Bordereaux Reconciliation, and how each part-payment converted
Which exchange rate belongs on each bordereau line?
The rate the binder fixes for the month the line belongs to, not the rate on the day the money moved. A premium bordereau in a policy currency that settles in another needs one rate per month, written into the binder schedule, so that the carrier and the delegate compute the same settlement figure from the same lines.
Northbeam's binder fixes a month-end Canadian-to-US rate for each month: 0.7302 for July, 0.7281 for August and 0.7255 for September. Every September line converts at 0.7255, whatever its wires achieved. A line that belongs to an earlier month converts at that month's rate, which is why the Lakeshore Cabinetry endorsement, bound on 28 August, was valued at 0.7281 when its stray $6,250.00 wire was paired to it in October. The wires themselves convert on their own days, and the gap between the two is an exchange difference: −$1,084.37 across Northbeam's 397 joined lines in September, all inside the carrier's 0.75% tolerance.
Two things go wrong when a bordereau omits the rate. The delegate converts at the wire rate and the carrier at the binder rate, so every line disagrees by a few cents and the real differences hide among them. Or a late-reported line is converted at the current month's rate, so the settlement is off by the movement between months. A rate column, with the month it applies to, prevents both.
What a premium bordereau cannot tell you
A premium bordereau tells the carrier what the delegate says it bound; it cannot tell the carrier what the delegate left out. In XL v IPORS the coverholder's bordereaux were consistent with themselves while premium was being under-declared; the gap was found from bank statements and third-party evidence, not from the bordereaux ([2022] EWHC 2093 (Comm), ¶¶34, 55). The honest version of the same problem is the Lakeshore endorsement: bound, paid, and simply missing from the month it belonged to.
That is why a premium bordereau needs a second source every month. Cash shows what arrived; the broker's statement shows what an independent intermediary says it received and passed on. A line on the statement or a wire with no bordereau line is the earliest sign of an omission. The premium bordereaux reconciliation report sets out the three tests a balanced report still has not passed.
A checklist before you accept a premium bordereau
Nine checks before a carrier accepts a delegate's premium bordereau
- The lines add up to the file's own totals
Gross, commission, taxes and fees, net: a bordereau that does not tie to itself is not ready to match.
- It arrived on the binder's day
Fifteen days after month end in the binders a court examined, and in the sample's defaults.
- Every line has a policy or endorsement reference
The reference is what joins it to cash; a missing one becomes unidentified cash later.
- Commission matches the binder's rate
Recompute from gross; a delegate may report one rate and remit at another.
- The rate of exchange is the binder's for that month
Not the rate on the wire day; the difference belongs in an exchange account.
- Cancellations and endorsements carry their dates
So reversals and additional premium land in the right month.
- Instalments show what is due and when
So instalments not yet due stay out of the settlement figure.
- Territory, limits and classes fit the binder
The model act's underwriting guidelines include territorial limitations and maximum limits.
- Last month's open items are answered
A missing endorsement or an unreversed cancellation should appear, not recur.
Premium Bordereaux Reconciliation runs most of these checks as it reads: the bordereau reader ties lines to totals and flags an amount it cannot read rather than guessing, the matcher joins each line at the binder rate and shows both rates on every join, and the difference explainer names the cause of every line that will not join. A person accepts every pairing; the settlement is drafted for a person to approve and send. For UK coverholders, the reconciliation sits alongside, not instead of, the firm's own client money reconciliations under CASS 5.5. To see the joins on a month of your own bordereaux, start from Premium Bordereaux Reconciliation; how the matching agent works follows the cash side in detail.
Questions people ask
What is a premium bordereau in insurance?
The schedule a delegate, such as an MGA or coverholder, sends its insurer each period listing the policies, endorsements and cancellations it bound, with premium from gross to net. It is the basis of the monthly settlement and of the insurer's check that business stayed inside the binding authority.
What is the difference between a premium and a claims bordereau?
A premium bordereau reports premium transactions and the money owed to the insurer; a claims bordereau reports claims notified, paid and reserved by a delegate with claims authority. Texas's quarterly MGA account report combines both kinds of figure, and many binders require both monthly.
How often is a premium bordereau sent?
Usually monthly. The binders in XL v IPORS required monthly premium bordereaux within 15 days of month end, and US MGA law requires accounts of all transactions at least monthly. Some binders allow a nil return when there was no activity.
Can a premium bordereau be sent as a PDF?
It can if the binder allows it, but a spreadsheet or CSV in an agreed layout is easier to check and reconcile. Premium Bordereaux Reconciliation reads each delegate's layout as a spreadsheet, CSV or PDF and ties the lines to the file's totals before matching.
What does "net" mean on a premium bordereau?
Premium after the delegate's commission and any permitted deductions: the amount the insurer should receive for that line. In the sample, net is 72.5% of gross under a 27.5% commission, converted to US dollars at the binder's monthly rate.