The cost of keeping a state lending license for a year has five parts: the state's own license and branch fees, the NMLS processing fee, the premium on the surety bond the state requires, the capital the company holds to meet the state's net worth minimum, and the staff time to renew, report and notify on time. The fees are published and predictable. The time is not, and neither is the cost of the one thing a licensing team exists to prevent: a lapse that stops the company lending in a state. For a lender licensed in thirty states or more, this work usually rests with one or two specialists and a manager. Botminds' Lender License Management is built to take the reading and drafting off them. This guide builds the yearly cost of a license from its parts, says plainly where no public benchmark exists, and gives a return formula to fill in with your own figures.
Where one renewal season's working days go at a 34-state lender, by hand (our estimate)
How much does it cost to maintain a mortgage license?
Less in fees than most finance teams assume, and more in time and risk than most licensing budgets show. The fees for one license are published and fixed in advance: a state fee, an NMLS fee and branch fees. The staff time is spread across the year but lands hardest in the eight weeks of renewal season, when the same one or two people must also file a quarterly call report and any change notices that fall due. The cost that dominates, when it happens, is a lapse: days in which the company cannot take applications in a state, plus the penalties and disclosures that follow.
What is the mortgage license renewal cost in fees?
A state renewal fee that varies by state and license type, plus an NMLS processing fee that does not: $120 for each company license, $25 for each branch and $35 for each loan originator license (NMLS). Four costs appear on an invoice or a balance sheet. Each state sets its own license, renewal and branch fees, and some collect them outside NMLS; on a fictional sample lender, Calder Ridge Lending, the California finance lender renewal carries a fee of $1,050. The NMLS fees rose on 1 March 2025, "the first since the NMLS was launched in 2008" (CSBS, February 2025), from $100, $20 and $30 (CSBS, May 2024). Paying by card adds 2.5%; ACH adds nothing (NMLS).
The surety bond is priced by the surety as a premium on the bond amount, which each state sets. California's scale shows how much the amount can move: finance lenders that originate residential mortgages need a bond of $25,000 up to $1 million of loans, $50,000 to $50 million, $100,000 to $500 million and $200,000 above that (DFPI). The net worth minimum is a capital cost rather than a cash one; California requires $25,000 at all times, or $250,000 for a licensee that employs loan originators and makes residential mortgage loans.
The visible costs of one license, from published figures
$120
annual NMLS processing fee for each company license, up from $100 in March 2025
$200k
top of California’s bond scale for finance lenders that originate mortgages; it starts at $25,000
$250k
California net worth minimum for a finance lender that employs loan originators and makes mortgages
The hours you cannot see
The hours are the larger cost and the less measured one. No regulator, academic or non-profit body publishes a benchmark for licensing hours per license, so any figure is an estimate and should be labelled as one. Ours, for a renewal season at a lender with about 60 licenses in 34 states, is about 30 working days by hand: 240 hours. At the May 2025 mean wage for compliance officers in credit intermediation, $94,090 a year or about $45 an hour before benefits and overhead (BLS OEWS), that is roughly $10,900 of wages for the season, or about $180 per license.
That number is smaller than many people expect, and it understates the problem in two ways. First, it covers only renewal season. Call reports four times a year, state annual reports, branch amendments and every officer, owner or address change add their own hours. Second, it is a peak: 30 working days of load in a window of about 40 working days falls on one or two people who are also answering every other question the business asks. The St. Louis Fed found personnel to be "by far, the largest category" of compliance cost at every size of bank it studied, with the smallest institutions carrying the highest share (St. Louis Fed, 2016). Licensing teams at non-bank lenders are small in the same way.
What does a missed license renewal cost?
Lending days first, re-application second and penalties third. NMLS is blunt about the first two: a company license not renewed by 31 December "is considered expired", the company "immediately loses its authority" in that state, and the lapse can take the branch licenses and loan officer sponsorships with it, so that "re-applying for these licenses may involve significant time and expense" (NMLS). Maryland shows both edges: a renewal filed less than two calendar weeks before expiry means the lender "shall cease processing and closing loans when the license expires" if it has not been approved, and a renewal more than 30 days late means a new application with all its fees (COMAR 09.03.06.04). In Virginia, a branch office not renewed by 1 March "shall be deemed to be closed as of the preceding January 1" (10VAC5-160-90).
What a lost week is worth depends on the state's share of the business. On the sample lender's third-quarter call report, California accounts for 508 applications and 295 closed loans worth $91.45 million in 92 days; on that pace, each week without the license would put roughly 22 closings and about $7 million of loan volume at risk, before any penalty. That is our arithmetic on fictional sample data, offered as the method, not a benchmark.
What missed licensing duties have cost, in state orders
| Duty | State | Cost |
|---|---|---|
| Address change not notified ten days ahead | California | Civil penalty up to $500 |
| Annual financial condition report filed late | Connecticut, 2016 | $4,500, and a reportable NMLS disclosure in every state after |
| Notice of an event the rules require reporting | New Jersey, 2026 | $10,000 and revocation (alongside a fraud count); up to $25,000 per violation |
| Unlicensed staff doing originator work | California, 2025 | $160,000 plus $500 per unlicensed employee found |
| Lending without the license | California, 2026 | $4 million |
Why the cost grows faster than the number of states
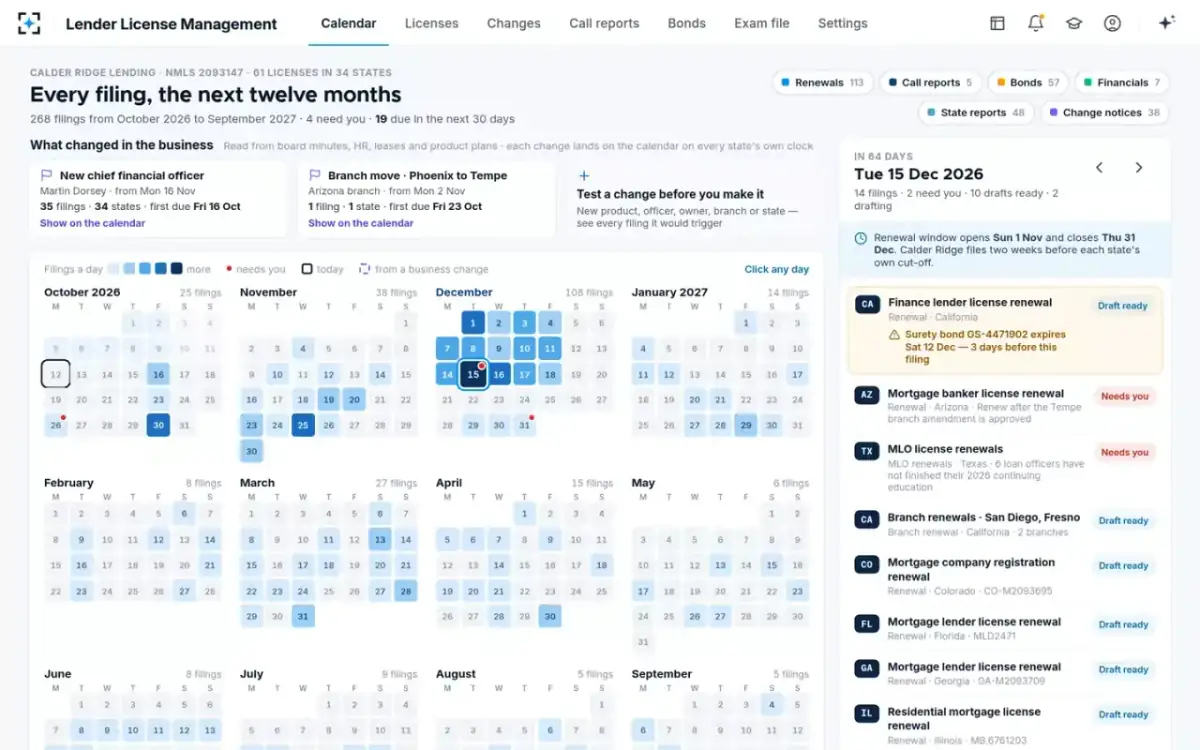
Fees grow in proportion to licenses; the work does not. A renewal is one filing per license, but a business change is one filing per state for every change. On the sample lender, one new chief financial officer produced 35 filings, a company amendment and a notice in each of 34 states on four different clocks. A lender in five states would have filed six. Every officer, owner, branch or product change multiplies the same way, and each state's clock has to be read from that state's rule, because the clocks do not agree.
Rules multiply the reading too. Each state's licensing law, regulations, regulator guidance and NMLS checklist has to be read for each license type the lender holds, and re-read when it changes. Our estimate puts six of a season's 30 working days on that reading alone. It is the part of the cost that grows with every state added, whether or not anything in the business changes, and it is the part most often done from memory or from last year's notes.
The cost also falls on people outside licensing. Finance pays and approves bond premiums and produces the net worth figure each state counts its own way. HR holds the officer list and sponsors loan originators. The corporate secretary holds the minutes. Each of those teams spends time answering licensing's questions, usually in November, and none of that time appears in a licensing budget.
Can mortgage license renewals be automated?
The submission already is, in bulk; the work that makes a renewal true is what teams often still do by hand, and that is where automation pays. NMLS gives large companies a Renewal Dashboard that processes renewals by entity type or jurisdiction, and smaller ones a Renewal Selection List that can "renew all of the licenses at once" (NMLS). Pressing renew on sixty licenses takes minutes. What takes weeks is the precondition NMLS sets for every company: confirm the records are current, attest to their accuracy, clear outstanding license items and make sure sponsored originators have finished their education (NMLS).
That precondition is reading and comparison: each state's checklist against the license, NMLS against HR and the leases, each bond against the renewal it secures, each officer change against each state's clock. It is the work an agent can do every morning instead of every December. The attestation is the part no software should take over, because it is the company's statement to the regulator; an honest automation plan leaves that line exactly where it is and moves everything before it.
What to automate in a renewal season, and what to keep
| Task | By hand (our estimate) | With agents (our estimate) | Who still owns it |
|---|---|---|---|
| Reading each state’s rules and renewal checklists | 6 days | 0.5 day | Licensing manager, for ambiguous rules |
| Pulling and comparing records: NMLS, HR, leases | 5 days | 0.5 day | Licensing, for each difference found |
| Drafting renewal answers with sources | 10 days | 2 days of review | Licensing, reviewing every draft |
| Bonds and continuation certificates | 3 days | 0.5 day | Finance approves each premium |
| Change notices, state by state | 4 days | 0.5 day | Compliance signs off change of control |
| Attesting and filing | 2 days | 2 days | The licensing manager, always |
Is license management software worth the cost?
For a lender in a handful of states, often not on hours alone; for one in thirty, the case rests on the lapse it prevents rather than the hours it saves. The arithmetic is worth doing honestly. On our estimate, a season falls from 240 hours to about 48. At the BLS mean wage above, the 192 hours returned are worth about $8,600 in wages before benefits and overhead. That is a real saving and a modest one. Set against it, one week without the license in a large state, on the sample lender's California pace, puts about $7 million of loan volume at risk. The return on licensing software is mostly an insurance calculation, and the formula below treats it that way.
The return on doing licensing differently has three gains and one cost, and each can be priced from figures a licensing manager and a controller already hold. Hours are the easy term. The terms that move the answer are the lapses and penalties avoided: a single avoided week without a license in a large state can outweigh a year of hours.
The return on Lender License Management, as a sum you fill in
Hours returned
(hours by hand − hours with agents) × loaded hourly rate
Renewal season, call reports, state reports and change notices, counted for a year. Our estimate for one season: 240 hours by hand, about 48 with the agents.
Licensing Manager
Lapses avoided
chance of a lapse × days without a license × value of a day’s lending in that state
Use your own history of near-misses and late filings, and each state’s share of applications from the call report.
Controller with Licensing
Penalties and disclosures avoided
late or missed filings a year × typical penalty in your states
Add the cost of disclosing an order at every renewal in every state.
Chief Compliance Officer
Cost of the solution
subscription + setup + the team’s review time
Review and attestation stay with your people; budget their time.
Controller
Where Lender License Management changes the sum
The solution moves cost out of the peak and aims the lapse term at zero. Its agents re-read each state's rules every Monday and the company's NMLS records every morning, place every filing on its clock, and start drafting 60 days before each is due, a design target. Its bond watcher sets every bond against the renewal it secures; on the sample lender, three of 61 bonds run out days before their licenses renew, found in October rather than December. The design target for missed renewals and filings across all 34 states is zero. The hours that remain are review and attestation, which stay with people because the filings are theirs. The bond case shows one avoided lapse in detail, and what you bring on day one covers the setup cost.
What a blocked renewal looks like before it is a lapse
Questions people ask
How much does an NMLS license cost per year?
The NMLS processing fee is $120 for a company license, $25 for a branch and $35 for a loan originator license each year, raised in March 2025 for the first time since 2008. The state's own license fee is set separately, and it varies by state and license type.
Are NMLS renewal fees different by state?
The NMLS part is the same in every state; the state part is not. Each state's renewal checklist in NMLS lists its own fee, any late fee and any amount collected outside the system, and a multistate lender pays one of each per license.
Does automating renewals change who attests?
It should not. In NMLS the attestation is made by an authorized person at the company; automation can prepare every answer and queue every filing, but the person who attests should have read what they attest to.
How long does a renewal season take by hand?
No public benchmark exists. Our estimate for a lender with about 60 licenses in 34 states is about 30 working days of licensing time, of which only two are attesting and filing; the rest is reading, gathering and drafting.
Is a surety bond a cost or a deposit?
A cost. The company pays the surety a premium each year to keep the bond in force; the bond amount itself is a guarantee the surety stands behind, not cash the lender sets aside.