You usually cannot buy a new homeowners policy during a hurricane watch in Florida if the property is in the area the watch covers: carriers that use binding restrictions suspend new business, coverage increases and deductible decreases there from the watch until the area lifts, and no Florida statute requires them to keep writing. Outside the watch area, buying is normal. Inside it, three kinds of request still have a route: a renewal on the same terms continues, a replacement for a policy that has not lapsed can be approved by an underwriter, and a change the insured signed before the watch can be too. A house purchase closing this week is new business and usually waits. Botminds’ Binding Restriction Management, a system carriers use to set and lift these restrictions by ZIP code, routes each such request to an underwriter with the rule that decides it and a recommendation, and tells the agent the answer and the reason.
The examples come from fictional sample data in the solution: a carrier called Brackwater Mutual, Hurricane Delphine and the homeowners named below. The weather definitions, Florida law, federal flood law and mortgage rules are real and linked; every carrier’s binding rules differ, so ask the agent which ones apply.
Four clocks a buyer meets when a storm is coming
48h
before tropical-storm-force winds, when a hurricane watch is posted and new business typically stops
30
days before most new federal flood policies take effect
0
days of flood wait when the policy is bought for a loan being made, increased, extended or renewed
2h
for an underwriter’s decision on an exception request, in the sample carrier’s notice
Can you buy homeowners insurance during a hurricane watch in Florida?
Usually not as new business in the watch area, and the reason is the carrier’s, not the state’s. Florida’s statutes regulate how insurers cancel and nonrenew, and after a declared emergency the Commissioner’s orders freeze those actions, but nothing we found in Florida law tells a carrier whether to bind a new policy during a watch. The 2024 Milton order expressly left new policies written from 8 October 2024 outside its freeze (OIR Emergency Order 400473-24; the order and the carriers’ own rules are set out in hurricane binding restrictions in Florida). Binding is left to each carrier’s rules, which is why two carriers can give a buyer different answers on the same morning.
The rules follow a common logic. A policy bound the day before landfall collects a day of premium and pays a full claim, so carriers stop the business that can be bought because a storm is coming, and let the business that already existed carry on. The tree below is the sample carrier’s version; its middle rows are where judgement comes in.
In a suspended ZIP code: which requests can still bind, and who decides
- 1
Is the property in a ZIP code under the carrier’s binding restriction?
YesGo on.
NoBind as normal. A watch elsewhere in the state does not affect it.
- 2
Is it a renewal of an existing policy on the same terms?
YesContinues. Renewal offers already sent stand.
NoGo on.
- 3
Is it a coverage increase or a lower deductible on an existing policy?
YesSuspended until the ZIP code lifts.
NoGo on.
- 4
Is it a change the insured signed before the watch was posted?
YesAn underwriter decides, with the signed request as evidence.
NoGo on.
- 5
Does it replace a policy that has not lapsed, with proof of the prior insurance?
YesAn underwriter decides. A gap of even a day is a lapse.
NoGo on.
- 6
Is it new business, including a house purchase closing this week?
YesHeld: the quote and its rate are kept, and it can bind when the ZIP code lifts.
When can you not buy hurricane insurance in Florida?
In practice, from the moment a carrier’s binding restriction covers the property until it lifts. Hurricane cover in Florida is mostly bought inside a homeowners policy rather than on its own: the state had 4,141,774 homeowners multi-peril policies and 69,597 wind-only policies at 30 September 2025 (Florida OIR). So the question is when a carrier will bind a homeowners policy at all, and the trigger is the National Hurricane Center’s watch or warning for the area.
There is no fixed season-wide blackout. A buyer in Tallahassee during a watch on the southwest coast is not affected; a buyer in a coastal ZIP code inside the watch is. How long it lasts depends on the carrier’s lift rule. The sample carrier lifts each ZIP code when the watch is discontinued, no warning or evacuation order is in force, reported damage is below 4 claims per 1,000 policies and two people sign; for Hurricane Delphine that reopened 74 of 97 ZIP codes within three days of the watch being posted.
Hurricane watch vs warning: which one stops a new policy?
Either can, depending on the carrier; the watch comes first, which is why a carrier that wants two days of protection keys its restriction to it. A hurricane watch means hurricane-force winds may reach the area and is issued 48 hours before tropical-storm-force winds are expected; a warning means they are expected there and is issued 36 hours before (NHC glossary; how carriers key restrictions to each is in when insurance companies stop writing policies in hurricane season).
Hurricane watch vs warning, and what each means for a policy
Hurricane watch: Winds of 74 mph or more are possible in the area.
Hurricane warning: Winds of 74 mph or more are expected somewhere in the area.
Hurricane watch: 48 hours before tropical-storm-force winds.
Hurricane warning: 36 hours before tropical-storm-force winds.
Hurricane watch: New business and increases suspended in the watch ZIP codes.
Hurricane warning: The same, in the warning ZIP codes.
Hurricane watch: No effect on its own.
Hurricane warning: Starts the statutory duration of a hurricane: cancellations and nonrenewals due during it are extended.
The warning matters for one more reason. Under Florida law the duration of a hurricane begins when the National Hurricane Center issues a hurricane warning for any part of the state (Fla. Stat. §627.4025), and a cancellation or nonrenewal that would take effect during it is pushed to the end. That protects existing policyholders statewide; it does nothing for a buyer who has no policy yet. How Florida’s rules protect a policy after a hurricane covers that side.
Three requests on one watch morning, and how each was decided
Exception requests are where a written rule earns its keep, because the circumstances are always slightly different. On the sample storm four arrived within the hour; two met the rules and two did not. Three of them show the routes most agents meet.
Three exception requests in suspended ZIP codes
| Request | The circumstances | Rule | Outcome |
|---|---|---|---|
| Replacement, St. Petersburg | Current policy expires 15 October; new policy to start the same day; prior declarations page attached | §4.3: replacement with no lapse and proof of prior insurance | Meets the rule; the underwriter can approve |
| Replacement after a nonrenewal, Port Charlotte | Prior carrier nonrenewed him on 10 October; asks to bind from 12 October | §4.3 requires no lapse; a two-day gap is a lapse | Recommended: decline, keep the quote held; refer to the state market or bind after the lift |
| House purchase, Bradenton | Closing this week; no prior policy on this house | New business, not a replacement: §4.1(a) | Held: the quote and its rate are kept until the ZIP code lifts |
An exception request in Binding Restriction Management, with the rule that decides it
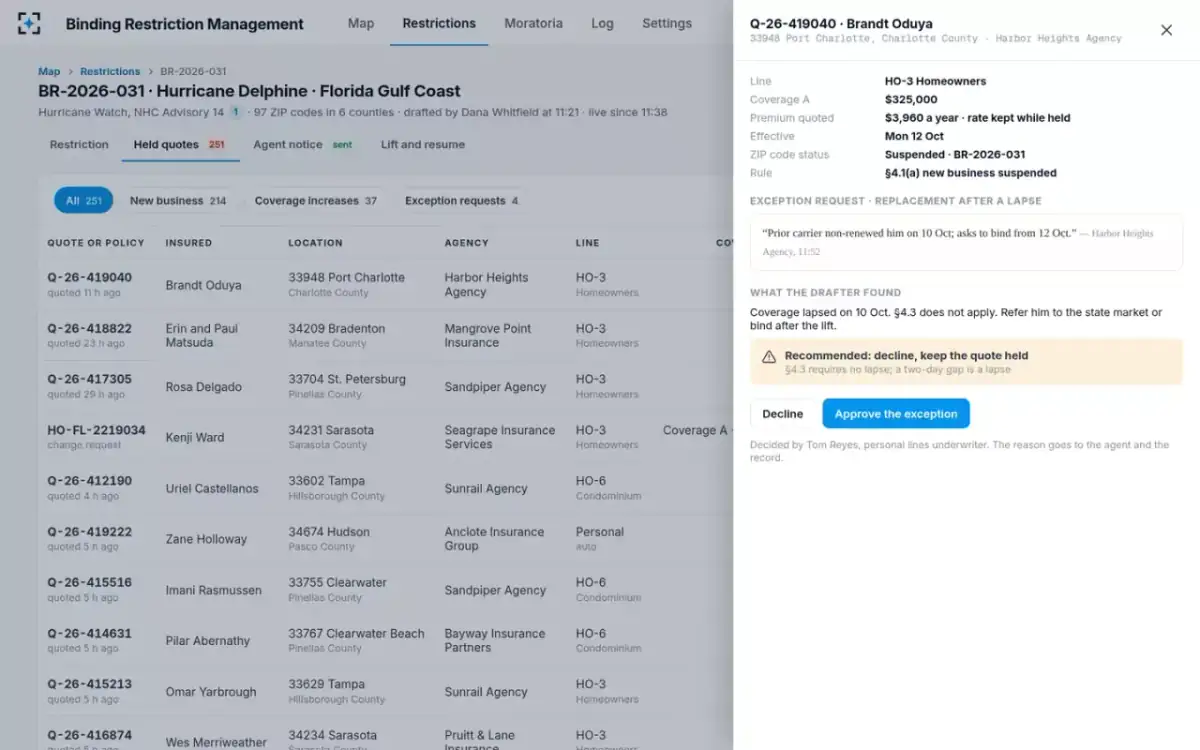
The Port Charlotte case is the hard one, and it is common in a market where nonrenewals rise. The rule exists to let a homeowner move between carriers without a gap; it does not exist to let someone without cover buy it as a storm arrives, and a two-day gap puts him in the second group. The recommendation keeps his quote and rate, so he can bind the moment his ZIP code lifts.
Buying a house when a storm is coming
A purchase closing during a watch is the request agents dread, because the buyer has no policy to replace and the lender needs one. Fannie Mae’s Selling Guide requires the lender to “verify the existence of a valid insurance policy” and warns that “If a lender is unable to determine whether the applicable insurance policy meets Fannie Mae’s requirements, the associated loan is not eligible for purchase by Fannie Mae” (Selling Guide B7-3-07). A loan without a verified policy is not one Fannie Mae will buy, so in practice the closing waits.
Two things help. The first is timing: a policy bound before the watch is posted stands, so a buyer closing in August or September should bind as soon as the contract is firm, not the day before closing. The second is the fallback the guide allows: Fannie Mae accepts policies from a state FAIR plan or “other state-mandated windstorm and beach erosion insurance pools” if they are “the only coverage that can be obtained at the time of the loan closing or policy renewal” (Selling Guide B7-3-01). Whether such a plan will bind during a watch is its own rule to check.
Flood insurance runs on its own 30-day clock
Flood is a separate policy with a separate clock, and federal law sets it. New National Flood Insurance Program coverage “shall become effective upon the expiration of the 30-day period beginning on the date that all obligations for such coverage (including completion of the application and payment of any initial premiums owed) are satisfactorily completed” (42 U.S.C. §4013(c)). Buying flood cover when the watch goes up does nothing for that storm.
The exception matters to home buyers: the 30 days do not apply to “the initial purchase of flood insurance coverage under this chapter when the purchase of insurance is in connection with the making, increasing, extension, or renewal of a loan.” A flood policy required for a mortgage at closing can take effect at closing, even when the homeowners policy is held. For how the two policies divide one storm’s damage, see hurricane insurance vs flood insurance.
Can’t get insurance with a hurricane coming to Florida? What still works
Four routes remain when the answer is no. Ask whether the property is really inside the restriction: a carrier that draws by ZIP code may be writing a few miles inland, where one that draws by county is not. Ask for the rule and the exception route in writing, so a replacement with no lapse reaches an underwriter rather than a voicemail. Keep the quote: in the sample carrier’s rules a held quote keeps its rate until the ZIP code lifts. And watch the lift notice, which in the sample listed each agency’s own reopened ZIP codes and quotes.
What does not work is binding by phone and hoping. A binder in Florida can be oral and carries the policy’s usual terms (Fla. Stat. §627.420), which is exactly why a carrier that means its restriction blocks the bind in the quoting screen rather than relying on agents to remember a bulletin. The sample carrier’s restriction stops new business at the quote screen in every suspended ZIP code.
What agents and closing agents should have in writing
The fastest exception decision is the one where the underwriter has everything on the first request. The sample carrier’s notice asked agents to attach the prior declarations page, and promised a decision within two hours.
Before you ask for an exception during a watch
- The prior policy’s declarations page
Showing the carrier, the policy number and the expiration date. Without it, “no lapse” is an assertion, not evidence.
- The exact dates
The prior policy’s last day and the requested effective date. A one-day gap changes the answer.
- Any change request signed before the watch
With its signature date and time; the watch’s advisory time is public and will be compared.
- For a purchase: the closing date and the lender’s requirement
Ask the lender what it will accept if the homeowners policy is held, and bind flood now if it is required.
- The quote reference
So the rate held with it is the rate that binds when the ZIP code lifts.
- The restriction and the lift notice
Which ZIP codes, from when, and the conditions for lifting, so you can tell the buyer what to expect.
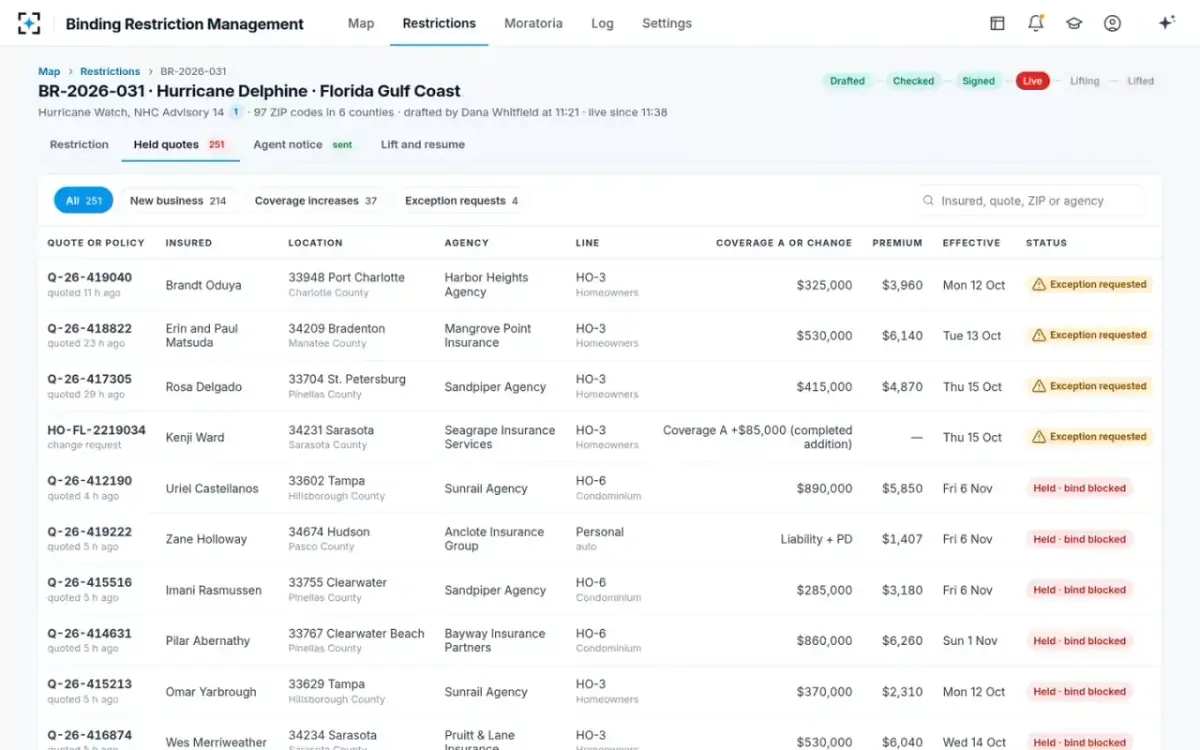
Binding Restriction Management: every held quote and change, exception requests marked
Questions people ask
Can I buy insurance during a hurricane watch in Florida for my home if I already have a quote?
Not until the restriction lifts, unless the quote was bound before the watch. A quote is an offer; only the bind creates coverage. The sample carrier holds the quote and its rate, so it can be bound as soon as the ZIP code reopens; ask your agent whether yours does the same.
Can you get hurricane insurance in Florida?
Yes. Florida law defines hurricane coverage as coverage for loss caused by the peril of windstorm during a hurricane, and it is bought as part of a homeowners policy or, where wind is excluded, as a wind-only policy, a market in which Citizens held 75.36% of policies at 30 September 2025. Flood is a separate policy with its own waiting period.
Should I buy insurance before a hurricane in Florida, even if closing is weeks away?
Bind as early as the purchase is firm. Once a watch covers the property, new business usually stops, and the lender will need a bound policy at closing. If flood cover is required, buying it for the loan avoids the 30-day wait.
Does a hurricane watch stop my policy from renewing?
No. Renewals on the same terms usually continue during a binding restriction, and Florida law pushes the other way: a cancellation or nonrenewal that would take effect during a hurricane’s duration is extended until the duration ends.
How soon after a hurricane can I buy homeowners insurance?
When the carrier lifts your ZIP code, which can be days after the watch is dropped, or longer where damage is heavy. In the sample, 74 of 97 ZIP codes reopened about three days after the watch was posted, and 23 around the landfall area stayed held for damage review.