A flood zone determination is the finding of which FEMA flood zone a building stands in, read from the current effective Flood Insurance Rate Map at the building's own location, with the map panel and date that support it. For a lender it is a federal form; for a commercial property underwriter it is a column on the schedule of values that has to be right for every location before a flood model or a price can be trusted. The hard part is not the map. It is the point: a schedule of forty buildings arrives with partial addresses, and a zone read at a postal-code centre or a parcel centre belongs to somewhere else. Botminds' Schedule of Values Validation places each location on its building, reads the flood zone, base flood elevation and distance to the coast there, and re-reads them whenever a person moves a pin, so the underwriter and the cat modeling analyst see total insured value by zone as submitted and as checked.
The zone definitions and rules on this page are FEMA's and the statute's, linked where they appear. The worked examples come from the solution's sample data: a fictional Gulf Coast logistics renewal of 42 locations and $989.5M of total insured value.
Why the flood zone column deserves its own check
90%+
of the US population covered by FEMA’s digital National Flood Hazard Layer
1 in 3
flood insurance claims come from low- and moderate-risk zones
7yrs
how old a lender’s prior determination may be before it must be redone
$500K
NFIP building limit for a non-residential building; the rest is the commercial market’s
What is a flood zone determination?
It is a finding, made from FEMA's flood maps, of whether a building lies in a special flood hazard area and which zone label applies. FEMA defines the special flood hazard area as "the area that will be inundated by the flood event having a 1-percent chance of being equaled or exceeded in any given year," labelled with the A and V zones. Outside it, shaded Zone X (B on older maps) covers "the areas between the limits of the base flood and the 0.2-percent-annual-chance (or 500-year) flood," and unshaded Zone X (C on older maps) the areas "higher than the elevation of the 0.2-percent-annual-chance flood" (FEMA, Flood Zones).
The map that governs is the effective one. FEMA's National Flood Hazard Layer is "a geospatial database that contains current effective flood hazard data," covering over 90% of the US population, and FEMA is explicit that "where an effective flood map exists and provides data, that data must be used to establish the minimum NFIP requirements" (FEMA, National Flood Hazard Layer). Preliminary maps show where a zone is heading, but they do not yet set the rules. A determination that does not say which map it used cannot be checked.
The zones a commercial schedule meets, and what each one obliges the underwriter to carry
| Zone | What FEMA means by it | Federal purchase rule on a federally backed loan | What the schedule should carry |
|---|---|---|---|
| A, AE, AH, AO | Special flood hazard area: the 1%-annual-chance flood; AE has a base flood elevation | Applies in participating communities | Zone, base flood elevation, floor elevation and foundation where known |
| V, VE | Coastal special flood hazard area with wave action | Applies | Zone, base flood elevation, distance to the coast |
| X shaded (B) | Between the 1% and 0.2%-annual-chance flood limits; may be behind a levee | Does not apply | Zone, distance to the nearest A or V boundary, levee dependence |
| X unshaded (C) | Above the 0.2%-annual-chance flood | Does not apply | Zone, and floor elevation if known |
| D | Flood risk not determined; no flood hazard analysis done | Does not apply | Treat as unknown, not as low |
The lender's determination and the underwriter's are different jobs
A lender's flood zone determination answers one legal question for one loan; an underwriter's answers a pricing and accumulation question for a whole account. The lender's version is the Standard Flood Hazard Determination Form, which the statute requires for a loan secured by improved real estate. It records whether the building is in a special flood hazard area, so the lender knows whether flood cover is mandatory and whether to notify the borrower.
The statute also sets the lender's reliance rules. A lender may hand the work to a determination company, but only to the extent that company "guarantees the accuracy of the information." And a lender extending, renewing or buying a loan may rely on an earlier determination, without liability for its errors, "if the previous determination was made not more than 7 years before the date of the transaction," unless a map revision has since put the building into a special flood hazard area (42 U.S.C. 4104b).
An underwriter has no such safe harbour, and needs more than a yes or no. A shaded-X warehouse a few metres from an AE boundary and an unshaded-X warehouse on a ridge are both "not in the special flood hazard area" on a lender's form. To a flood model and to the account's accumulation they are different risks.
Lender's flood determination: Is this building in a special flood hazard area?
Underwriter's flood zone determination on a schedule: What flood hazard does each insured building face, and how much value sits in each zone?
Lender's flood determination: One building securing one loan
Underwriter's flood zone determination on a schedule: Every building on a schedule, often dozens across several states
Lender's flood determination: The federal form: in or out, zone, map panel and date
Underwriter's flood zone determination on a schedule: Zone, base flood elevation, distance to the coast and to the nearest boundary, placement precision, per location
Lender's flood determination: A prior form up to 7 years old, unless the map changed
Underwriter's flood zone determination on a schedule: Re-read at every renewal and whenever a pin moves
Lender's flood determination: The determination company that guaranteed it
Underwriter's flood zone determination on a schedule: The carrier, in its price and its accumulation
Why every building on a schedule needs its own determination
Because flood hazard changes over metres, not counties, one answer per account is wrong for most of the account. A Gulf Coast logistics schedule can hold buildings in AE on a ship channel, in shaded X a mile inland and in unshaded X on higher ground, all in the same county and all with the same broker's "flood: no" in the column.
The model that prices the flood shares the problem. Florida's standards for the flood loss models used in that state put it plainly: "Flood model outputs, including flood loss costs and flood probable maximum loss levels, are sensitive to insured exposure locations and topography" (Florida Commission on Hurricane Loss Projection Methodology, flood standards as of 1 November 2025, standard AF-3). A model fed a zone and coordinates from the wrong point returns a precise answer about a building that does not exist.
The federal program covers little of a commercial building's value either. For a non-residential building the NFIP maximum is $500,000 of building cover and $500,000 of contents (FEMA NFIP guide for non-residential buildings). A $20M distribution centre is insured for flood almost entirely in the commercial market, which is why the commercial underwriter, not the federal form, has to own the answer.
How do you determine the flood zone for each location on a schedule?
Place each building precisely, read the effective map at that point, measure the distance to the nearest A or V boundary, and keep the evidence with the row. The work is mechanical once the point is right, so most of the effort, and most of the errors, sit in the first step.
Flood zone determination across a schedule: five steps, two of them a person's
Agent
Place the buildingGeocodes each address to the roof where it can, and says how precisely each one is placed: rooftop, parcel, street or postal-code centre.
Never: Never treats a postal-code centre as a building
Agent
Read the zone at the pinReads the flood zone, base flood elevation and distance to the coast from published hazard layers at each placed point.
Never: Never infers a floor elevation from the zone
Agent
Measure the marginNotes how far each building sits from the nearest special flood hazard boundary, and flags those close to one.
A person decides
Fix the doubtful pinsThe underwriter looks at every location not placed on a roof and moves the pin to the building when the agents have found it.
A person decides
Sign the exposure fileThe cat modeling analyst receives total insured value by zone, as submitted and as checked, with unknowns sent as unknown.
Placement precision belongs in the determination itself. "Zone X, rooftop" and "Zone X, postal-code centre" are different findings, and a schedule that prints only the zone hides which is which. Five measures of geocoding accuracy on a schedule sets out how far points like these typically miss.
Where flood zone determinations go wrong on a commercial schedule
Four failures account for most bad flood answers on a schedule, and none of them is a misread map. Each is visible in the data if someone looks.
The point is not the building. An address missing from the address file falls back to a street or postal-code centre, and a large industrial parcel's centre may sit in a different zone from the warehouse on its edge. The map is old. A zone copied from last year's schedule may come from a map since revised, or carry a B or C label from a map that predates Zone X. The building is counted twice. A duplicated row doubles the value in its zone. The protection is assumed. FloodSmart notes that shaded areas "may have reduced their risk with mitigation efforts such as levees," and a levee's protection lasts only as long as the levee (FloodSmart, What is my flood zone?).
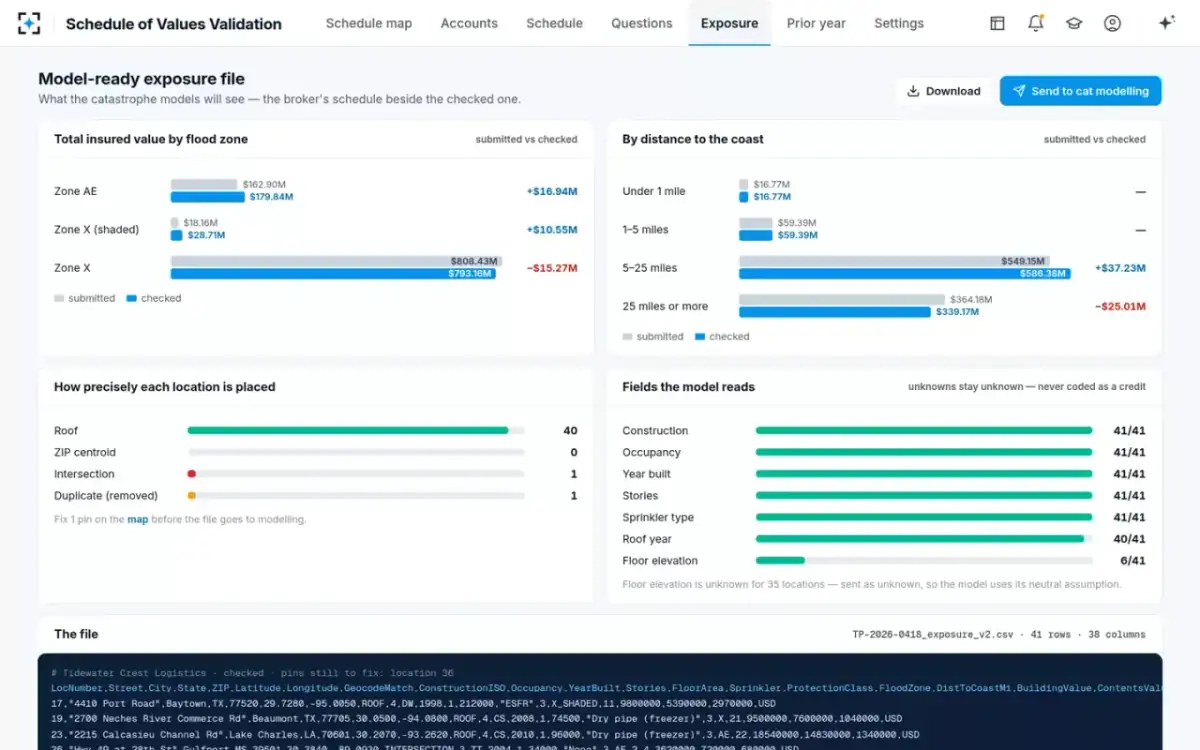
One sample schedule's value by flood zone, before and after each location was checked
Both directions matter. Had the cat modeling analyst received the broker's file, the model would have carried $17.77M of AE value twice and missed $34.71M of it where the water would actually reach. The account's flood accumulation would have been wrong in a way no total could reveal, because the two errors partly cancel.
One location, two zones: the cold store on the ship channel
A single relocated pin can move tens of millions of dollars across a zone boundary. In the sample renewal, location 23, a cold store at 2215 Calcasieu Channel Road in Lake Charles, Louisiana, was not in the address file, so it matched only the 70601 postal-code centre: Zone X, 27 miles from the coast. The agents searched the parcels along the channel road and found a 96,000 square foot cold store 5.6 km west, on the ship channel. They drew a dotted line to it and left the pin where it was, because moving a building is a person's decision.
Pin 23 moved to the roof: Zone X becomes Zone AE, base flood elevation 8 feet
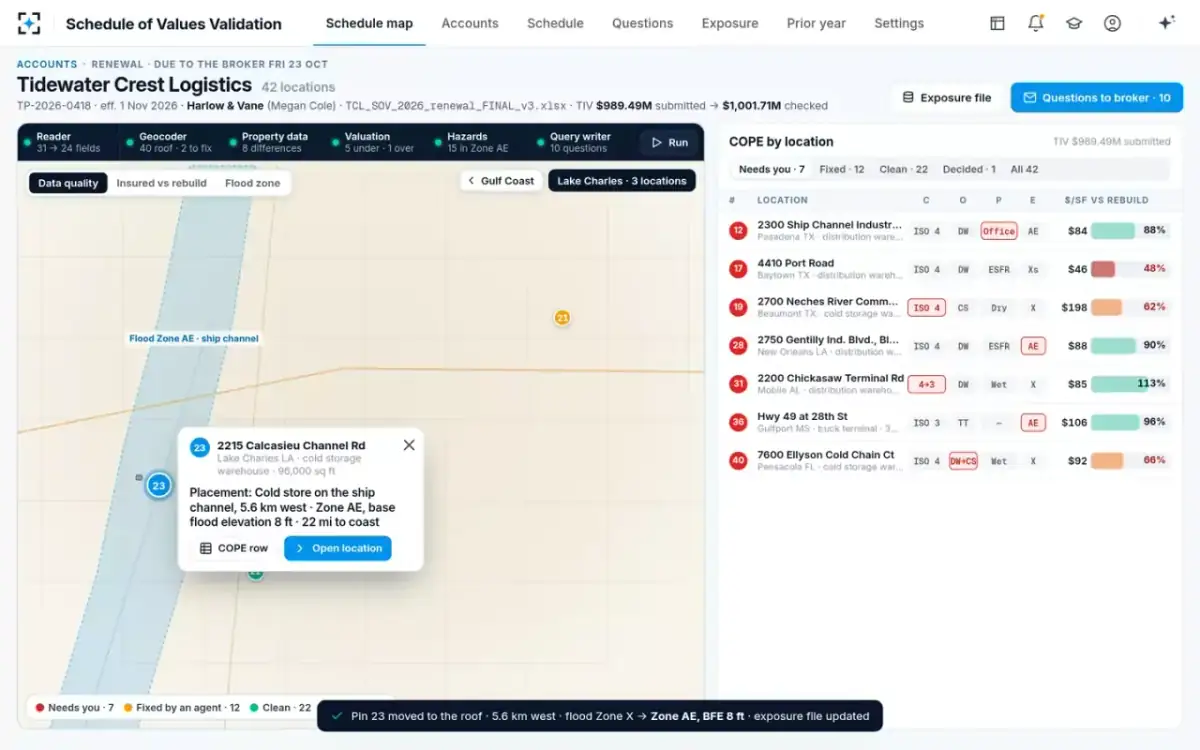
The underwriter moved the pin. The new determination was Zone AE with a base flood elevation of 8 feet, 22 miles from the coast, and $34.71M of value moved into the special flood hazard area. Nothing on the broker's spreadsheet hinted at it: the address looked complete and the zone looked reassuring. That is the case a flood zone determination process exists to catch, and the case a process that trusts the submitted column cannot.
Since Risk Rating 2.0, the zone screens the risk but does not price it
The federal program itself no longer prices flood from the zone. The Congressional Research Service summarised FEMA's change: "flood zones will no longer be used in calculating a property's flood insurance premium following the introduction of Risk Rating 2.0," and the premium rests instead on features such as "the foundation type of the structure, the height of the lowest floor of the structure relative to base flood elevation, and the replacement cost value of the structure" (Congressional Research Service, R45999).
The zone keeps two jobs. The same report notes that zones "will still be used for floodplain management purposes, and the boundary of the Special Flood Hazard Area will still be required for the mandatory purchase requirement." For a commercial underwriter the lesson is the same as the federal program's: the zone is a screen and a legal line, and the loss depends on the building's elevation, foundation and value. A determination that stops at the letter leaves the most useful questions unasked.
That is why the schedule should carry floor elevation and foundation where they are known, and say "unknown" where they are not. In the sample renewal, floor elevation was known for 6 of 41 locations; the other 35 went to the model as unknown, so the model used its neutral assumption rather than a favourable value nobody had measured. The COPE questions an underwriter asks of every building put flood inside the wider exposure picture.
What should a flood zone determination leave behind as evidence?
Enough for someone else to repeat it: the point, the map, the result and who changed what. A reviewer, a reinsurer's modeler or an auditor should be able to take any row and reach the same zone without asking the underwriter.
What each location's flood zone determination should carry
- The coordinates used, and how precise they are
Rooftop, parcel, street or postal-code centre. A zone is only as good as its point.
- The zone, and the base flood elevation where the map gives one
Shaded and unshaded X kept apart; D sent as unknown, never as low.
- The map source and its date
Effective data governs; a preliminary map is noted, not used as the determination.
- Distance to the nearest A or V boundary and to the coast
A building metres from the line is a different risk from one a mile away.
- Floor elevation and foundation, or "unknown"
Never inferred from the zone; unknown goes to the model as unknown.
- Every manual change, with before and after
A moved pin, a corrected address or a removed duplicate, with who made it and why.
When should the zone be determined again?
At every renewal, and whenever the building's point or the map changes. Maps are restudied and revised, and owners can obtain a Letter of Map Amendment or a Letter of Map Revision through FEMA, so last year's zone may no longer be the effective one. FloodSmart puts the cause simply: "Flood hazards change over time."
A pin that moves is the other trigger. In the sample renewal the moment the cold store's pin moved, the zone, the base flood elevation, the coast distance and the exposure file changed with it; no one had to remember to re-run anything. Comparing this year's schedule against last year's, matched by parcel rather than by row number, also shows which locations changed zone between renewals and why. The columns a schedule of values template should ask brokers for covers the fields that make that comparison possible.
Total insured value by flood zone and distance to the coast, submitted beside checked
What the solution decides about a flood zone, and what stays with FEMA and the underwriter
The solution makes the determination for every location and keeps the evidence; it does not replace the map or the people who sign. Its hazard mapper reads published hazard layers only, so a zone is never more current than the layer it reads. It does not issue the lender's federal form, and its finding is not a Letter of Map Amendment: a building whose owner believes the map is wrong still goes to FEMA.
What it changes is where an underwriter's time goes. Instead of reading forty zones off a spreadsheet and hoping the addresses were right, the underwriter looks at the handful of locations that are not placed on a roof, decides where each one really is, and lets the zone follow. The cat modeling analyst receives a file that says how much it can be trusted. The week before the model runs follows that file from the analyst's side.
Questions people ask
Who is responsible for the flood zone determination on a commercial loan?
The lender, which must complete the Standard Flood Hazard Determination Form for a loan secured by improved real estate. It may use a determination company, but under 42 U.S.C. 4104b only to the extent that company guarantees the accuracy of the information. A property insurer's underwriting is separate and carries no such reliance protection.
How long is a flood zone determination valid?
For a lender increasing, extending, renewing or buying a loan, a prior determination may be relied on if it was made no more than seven years earlier and set out on the standard form, unless a map revision has since placed the building in a special flood hazard area. An underwriter should re-read the zone at every renewal regardless.
What is the difference between Zone X shaded and Zone X unshaded?
Shaded Zone X lies between the 1% and 0.2%-annual-chance flood limits and may be protected by a levee; unshaded Zone X lies above the 0.2% flood. Neither is a special flood hazard area, and FloodSmart reports that one in three flood insurance claims comes from low- and moderate-risk zones.
Does a commercial building outside the special flood hazard area need flood cover?
The federal purchase requirement does not apply outside it, though a lender or a lease can require cover by contract. For underwriting, the zone is a screen: under Risk Rating 2.0 even the NFIP prices from foundation, floor height relative to the base flood elevation and replacement cost, not from the zone.
What does Zone D mean on a property schedule?
Zone D marks areas where no flood hazard analysis has been done, so the risk is undetermined. FloodSmart notes that rates there are proportionate to the uncertainty. On a schedule, a D location should go to the model as unknown, never as low risk.
Can the flood zone on a schedule be wrong if the map is right?
Yes, and it is the most common way. If the location is placed on a postal-code centre or the centre of a large parcel, the zone read there may belong to another place. In the sample renewal one cold store moved from Zone X to Zone AE, with $34.71M of value, once its pin was moved 5.6 km onto the building.