Homeowners claim frequency in the United States was 71.2 claims closed with payment per 1,000 policies in force in 2024, on state regulators' data compiled by the NAIC: 90.1 in the Southeast, 76.2 in the Midwest, 63.4 in the West and 45.7 in the Northeast. At that rate a block of 18,460 renewals carries roughly 1,300 policies with a paid claim in a year, and every one of them raises the same underwriting question: may the claim count at renewal, and for how much? States answer differently. Florida bars an act-of-God claim, and a single water claim, as the cause of nonrenewal unless the insured ignored the insurer's requests to prevent a repeat; Texas excludes natural-cause claims altogether and allows a refusal to renew only after three claims in three years, and only after a written warning at two. Botminds' Homeowners Renewal Underwriting re-scores every renewal and shows the claim as its own factor, with its source and date, so the underwriter can see whether it moved the decision and whether it may.
This guide is for the homeowners underwriting leader and the product manager who own renewal guidelines and the rating plan. It describes published rules; it is not legal advice for any state. The sample renewals are from a fictional insurer, Larkmoor Mutual, as they appear in the solution.
Paid homeowners claims per 1,000 policies in force, 2024, by NAIC zone
What is the average homeowners claim frequency?
About 7 paid claims per 100 policies a year, nationally, with wide regional spread. The NAIC's Center for Insurance Policy and Research counted 7,354,437 homeowners claims closed with payment in 2024 against 103,289,334 policies in force, 71.2 per 1,000 (NAIC CIPR, July 2026). The Southeast's rate was nearly double the Northeast's. The same report found that within zones the pattern differs by type of writer: in the West, larger national carriers had higher paid-claim rates, while in other zones regional and single-state writers had some of the higher ones.
The trend matters as much as the level. "Since 2018, these claim frequency rates—measured as claims closed with payment per 1,000 policies in force—have fluctuated significantly from year to year. However, in 2023, there was a notable increase in claims for all zones, followed by a leveling off or reduction in growth rates in 2024 for all zones except the Southeast Zone." The report's summary puts it plainly: insurers "have been faced with paying claims in both an increasing claim frequency and claim severity environment", and insurer-initiated nonrenewals rose over the same period, to 2,019,799 in 2024. How those nonrenewals break down by region is set out in homeowner policy non renewal rates.
Why claim frequency matters at renewal
Because every paid claim is a renewal decision the state may limit. Multiply 71.2 per 1,000 by a January block of 18,460 renewals and the block carries about 1,300 policies with a paid claim in the year, before counting claims from earlier years still inside a carrier's look-back window. Each of those households is a possible surcharge, re-rate or nonrenewal, and each such decision has to fit the rules of the state the home is in and the kind of claim it was.
A claim can reach a renewal in three different ways, and each is governed differently. The distinction is the one an underwriting guideline should write down first.
One claim can change a renewal in three different ways
As a count
The claim adds to the claims history the insurer reads from its own files and from claims databases. Some states limit how many claims, and which kinds, may count.
As a condition
The claim reveals damage. If it is not repaired by renewal, the unrepaired roof or water damage, not the claim, becomes the reason, and some states protect the repair period.
As a price
The claim moves a rating factor and the premium rises at renewal with no change to coverage. Texas allows a claims surcharge only after two claims in three policy years.
Can an insurer non-renew a homeowners policy after one claim?
In Florida and Texas, rarely for the claim alone. Florida protects categories of claims: "Claims on property insurance policies that are the result of an act of God may not be used as a cause for cancellation or nonrenewal, unless the insurer can demonstrate, by claims frequency or otherwise, that the insured has failed to take action reasonably necessary as requested by the insurer to prevent recurrence of damage to the insured property" (Fla. Stat. §627.4133(3)). A single water-damage claim "may not be used as the sole cause for cancellation or nonrenewal" on the same condition (§627.4133(6)).
Texas sets a count and excludes kinds of claim from it. A claim does not count if it results "from a loss caused by natural causes", if it "is filed but is not paid or payable under the policy", or if it is an appliance claim the insurer is barred from using. An insurer "may refuse to renew an insurance policy if the insured has filed three or more claims under the policy in any three-year period", but only if it warned the insured after the second; "If the insurer does not notify the insured in accordance with this subsection, the insurer may not refuse to renew the policy because of claims" (Tex. Ins. Code §551.107).
What one claim can and cannot do to a homeowners renewal in Florida and Texas
| Situation | Florida | Texas |
|---|---|---|
| A storm, hail or other natural-cause claim | Cannot be the cause of nonrenewal unless the insured failed to take action the insurer reasonably requested to prevent a repeat (§627.4133(3)). | Does not count as a claim for the renewal rule (§551.107(b)(1)). |
| A single water-damage claim | Cannot be the sole cause, on the same condition (§627.4133(6)). | Counts, unless natural-cause or excluded; one claim alone does not reach the threshold. |
| Damage not yet repaired | No cancellation or nonrenewal until repaired or one year after the final claim payment, whichever is earlier; after a declared hurricane or wind loss, not until 90 days after repair (§627.4133(2)(e)). | No specific repair period in ch. 551; the condition may still be a lawful reason. |
| How many claims allow a refusal | No fixed number in statute. | Three or more in any three-year period, after a written warning at two (§551.107(d)–(e)). |
| A surcharge instead | Through the filed rating plan. | Allowed at renewal after two or more claims in the preceding three policy years, on sound actuarial principles (§551.107(c)). |
| A phone call that is not a claim | Not addressed in these sections. | A customer inquiry cannot be a basis for nonrenewal or cancellation (§551.113). |
The Texas warning letter: a precondition, not a courtesy
In Texas the warning after a second claim is what preserves the right to non-renew for claims at all. The notice must "list the policyholder's claims" and contain a prescribed sentence beginning: "The filing by you of another claim, except for a claim resulting from a loss caused by natural causes, a claim filed but not paid or payable under the policy under which it was filed, or an appliance-related claim that we are prohibited from using…" (§551.107(e)). A carrier that skips the letter, or sends it with the wrong claims listed, cannot rely on the third claim later.
The surcharge rule has its own boundary. A Texas "premium surcharge" is "an additional amount that is added to the base rate", and the statute excludes from that term the reduction of a discount, a move to another rating tier, re-rating and re-underwriting through affiliates (§551.107(f)). That definition decides which renewal actions the two-claim surcharge rule governs, and it is a question for the product manager and the filed rating plan, not for an individual underwriter on a deadline.
The repair window: when the condition, not the claim, is the reason
An unrepaired condition can be a lawful reason where the claim itself cannot, and Florida protects the repair period. An insurer may not cancel or non-renew a residential policy "Until the earlier of when the dwelling or residential property has been repaired or 1 year after the insurer issues the final claim payment" after damage from a covered peril, and after a declared hurricane or wind loss not until 90 days after the home has been repaired (§627.4133(2)(e)). A Florida renewal that falls inside that window has to wait, whatever the score says.
Where a condition is the reason, the letter has to name it precisely. Delaware's bulletin on aerial imagery says "Nonspecific reasons, such as “claims experience,” “underwriting judgment,” or “increase in hazard,” are unacceptable as they do not provide sufficient notice for the insured to address the underlying issue" (Delaware Bulletin No. 150). A letter that says where on the roof, seen when and by what means, gives the insured the chance to repair and send proof, which is also the record a carrier needs if the decision is challenged. The tests regulators apply to a contested nonrenewal are scored on one file in homeowners non renewal notice requirements.
Claims databases and the adverse action notice
Claims history read from a consumer reporting company brings federal duties with it. The CFPB lists LexisNexis's C.L.U.E. as holding "seven years of home insurance and personal property claims, to help inform pricing and underwriting decisions" (CFPB, consumer reporting companies list). When an insurer takes adverse action "based in whole or in part on any information contained in a consumer report", the Fair Credit Reporting Act requires notice to the consumer, the reporting company's name, address and telephone number, a statement that the reporting company did not make the decision, and the consumer's right to a free copy and to dispute (15 U.S.C. §1681m(a)).
Two operational consequences follow. A renewal decision that draws on a claims report needs the adverse action notice as well as the state's nonrenewal or surcharge notice, and the two have different content. And a claim on the report that does not match the carrier's own files, a different address or a claim the insured never filed, should be resolved before it moves a score, because the insured can dispute it and the decision will be reviewed against the corrected report.
How a claim travels to the renewal decision
A person decides
Claim is adjustedThe insurer pays it, or does not. In Texas a claim filed but not paid does not count toward the renewal rule.
Agent
Claims history is readFrom the insurer’s own files and claims databases, five years back in the sample setup.
Agent
Renewal re-score, 90 days outThe claim becomes one input beside roof age, roof condition and hazard scores.
Never: counts a natural-cause claim toward a Texas claims limit
Agent
Change explainerSplits any score change into factors, so the claim’s share is visible on its own line.
Never: shows a factor without its source and date
A person decides
Underwriter decidesRenew, re-rate or inspect; a nonrenewal goes to the underwriting manager.
A person decides
Underwriter signs the letterOne reason per factor, each with its source, in the state’s wording and timing.
How should a renewal underwriter weigh one claim?
By kind, by state and on its own line. A paid water claim from an unrepaired leak is a different signal from a hail claim the whole street filed after the same storm, and Florida and Texas write that distinction into law. A guideline that treats every claim as equal is blunt everywhere and may be unlawful in those two states. The NAIC's examination standards test that a carrier's "underwriting practices are not unfairly discriminatory" and that it "adheres to applicable statutes, rules and regulations and regulated entity guidelines in the selection of risks", and that "Rejections and declinations are not unfairly discriminatory" (NAIC Market Regulation Handbook, Chapter 20).
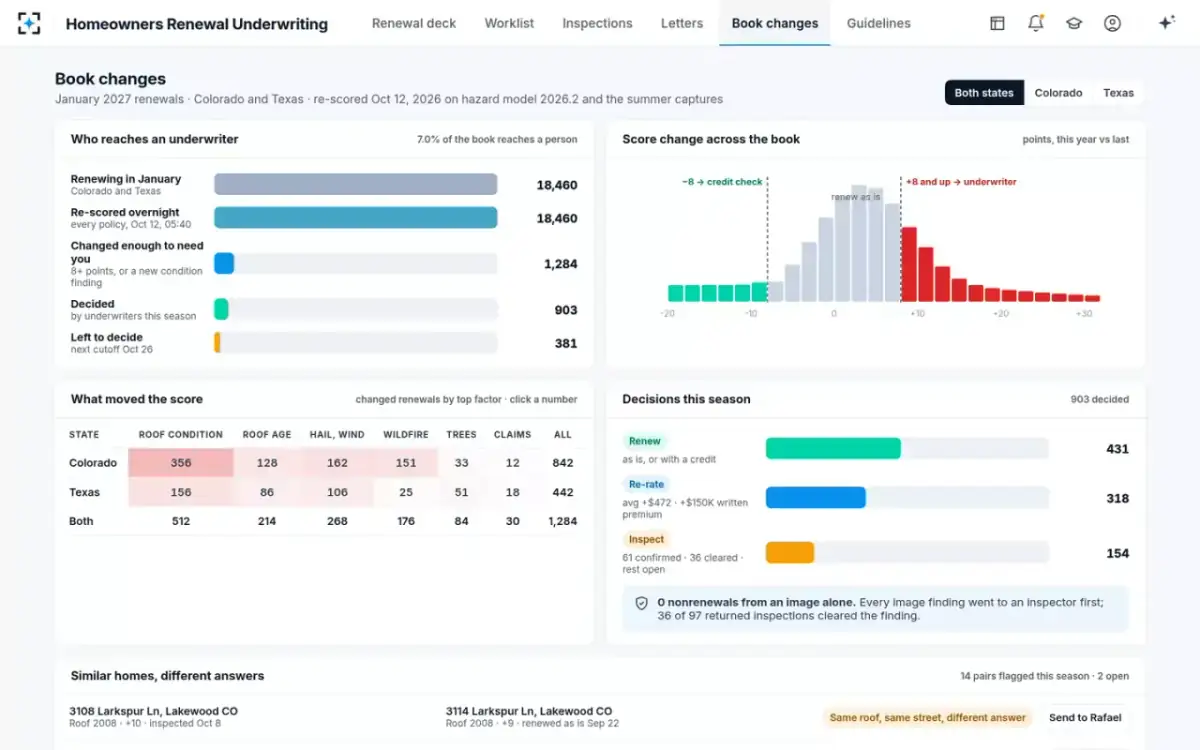
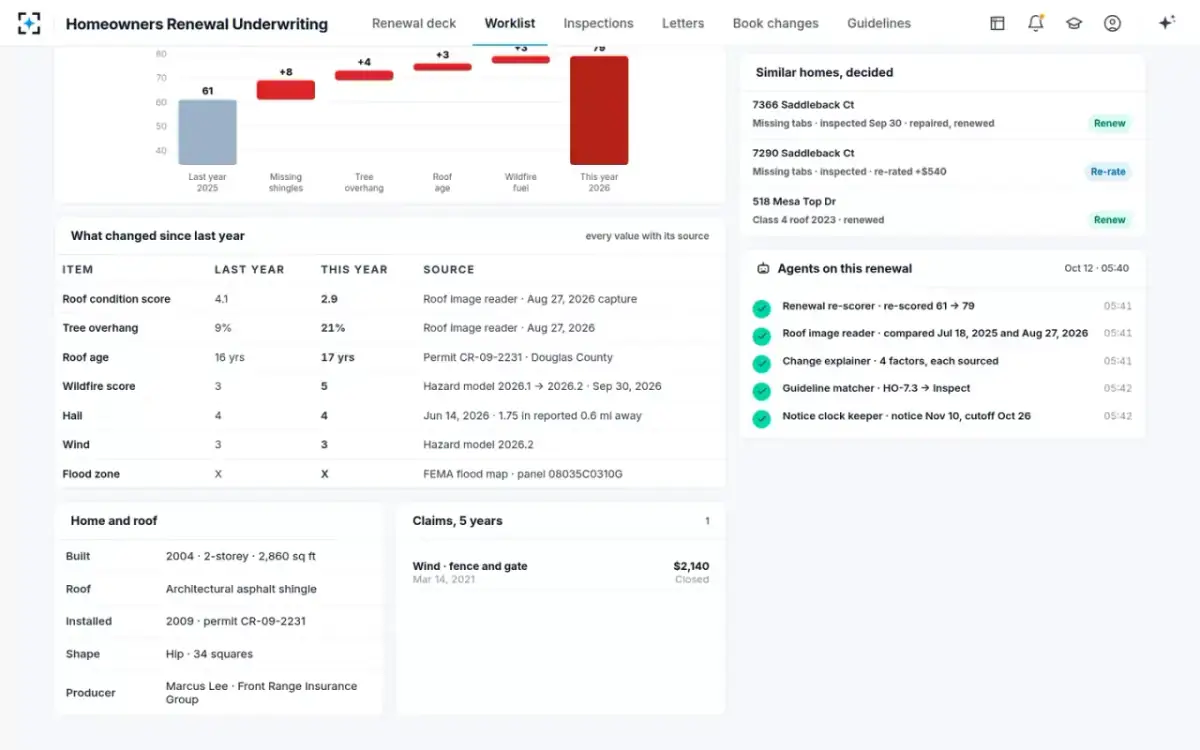
In practice, claims move fewer renewals than the question suggests. In the sample insurer's January book, claims were the top factor for 30 of the 1,284 renewals whose score moved enough to need an underwriter; roof condition led 512, hail and wind 268, roof age 214. The Brennan home in Castle Rock had one claim in five years, a $2,140 wind claim for a fence in March 2021, and it added nothing to an 18-point score change driven by the roof, the trees and a new hazard model.
Across a season, claims moved few renewals
Six rules for using claims at renewal
- Classify every claim by cause before it counts
Natural-cause, water, appliance, liability; Texas excludes natural causes and Florida protects act-of-God claims.
- Count only paid claims where the state says so
Texas excludes claims filed but not paid or payable.
- Send the Texas warning at two claims, with the claims listed
Without it, the right to non-renew for claims is lost.
- Check the Florida repair window before any adverse action
Repaired, or a year after final payment; 90 days after repair for a declared hurricane.
- Never treat a coverage question as a claim
In Texas a customer inquiry cannot be a basis for nonrenewal.
- Send the FCRA notice when a claims report contributed
Alongside the state notice, with the reporting company named.
Where Homeowners Renewal Underwriting fits on claims at renewal
The solution keeps each claim's weight visible and lawful on every renewal. The guideline matcher never counts a natural-cause claim toward a Texas claims limit, the change explainer shows claims as their own factor with points, source and date, and a renewal whose score moved because of claims reaches a named underwriter like any other change. Nonrenewals go to the underwriting manager, and each letter gives one reason per factor, so a homeowner whose renewal changed because of the roof is not told it was the claim, and the reverse.
It does not decide what the rating plan does with claims; the claims factor's points are set as filed by the product manager. It does not interpret a state's statute either: the rules it applies are settings the underwriting manager approves, versioned so the rule in force on any decision can be shown. And it reads the claims a carrier gives it; reconciling a claims report against the carrier's own files remains a step for the underwriting team.
One claim in five years, and how little it moved this renewal
Questions people ask
How is homeowners claim frequency calculated?
As claims divided by exposure. The NAIC's 2026 report uses claims closed with payment per 1,000 policies in force at year end: 7,354,437 paid claims over 103,289,334 policies gave 71.2 per 1,000 nationally in 2024.
Which region has the highest homeowners claim frequency?
The NAIC's Southeast zone, at 90.1 paid claims per 1,000 policies in 2024, followed by the Midwest at 76.2. The Northeast was lowest at 45.7.
How many claims before a Texas insurer can refuse to renew?
Three or more claims under the policy in any three-year period, not counting natural-cause claims, unpaid claims or excluded appliance claims, and only if the insurer warned the insured in writing after the second claim.
Can a Florida insurer non-renew after a hurricane claim?
Not because of the claim, unless the insured failed to take action the insurer reasonably requested to prevent a repeat. After a declared hurricane or wind loss, the insurer also may not non-renew until 90 days after the home is repaired.
Can an insurer surcharge after one claim in Texas?
Not as a "premium surcharge" under §551.107, which requires two or more claims in the preceding three policy years and actuarial support. The statute's definition of surcharge excludes losing a discount, a tier move and re-rating.
Does a claims database report trigger an FCRA notice?
Yes, when the adverse action is based in whole or in part on it. The notice must name the reporting company, say it did not make the decision, and tell the consumer of the right to a free copy and to dispute.