Florida Statute 627.7011(5) is the state's roof age law for homeowners insurers. An insurer may not refuse to issue or renew a homeowners policy solely because the roof is under 15 years old; for a roof of 15 or more it must let the homeowner have an authorized inspector examine the roof before requiring replacement, and if that inspection finds five or more years of useful life left, age alone cannot be the reason either. Age is counted from the last full replacement to code, with a rule for roofs replaced in parts, and the subsection applies to policies issued or renewed from 1 July 2022. Nothing in it limits decisions on the roof's condition or "other lawful reasons". The underwriting difficulty is applying three branches correctly to every renewal in a Florida book, each with a 120-day notice clock and an inspection the homeowner arranges. Botminds' Homeowners Renewal Underwriting reads roof age from the permit, keeps age apart from condition, and sends a changed roof to an underwriter with the rule that applies.
This guide is for the underwriting and compliance leaders of carriers writing Florida homeowners business. It reads the 2026 statute text as published; it is not legal advice. The product examples are sample data on a fictional insurer, Larkmoor Mutual, whose sample book is in Colorado and Texas.
“An insurer may not refuse to issue or refuse to renew a homeowner’s policy insuring a residential structure with a roof that is less than 15 years old solely because of the age of the roof.”
Florida Statutes §627.7011(5)(b), 2026 text
What does Florida Statute 627.7011 require of a homeowners insurer?
One obligation and two prohibitions, all about refusal on age. The obligation: for a roof of 15 years or more, the insurer must allow the homeowner to have the roof inspected by an authorized inspector, at the homeowner's expense, before requiring replacement as a condition of issuing or renewing. The prohibitions: no refusal to issue or renew solely because of age when the roof is under 15, and none for age alone when an inspection of an older roof shows "5 years or more of useful life remaining" (§627.7011(5)(b)–(c)).
The subsection is narrower than its reputation. It applies only to homeowners policies as the industry commonly understands them, not to mobile home policies, and it does not limit an insurer's ability to reject or non-renew because the structure fails its underwriting criteria for replacement cost or law and ordinance coverage, or for "other lawful reasons" (§627.7011(6)). It sets no premium, no rating factor and no maximum roof age. The text in force is the 2026 statute, last amended by chapter 2024-182, and a carrier's guidelines should cite it rather than a 2022 summary.
Florida's roof age law as a decision tree, with the statute at each branch
1 Is it a homeowners policy, issued or renewed on or after 1 July 2022?
No The subsection does not apply. Mobile home policies and policies that are not homeowners’ policies as commonly understood are excluded. §627.7011(5)(e), (6)
Yes Go on.
2 How old is the roof, counted the statute's way?
Count From the last date on which 100% of the roof’s surface was built or replaced to the code then in effect, or, where partial replacements together covered the whole roof, from the date of the first of them. §627.7011(5)(d)
3 Under 15 years?
Yes No refusal to issue or renew solely because of age. Condition and other lawful reasons remain. §627.7011(5)(b), (6)(c)
No, 15 or older Go on.
4 Has the homeowner been allowed an inspection by an authorized inspector?
Must be allowed Before requiring replacement as a condition of issuing or renewing, at the homeowner’s expense. §627.7011(5)(c)
5 Does the inspection show 5 or more years of useful life remaining?
Yes No refusal to issue or renew solely because of age. §627.7011(5)(c)
No Age may be a reason, with specific written reasons and 120 days’ notice of nonrenewal. §§627.4091, 627.4133(2)(b)
How Florida counts a roof's age, and the evidence it takes
Age runs from the last date on which 100% of the roof's surface was built or replaced to the code in effect at the time, or, for a series of partial replacements that together covered the whole roof, from "the initial date of a partial roof replacement" in that series (§627.7011(5)(d)). A patch on one slope leaves the roof's age where it was. A roof replaced slope by slope over several years takes the date of the first slope, once the last is done.
The building code makes partial work more common. For a roof built, repaired or replaced to the 2007 Florida Building Code or later, when 25% or more of it is repaired, replaced or recovered, "only the repaired, replaced, or recovered portion is required to be constructed in accordance with the Florida Building Code in effect" (Fla. Stat. §553.844(5)). A carrier's roof age therefore has to follow a history of permits, not a single date typed into an application years ago.
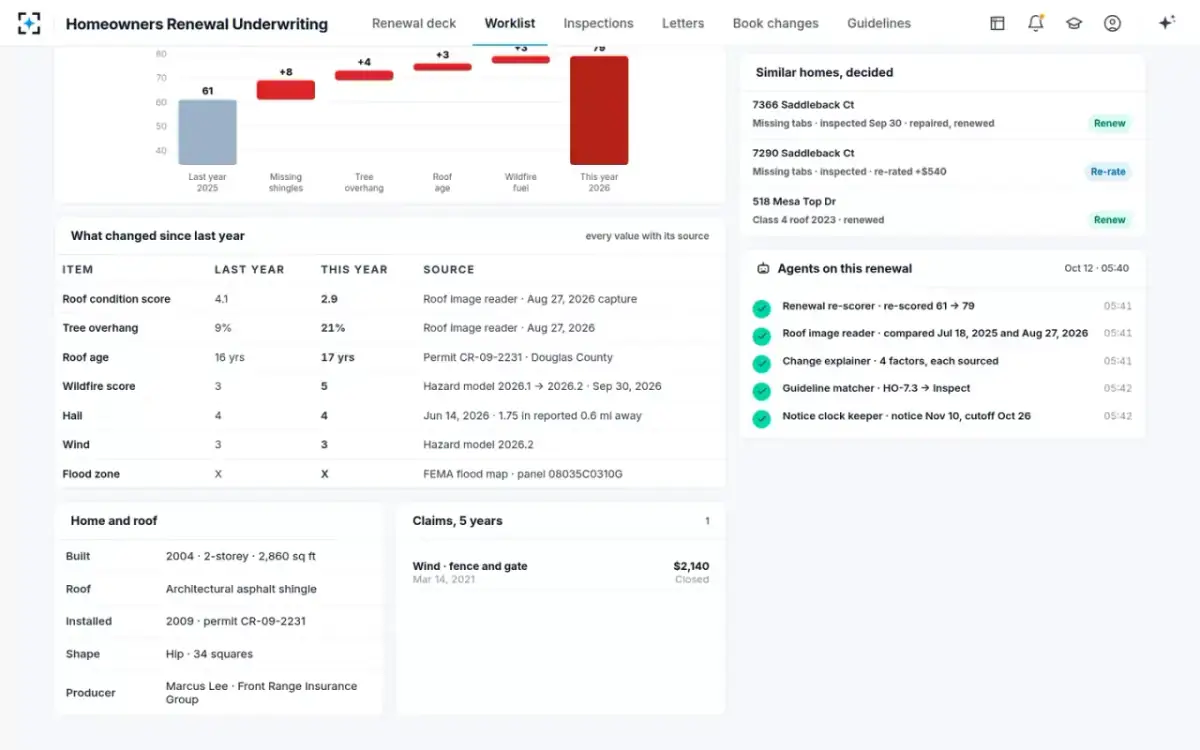
The age that holds up is the one a dated document supports: a county permit, a property appraiser's record or an inspection report, kept with the file and cited in any letter. In the sample insurer's renewal files, roof age arrives from the county permit with its number beside the figure, so a reviewer can see where 17 years came from.
Roof age from the permit, beside every other input that changed
The inspection branch: who qualifies, and who pays
For a roof of 15 or more, the inspection comes before any replacement demand, and the statute defines who may perform it. An "authorized inspector" is one "approved by the insurer" who is a licensed home inspector, a certified building code inspector, a licensed general, building, residential or roofing contractor, a licensed engineer or architect, or another person the insurer recognises as qualified (§627.7011(5)(a)). The homeowner pays. An inspection that finds five or more years of useful life takes age off the table for that decision.
Three operational points follow for a carrier. Its list of approved inspectors, or its criteria for approval, must be ready to give a homeowner when the branch opens. Its renewal letters for 15-year-plus roofs must offer the inspection before demanding replacement, not after. And its underwriters need a rule for reading the report: "useful life remaining" is the inspector's finding, and the carrier's guidelines should say how a report that finds five years is recorded and what a report that finds less leads to. When to order the carrier's own inspection at renewal is a separate question, set out in homeowners renewal inspection requirements.
What the law does not cover: price, condition and other lawful reasons
The roof age law limits refusals based solely on age. It does not reach condition, price or the other reasons a carrier may lawfully act on, and reading more into it produces guidelines that are both wrong and hard to defend.
Florida's roof age law: what it covers and what it leaves to other law
What §627.7011(5) says: No refusal to issue or renew solely because of the roof’s age.
What it does not say: Nothing about condition: a damaged 10-year-old roof can still be a lawful reason.
What §627.7011(5) says: The insurer must allow an inspection by an authorized inspector before requiring replacement.
What it does not say: It does not make the insurer pay for that inspection; the homeowner does.
What §627.7011(5) says: If the inspection finds 5+ years remaining, no refusal solely because of age.
What it does not say: No promise of the same premium or terms; pricing follows the filed rating plan.
What §627.7011(5) says: From the last 100% build or replacement to code, or the first date of a completed series of partials.
What it does not say: Nothing on which document proves the date; that falls to the evidence the insurer relies on.
What §627.7011(5) says: Homeowners policies issued or renewed on or after 1 July 2022.
What it does not say: Mobile home policies and policies that are not homeowners’ policies as commonly understood.
What §627.7011(5) says: —
What it does not say: Notice and reasons come from §§627.4133 and 627.4091: 120 days, specific reasons.
The consequence for a carrier's rating and underwriting files is separation. A roof can cost more because of its age under a filed rating plan while the carrier still may not refuse it for age alone, and a roof can be non-renewed for its condition whatever its age. Guidelines and letters that keep the two apart, with separate evidence for each, are the ones that survive a complaint.
How does 627.7011 change the renewal calendar?
It pushes the decision on an older roof much earlier than a 60-day state would need. Florida requires nonrenewal notice "at least 120 days before the effective date of the nonrenewal", with the reason in the notice (§627.4133(2)(b)). For a roof of 15 or more, the carrier must also leave the homeowner time to book and pay for an authorized inspection before it can demand replacement, and time to read the report. Our arithmetic: if a carrier allows 30 days for the homeowner's inspection and keeps a 15-day internal buffer before its notice date, it has to identify Florida roofs crossing 15 at least 165 days before renewal.
One Florida renewal with a 15-year-old roof: the inspection branch comes first
- Homeowner’s inspection window30 d
- Read the report, decide, sign15 d
- Florida notice period120 d
A book renewing evenly through the year has a slice of roofs crossing 15 every month, because every roof in it is a year older at each renewal. That makes the Florida roof age branch a standing workload, not a one-off project, and it competes for the same underwriters as storm and claims work. How a whole renewal block runs from pull to mailing is set out in the property insurance renewal process.
New business and the first 60 days
The same branches apply to new policies, because the statute speaks of refusing "to issue" as well as refusing "to renew". An insurer may not turn down an application solely because the roof is under 15, and for an older roof it must allow the applicant's inspection before requiring replacement as a condition of writing the policy. A denial must be "accompanied by the specific reasons for denial, including the specific underwriting reasons, if applicable" (§627.4091(1)).
Florida's cancellation statute treats a policy's first 60 days differently, with a shorter notice for certain cancellations in that period (§627.4133(2)(b)). A roof inspection that a carrier requires at binding has to be ordered, returned and read inside that window if it is to be acted on under the shorter rule; after it, the carrier is on the 120-day track like any renewal.
Applying the rule on a renewal book without skipping a branch
A guideline that applies Florida's statute correctly does four things on every policy: reads the roof's age from evidence, not the application; applies the full-replacement and partial-replacement rules to that evidence; routes roofs of 15 or more to the inspection branch before any replacement demand; and keeps age apart from condition so that a refusal never rests on age where the law forbids it. Each step should leave a record a reviewer can follow.
A Florida roof age renewal check, in the order the statute asks the questions
- Confirm the policy is a homeowners policy issued or renewed after 1 July 2022
Mobile home policies are outside subsection (5).
- Take roof age from a permit or other dated evidence
Keep the document with the file; Florida requires specific reasons, including underwriting reasons.
- Apply the 100% rule and the partial-replacement rule
A patch does not reset the age; a completed series of partials takes the first date.
- Under 15: never let age alone drive an adverse action
Condition findings can still apply, each with its own evidence.
- 15 or older: offer the inspection before any replacement demand
At the homeowner’s expense, by an authorized inspector as the statute defines one.
- Record an authorized inspector’s finding of 5+ years of life
Age alone is then off the table for that decision.
- Separate age from condition in the letter
Specific reasons under §627.4091; one reason per finding.
- Count back 120 days from renewal, and earlier for your own cutoff
Leave time for the homeowner’s inspection before the notice must be mailed.
Where Homeowners Renewal Underwriting fits on a Florida book
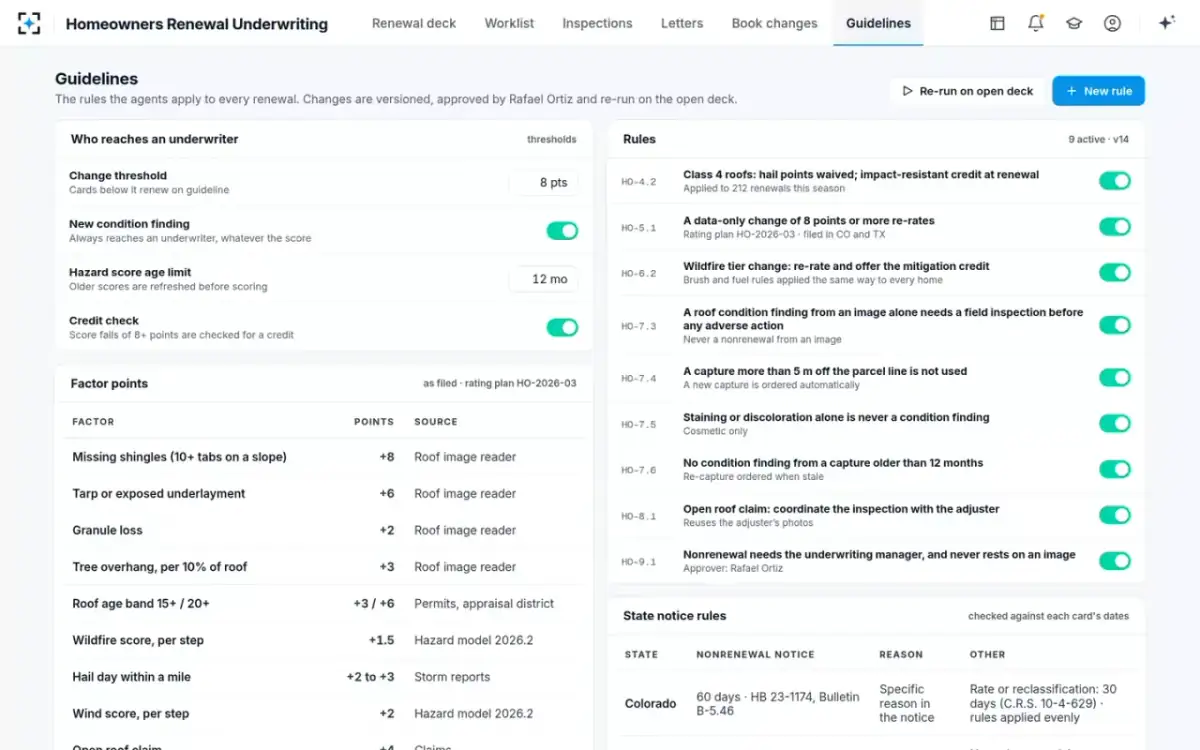
In the solution those checks become guidelines the underwriting manager owns. Roof age arrives from the permit with its number; roof-age points are kept apart from roof-condition points, so a letter can say which is which; an image-only condition finding goes to a field inspection before any adverse action; and the notice clock is set per state, so a Florida renewal's cutoff falls well before its 120-day date. The sample book in the solution is Colorado and Texas; a Florida book would carry the statute's branches as rules of its own, approved by the manager before they apply.
It does not decide what the statute means. The branches above are our reading of the 2026 text, and a carrier's counsel should approve the rules its guidelines encode. Nor does it choose the carrier's rating for older roofs, which is the product manager's filed plan.
Roof-age points kept separate from roof-condition points
Questions people ask
What is Florida Statute 627.7011?
The Florida statute on homeowners policies' replacement-cost and related terms; its subsection (5) is the roof age law. Since 1 July 2022 it bars refusing to issue or renew solely because a roof is under 15, and requires an inspection branch for older roofs.
Can a Florida insurer non-renew a 15-year-old roof?
Not for age alone without the inspection step. The insurer must allow an authorized inspector's inspection at the homeowner's expense before requiring replacement; if it finds five or more years of useful life, age cannot be the sole reason. Condition and other lawful reasons remain, with 120 days' notice and specific reasons.
Who is an authorized inspector under 627.7011?
An inspector approved by the insurer who is a licensed home inspector, certified building code inspector, licensed general, building, residential or roofing contractor, licensed engineer or architect, or another person the insurer recognises as qualified.
Does a partial roof replacement reset the roof's age?
Only when the parts add up to the whole roof. Age runs from the last full replacement, or, for a series of partial replacements that together covered the whole surface, from the date of the first of them.
Does 627.7011 limit what an insurer charges for an older roof?
No. It limits refusals based solely on age; premiums follow the insurer's filed rating plan, and the statute expressly preserves rejections and nonrenewals for other lawful reasons.
Does the roof age law apply to mobile homes?
No. Subsection (6) excludes mobile home policies and policies that are not homeowners' policies as commonly understood in the insurance industry.