Accounts receivable dilution is the share of a receivable balance that never turns into cash, because a discount, a return, an allowance or a write-off reduces it first. It matters to an asset-based lender because the borrowing base is built on receivables that are supposed to collect at face value, and every dollar of dilution is a dollar the lender's advance rate was never meant to cover. Most dilution is exactly what the name promises — ordinary, seasonal, and worth no more than a glance at the trend. One pattern is not: a customer's old invoice gets credited and rebilled under a new date, and the receivable that was ninety days old reappears as two days old. Field Exam Automation, Botminds' software for asset-based lending field exams, is built to catch that pattern before fieldwork starts, not after.
The example below comes from a fictional sample exam the solution runs: Tamsin Industrial Supply, a Toledo distributor on a $35.0 million revolver, examined for its third quarter ended 30 September. Tamsin, its customers and its numbers are invented for this walkthrough. The regulatory figures are quoted from the OCC and FDIC, linked where they appear.
What dilution is, in one definition
The OCC's Comptroller's Handbook on asset-based lending defines dilution plainly: it is "the difference between the gross amount of invoices and the cash actually collected for such invoices," and it names the usual causes — "discounts, returns, allowances, and credit losses" (OCC, Comptroller's Handbook: Asset-Based Lending). A $10,000 invoice that collects $9,400 because the customer took a 6% early-payment discount contributed $600 of dilution. A $4,000 return credited in full contributed $4,000. None of this means anything has gone wrong; it means the receivable, as billed, was never going to collect at full face value, and the lender's advance rate has to assume some of that will keep happening.
The FDIC's own examination manual lists the same ordinary causes from the other side of the desk, listing sales dilution from merchandise returns, bad-debt allowances and uncollectible receivables among the items an examiner checks in an asset-based relationship's on-site audits (FDIC, RMS Manual of Examination Policies, Commercial and Industrial Lending). Two regulators, one description: dilution is a fact about how a business sells, not a symptom by itself.
What makes up the dilution rate — and the one line that isn't honest
Discounts taken
early-payment and volume discounts
Priced into terms before the sale; the most predictable cause.
Returns and allowances
RMA credits, pricing adjustments
Tracked by the returns log; normal in any distributor.
Credit losses and write-offs
accounts given up as uncollectible
Usually small and infrequent in a performing book.
Credit-and-rebill
credited, then rebilled under a new invoice date
Not a sale adjustment — a receivable re-dated to look current.
Not dilution at all; a rebill wearing a credit memo
Why 5% is the number examiners watch
The OCC's own benchmark is specific: "dilution varies by industry but is usually expected to be 5 percent or less of receivables" (OCC, Comptroller's Handbook: Asset-Based Lending). Above that line, the handbook does not say a loan is automatically troubled; it says the bank should look harder, because "a rise in dilution rates can signal a decline in product or service quality, which can lead to financial problems for the borrower". A distributor selling to retailers can run higher dilution from seasonal returns than one selling to manufacturers on long contracts; the 5% line is a starting point for a conversation, not a pass/fail test written into every loan agreement the way a cross-aging percentage is.
Field Exam Automation keeps the line as a setting rather than a constant. Tamsin's loan agreement sets the dilution trigger, on a rolling three months, at 5% — the default among three choices in the exam's settings, with 4% and 6% the alternatives a credit officer can choose instead. Crossing the trigger does not refuse the borrowing base; it routes the finding to the field exam manager with the months and the reasons behind the rise, the same conversation the OCC's guidance describes, just arriving before the exam closes rather than after.
The honest causes of dilution — and the one that isn't
Most of what an examiner sees in a dilution review belongs in the first three rows of the formula above, and Tamsin's third quarter has an example of exactly that kind. Nine invoices to Ardent Robotics, totalling $214,800, were authorized for return under Tamsin's standard policy but had not yet been credited as of the data download — goods in transit back to the warehouse, with the paperwork a step behind the goods. That is dilution in its most ordinary form: a return, moving through the process it was always going to move through, visible to anyone who reads the returns log alongside the credit memos rather than the credit memos alone.
The OCC's guidance says what a lender should do with numbers like Ardent's: "the bank should carefully analyze trends or significant changes in dilution rates, and a field auditor should review and test selected credit memos" (OCC, Comptroller's Handbook: Asset-Based Lending). A field exam that only totals the credit memos for the quarter would show a number; one that reads the returns log, the shipping dates and the credit-memo reasons behind the number shows whether it is ordinary or not. Ardent's returns passed that test. A second item in the same quarter's review did not.
One credit-and-rebill case, minute by minute: 14 invoices, $186,240
On Monday 28 September, fourteen invoices to Holloway Packaging, totalling $186,240 and first dated between 15 June and 1 July, were credited in full and rebilled the same afternoon under new invoice numbers and a current date. Read only as a credit memo, the entry looks like a routine $186,240 adjustment — a number inside the 5% trigger on its own, nothing to flag. Read as a pair with the new invoices it produced, it is something else: the same receivable, re-dated from being ninety-plus days old to being two days old, with no goods, no payment and no dispute changing hands in between.
The same $186,240, aged two different ways
- Credited in full28 Sep
- Rebilled, new invoice numbers28 Sep
- Age at the 30 Sep test date2 days old
- First invoiced15 Jun – 1 Jul
- Age at the 30 Sep test date91–107 days old
Nothing shipped again. No dispute was raised or resolved. Gail Prentiss, Tamsin's controller, later confirmed to Owen Castellano, the field examiner, that the invoices were reissued at Holloway's request, with payment terms still running from the original June dates — which is itself the detail that unravels the rebill: if the terms never restarted, neither did the age that matters to the borrowing base. The dilution and credit memo analyst's role in Field Exam Automation is to raise exactly this kind of pattern for a person to judge, never to decide on its own what it means; its own limits say so — it never calls a pattern fraud, only raises it for the examiner to confirm.
How re-aging from the first invoice date catches it
The fix is arithmetic, not judgment: age every receivable from the date of the sale that actually produced it, not from the date of the most recent paperwork touching it. A rebilled invoice carries a new invoice number and a new date, but the underlying sale — the shipment, the customer, the goods — happened once, and that is the date the aging should respect.
One invoice, read two ways
As the credit-and-rebill dates it: 28 September (the rebill)
As re-aged to the first invoice date: 15 June – 1 July (the original sale)
As the credit-and-rebill dates it: 2 days
As re-aged to the first invoice date: 91–107 days
As the credit-and-rebill dates it: A fresh, current receivable
As re-aged to the first invoice date: A receivable approaching or past a 90-day past-due line
As the credit-and-rebill dates it: A credit and a new invoice, same afternoon
As re-aged to the first invoice date: One shipment, four months earlier
Re-aging is only possible when the system doing it can connect a credit memo to the invoice it rebills — matching customer, items and amount across the pair — rather than treating every credit as a closed, unrelated event. That matching is the roll-forward and tie-out builder's job elsewhere in the exam program; for dilution specifically, it is what turns "a $186,240 credit memo" into "a $186,240 rebill of invoices that are really 91 to 107 days old," which is a very different fact for a borrowing base.
What a field auditor is told to review in every credit memo
The OCC's instruction is not limited to large or unusual credits — it calls for the field auditor to "review and test selected credit memos" as a matter of course (OCC, Comptroller's Handbook: Asset-Based Lending), and three questions do most of the work on each one: does the credit memo's reason match an actual return, allowance or write-off rather than a reissue; does a new invoice appear for the same customer within a few days of the credit, for close to the same amount; and if one does, do the payment terms on the new invoice match the terms on the original sale, or do they reset the clock. Holloway's case failed the second and third tests at once — a same-day rebill, with terms the controller herself said were still running from June.
"Dilution varies by industry but is usually expected to be 5 percent or less of receivables."
OCC, Comptroller's Handbook: Asset-Based Lending
A single rebill rarely moves a quarter's dilution rate past that 5% line on its own; Holloway's $186,240 is a fraction of Tamsin's receivables base. The reason it still belongs in the review is that a credit-and-rebill pattern, once it exists for one customer, is cheap to repeat for others, and a number that looks fine in aggregate can be hiding one relationship that is not fine at all.
What happens to availability when a rebill is reversed
Reversing the rebill changes two things at once, and they pull in the same direction. First, the $186,240 stops counting as a two-day-old receivable and starts counting at its true age, which on an aging-based eligibility test can push it toward or past the past-due line the loan agreement sets — eligibility and cross-aging treatment for that balance are worked through on their own, elsewhere. Second, the dilution rate itself changes, because a correctly treated rebill was never really a credit memo against current sales; removing it from the dilution calculation and reading it instead as an aging correction is why Tamsin's own exam shows two different numbers for the same quarter.
Two items on Tamsin's dilution review, by dollar
That is the quiet value of catching a rebill before fieldwork: it does not necessarily blow through the dilution trigger by itself, but it corrects the two numbers — dilution and aging — that a borrowing base depends on getting right at the same time, rather than leaving one of them wrong until an examiner happens to notice the same customer's invoices twice.
How to tell a rebill from a legitimate reissue
Not every credited-and-reinvoiced pair is a problem. A legitimate reissue happens when something about the sale itself changed — a pricing error corrected, a purchase order amended, a tax recalculated — and the new invoice reflects that change rather than simply restating the old one. Four questions separate the two in practice: did anything about the transaction actually change, or is the new invoice identical to the old one; do the payment terms reset, or does the customer (and the company issuing the credit) treat them as continuing from the original sale; is there a business reason on file — a pricing dispute, a correction, a contract amendment — or no stated reason at all; and does the pattern repeat for the same customer, which a single correction does not but a working method of refreshing aging does.
The dilution review: the Holloway pair, flagged
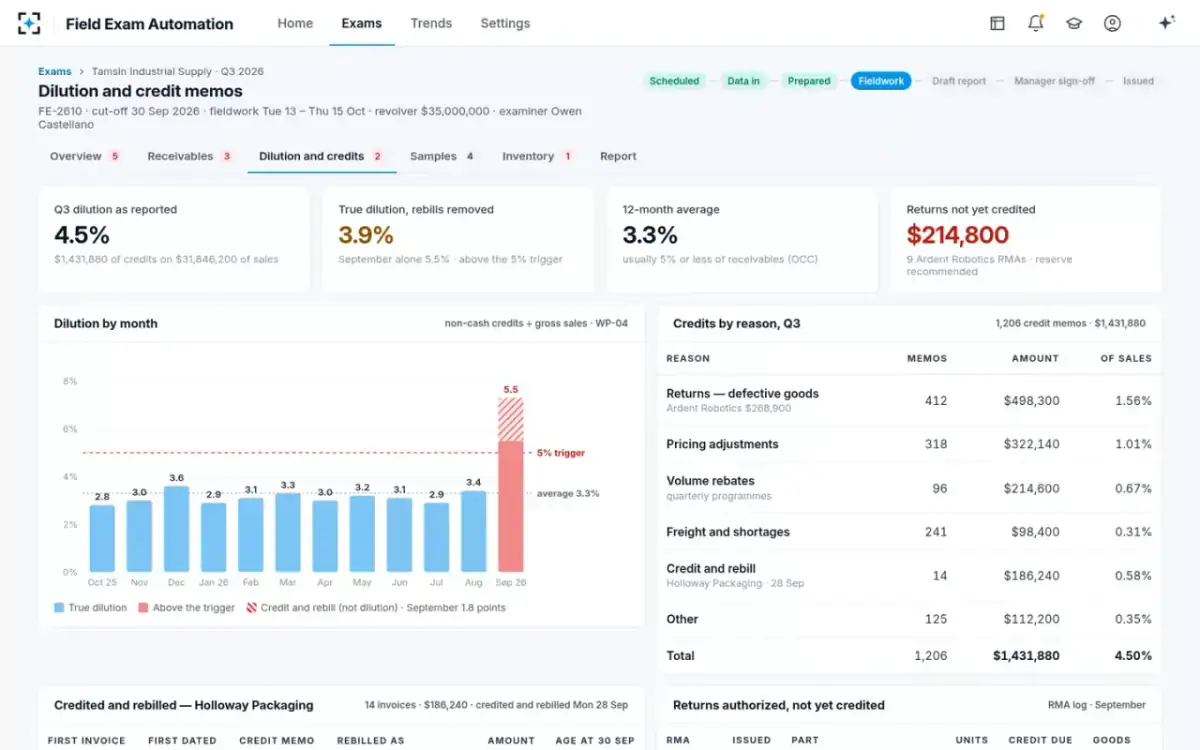
Owen Castellano confirmed the Holloway finding on site at Tamsin: Gail Prentiss told him directly that the invoices were reissued at Holloway's request, with terms still running from June — the detail that turns a plausible-looking reissue into a rebill. Confirmation on site is not a formality; the dilution and credit memo analyst raises the pattern, but only the examiner's conversation with the controller settles whether it was a correction or a redate. For how that confirmation step fits into the rest of the exam, and what the examiner can and cannot do with a flagged finding, see what a field examiner does, seat by seat. For what happens to the receivable's eligibility once it is re-aged, see cross-aging and ineligible receivables. To see the dilution review alongside the rest of the exam, start from Field Exam Automation.
Questions people ask
What is accounts receivable dilution?
It is the share of a receivable's gross invoice amount that never collects in cash, because of a discount, a return, an allowance or a write-off. The OCC defines it as "the difference between the gross amount of invoices and the cash actually collected for such invoices," naming discounts, returns, allowances and credit losses as the common causes.
How is dilution calculated?
As a rate: total discounts, returns, allowances and credit losses for a period, divided by average receivables or by gross sales for the same period. Lenders usually watch it on a rolling three-month basis so one unusual month does not drive the whole reading.
What is a normal dilution rate?
The OCC's guidance puts the usual range at 5% or less of receivables, while noting that the right number varies by industry. A distributor with seasonal returns can run higher than a business selling on long contracts; the figure is a starting point for review, not a universal pass line.
What is credit-and-rebill in accounts receivable?
It is crediting an existing invoice in full and immediately reissuing it under a new invoice number and date, without any real change to the underlying sale. The effect is to make an old receivable look current again, which can hide it from an aging-based eligibility test.
How do you catch a credit-and-rebill pattern?
By matching every credit memo to any new invoice issued for the same customer, items and amount shortly afterward, and re-aging the result from the date of the original sale rather than the date of the rebill. A payment-terms check — do the terms reset, or do they still run from the first invoice — usually settles whether it was a correction or a redate.
How often should dilution be reviewed?
The OCC calls for ongoing attention to trends, not a once-a-year look: "the bank should carefully analyze trends or significant changes in dilution rates, and a field auditor should review and test selected credit memos." In a quarterly field exam, that review happens every quarter, on the months since the last one.