FDIC insurance on a payable-on-death account covers the owner’s deposits up to $250,000 for each eligible beneficiary named, to a maximum of $1,250,000 for five or more beneficiaries, and that limit applies to all of the owner’s trust accounts at the same bank combined. That has been the rule since April 1, 2024. Two death rules sit on top of it. When the owner dies, the FDIC insures the deposits as if the owner were alive for six months. When a beneficiary dies, there is no grace period: the coverage that beneficiary supported falls away at once. Credit unions, insured by the NCUA, adopt the same trust-account structure on December 1, 2026. For the deposit operations teams that settle estates, the rules decide how long an estate can sit before coverage changes, and which events, such as a beneficiary’s death, should prompt a call to the owner. Botminds’ Deceased Account Processing reads every beneficiary designation an estate has; this guide explains the coverage behind them.
Trust-account coverage under the old structure and the new one
Credit unions until November 30, 2026: Revocable trusts (including payable-on-death, in-trust-for and living trusts) are insured separately from irrevocable trusts.
Banks since April 1, 2024; credit unions from December 1, 2026: One trust accounts category for revocable and irrevocable trusts, with “a common simple calculation”.
Credit unions until November 30, 2026: Number of different beneficiaries times $250,000; a separate formula for an owner with more than five beneficiaries and more than $1,250,000.
Banks since April 1, 2024; credit unions from December 1, 2026: $250,000 per eligible beneficiary, a maximum of $1,250,000 per owner however many beneficiaries are named.
Credit unions until November 30, 2026: The intention may be shown in the title or the account records, and the beneficiaries must be specifically named in the records.
Banks since April 1, 2024; credit unions from December 1, 2026: Beneficiaries must be named in the deposit account records; payable-on-death wording in the title “is no longer required.”
Credit unions until November 30, 2026: With more than five beneficiaries and more than $1,250,000, coverage is the greater of $1,250,000 or the sum of each beneficiary’s interest, each capped at $250,000.
Banks since April 1, 2024; credit unions from December 1, 2026: $1,250,000 per owner is the ceiling; the NCUA says the new rule “may reduce coverage” for members above it.
How does FDIC insurance work for payable-on-death accounts?
A payable-on-death account is, for deposit insurance, an informal revocable trust, and it is insured per owner, per eligible beneficiary. The FDIC’s formula is “# of Owners x # of Beneficiaries x $250,000 = Amount Insured,” capped at “$1,250,000 per owner for all trust accounts” (FDIC, Your Insured Deposits). A single owner with two named children is insured up to $500,000; two owners naming the same two children, up to $1,000,000.
The FDIC defines the category broadly: informal revocable trusts are “often called payable on death, Totten trust, in trust for, or as trustee for accounts,” and are created when the owner signs a deposit agreement “directing the bank to transfer the funds in the account to one or more named beneficiaries upon the owner’s death.” In the regulation itself, an informal revocable trust is one under which “a deposit passes directly to one or more beneficiaries upon the depositor’s death without a written trust agreement” (12 CFR 330.10).
Three conditions decide whether a beneficiary counts. The beneficiary must be named in the bank’s deposit account records. The beneficiary must be eligible: “a living person, a charity, or a non-profit organization.” And each beneficiary counts once per owner: “if a single owner names the same beneficiary on multiple trust accounts at the same bank, that beneficiary only counts once when determining coverage” (FDIC).
Maximum coverage per trust owner, by number of eligible beneficiaries
| Unique eligible beneficiaries | Maximum coverage per owner | With two owners |
|---|---|---|
| 1 | $250,000 | $500,000 |
| 2 | $500,000 | $1,000,000 |
| 3 | $750,000 | $1,500,000 |
| 4 | $1,000,000 | $2,000,000 |
| 5 or more | $1,250,000 | $2,500,000 |
What changed on April 1, 2024?
Two things: a ceiling, and a merger of categories. “As of April 1, 2024, the maximum insurance coverage for a trust owner with five or more beneficiaries is $1,250,000 per owner,” the FDIC states, and the change “applies to both existing and new trust accounts, including CDs (regardless of maturity date)” (FDIC). And revocable and irrevocable trusts now share one limit: it “applies to the combined interests of all beneficiaries the owner has named in revocable and irrevocable trust accounts at the same bank.”
The FDIC’s own worked example shows the effect. An owner with a living trust, a payable-on-death savings account and an irrevocable charitable trust at one bank, naming six eligible beneficiaries between them and holding $1,280,000, is insured for $1,250,000 and uninsured for $30,000, because “a trust account owner that identifies five or more eligible beneficiaries will not be insured beyond $1,250,000 per bank.” Naming a sixth beneficiary changes the estate plan, not the insurance.
The rule also loosened a formality. For payable-on-death accounts, “the account title may include POD/ITF or similar language, but it is no longer required,” as long as the beneficiaries are named in the bank’s records. For estate work that cuts both ways: an account titled in the owner’s name alone may still carry beneficiaries on a separate designation, so the title is not proof of sole ownership.
FDIC insurance on payable-on-death accounts, in four numbers
$250K
per eligible beneficiary, per owner
$1.25M
maximum per owner, all trust accounts at one bank
6 mo
coverage unchanged after the owner’s death
0
days of grace when a beneficiary dies
The FDIC 6 month rule after an account owner dies
When a depositor dies, the FDIC keeps insuring the deposits as if the depositor were alive for six months. The regulation reads: “The death of a deposit owner shall not affect the insurance coverage of the deposit for a period of six months following the owner’s death unless the deposit account is restructured. The operation of this grace period, however, shall not result in a reduction of coverage. If an account is not restructured within six months after the owner’s death, the insurance shall be provided on the basis of actual ownership” (12 CFR 330.3(j)).
The six months matter most where a death changes the ownership category. A joint account between spouses that becomes the survivor’s alone after the death would, on actual ownership, be added to the survivor’s other single accounts at the same bank. The grace period gives the family, and the bank, time to restructure before that happens, and the rule’s last clause means the grace period is never applied to reduce coverage. Credit union members have the same protection: “The death of a member will not affect the member’s share insurance coverage for a period of six months following death unless the member’s share accounts are restructured in that time period” (12 CFR 745.2(e)).
For a bereavement desk the practical point is a clock. An estate still open six months after the death has a coverage question as well as a service one, and that clock is set by the date of death, not the date the bank learned of it. How long a bank takes to release funds after a death sets this six months beside the other legal clocks on an estate.
Is there an FDIC grace period when a beneficiary dies?
No. The FDIC is direct: “There is no grace period if the beneficiary of a POD account dies. In most cases, insurance coverage for the deposits would be reduced immediately” (FDIC, Your Insured Deposits). The reason is the eligibility rule: a beneficiary must be a living person, a charity or a non-profit, so a beneficiary who has died no longer counts.
A $500,000 payable-on-death account, before and after one of two beneficiaries dies
The same applies to formal trusts: “the six-month grace period does not apply to the death of a beneficiary named in a formal revocable trust account,” although the trust’s own terms may name a successor beneficiary. For a payable-on-death account there is no such document; the designation on file is all there is, which is why what happens when a POD beneficiary dies first is a question about the bank’s records as much as about the law.
Credit unions: the NCUA trust rule changes on December 1, 2026
Credit union deposits are insured by the NCUA’s Share Insurance Fund, not the FDIC, and until November 30, 2026 its trust rules keep the older structure. The NCUA adopted the FDIC’s approach in September 2024 with a delayed start: “The changes to the Share Insurance Fund coverage of trust accounts are effective on December 1, 2026,” and they “align with changes the FDIC previously adopted, which took effect on April 1, 2024” (NCUA, September 19, 2024). The Federal Register notice gives the same date (89 FR 79397).
Most members will not notice. The NCUA’s consumer site says: “For most member trust depositors (those with less than $1,250,000), the NCUA expects the coverage levels to be unchanged. However, the new rule may reduce coverage for those members who have placed more than $1,250,000 per member owner in trust deposits at one federally insured credit union” (mycreditunion.gov). Its fact sheet frames the test as two questions: does the member hold both revocable and irrevocable trust accounts at the same credit union, or trust accounts totalling “more than $1,250,000 for a single owner or $2,500,000 for two owners” (NCUA fact sheet)?
One line in the NCUA’s notice on its consumer site is aimed squarely at deposit operations: “We suggest federally insured credit unions and their members review the new rules for time deposits such as share certificates with maturities beyond December 1, 2026.” A share certificate payable on death that renews after that date will be insured under the new calculation, and an estate that is still open on December 1 will be settled under it.
Why the bank’s own records decide the coverage
Deposit insurance is calculated from the bank’s files, not from what the family remembers or what a will says. The regulation sets the starting point: “the FDIC shall presume that deposited funds are actually owned in the manner indicated on the deposit account records of the insured depository institution” (12 CFR 330.5(a)(1)). For a payable-on-death account, that means the beneficiaries the bank has on file are the beneficiaries the FDIC counts.
Three gaps between the records and the owner’s intentions are worth looking for in any estate. A beneficiary form signed but never filed, or lost in a system conversion, leaves the account with fewer beneficiaries on record than the owner thought. A beneficiary who died years ago stays on the designation, counted by the owner and not by the rule. And a designation replaced at a branch but never indexed to the account leaves the old names in force on paper. Each one is a coverage question while the owner lives and a payout question after the owner dies, which is why reading every designation in imaging, rather than trusting the ownership code in the core system, matters for both.
The NCUA’s rule says the same for credit unions. Until December 1, 2026, the intention to leave funds to beneficiaries must be shown “in the title of the account or elsewhere in the account records of the credit union,” and for informal revocable trusts “the beneficiaries must be specifically named in the account records of the insured credit union” (12 CFR 745.4(b)).
Estate, power-of-attorney and joint accounts after a death
Three other categories turn up in every estate, and none of them is a trust account. An estate account opened by the executor is insured as a single account: the FDIC lists “An account established for or representing a deceased person’s funds–commonly known as a Decedent’s Estate Account” under single accounts (FDIC). An account in one person’s name that another person can draw on under a power of attorney is also a single account, because the FDIC looks at ownership, not signing authority. And a joint account belongs in the joint category until the six-month grace period ends or the account is restructured.
For a bank, the useful habit is to note each account’s insurance category on the estate file alongside its destination. The two usually move together: a joint account retitled to the survivor becomes the survivor’s single account, and a payable-on-death certificate paid out leaves the bank or lands in the beneficiaries’ own accounts. An estate that leaves large balances in place for months while beneficiaries are traced is the one where the categories, and the clocks, need watching.
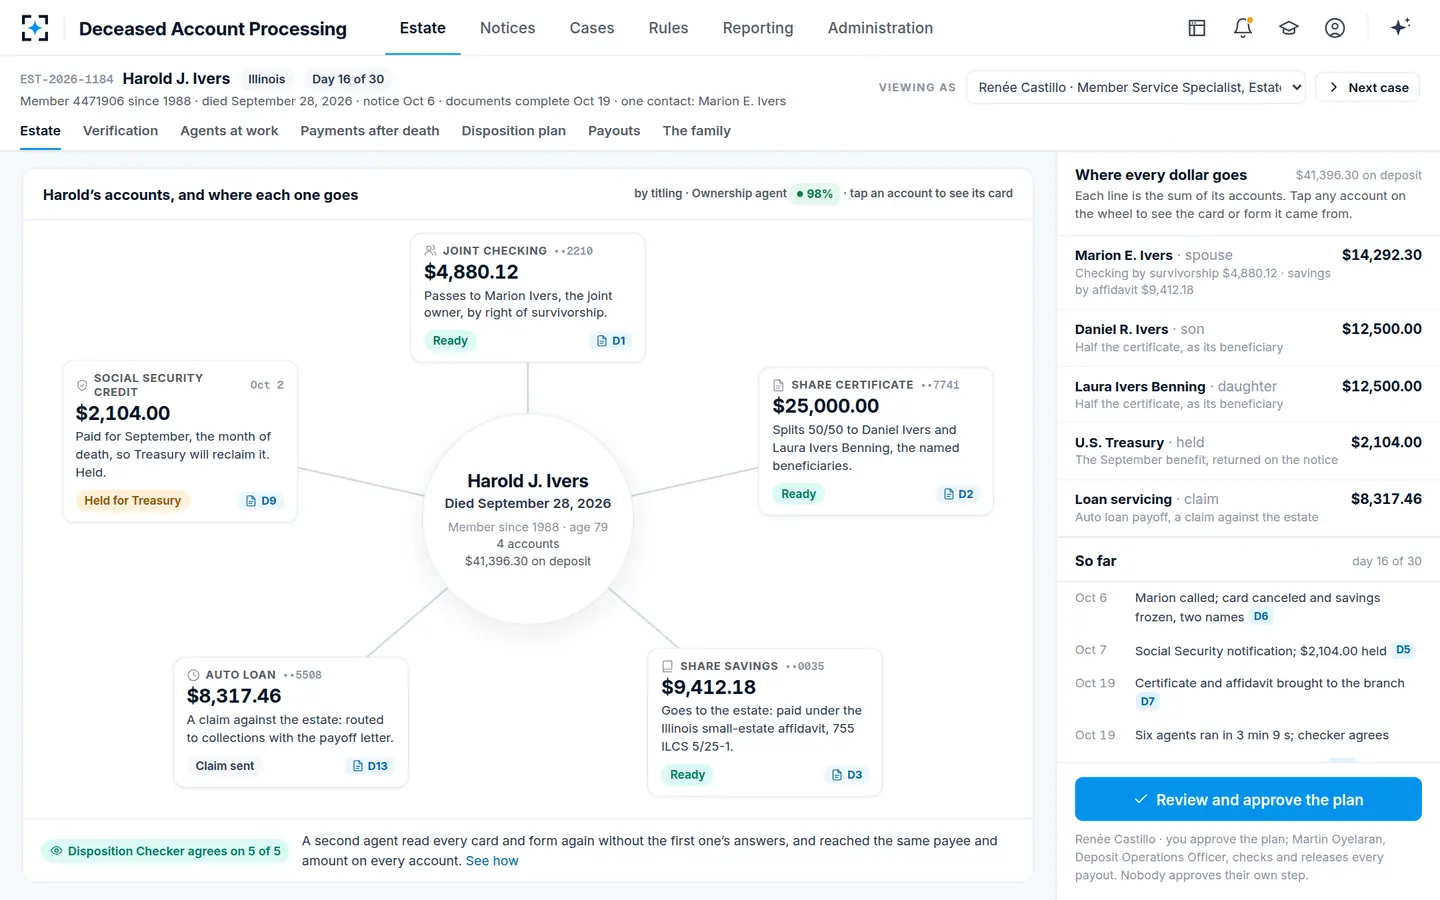
A payable-on-death certificate on the relationship wheel, split between its two named beneficiaries
What should deposit operations do with these rules?
Treat three events as triggers. The owner’s death starts a six-month clock on every account, so an estate file should carry the date of death and the date six months on. A beneficiary’s death reduces coverage at once and leaves the owner’s designation stale, so it should prompt a conversation with the owner about naming someone else; until then, the account’s coverage may be lower than the owner believes. And, for credit unions, December 1, 2026 changes the calculation for members with trust balances above $1,250,000 or with both revocable and irrevocable trusts, including share certificates that mature after that date.
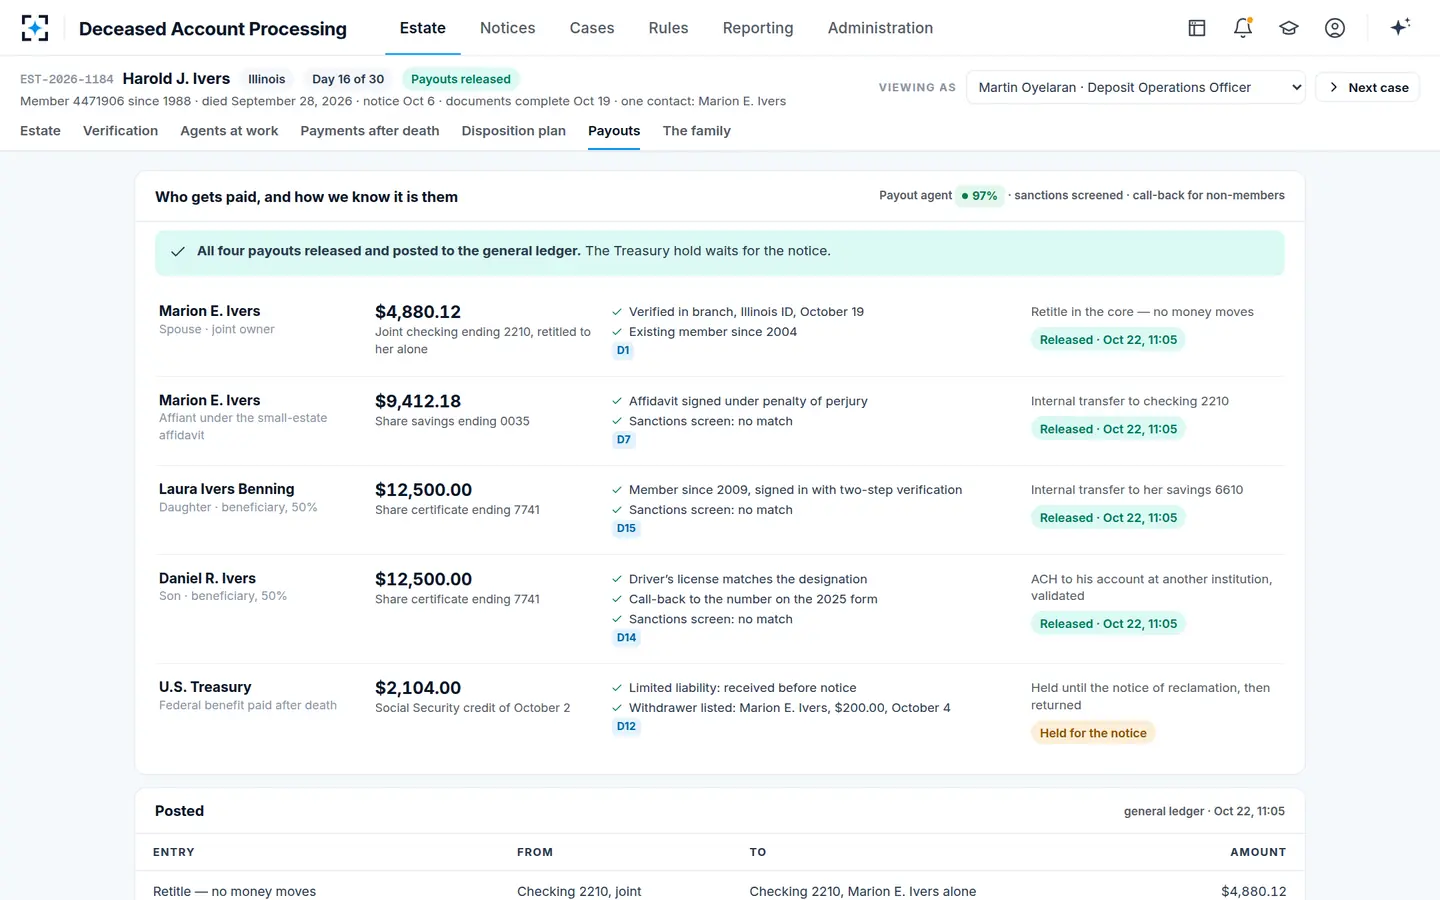
None of this requires a calculator on every estate; it requires the beneficiary designations to be read. In the solution, the Ownership agent reads each designation from document imaging and the Payout agent checks that each beneficiary is alive and identified before any payout, with a second officer releasing each one.
Each payee checked before the officer releases the payout, beneficiaries included
The rest of the estate is in the companion guides: what happens to a bank account when someone dies covers who receives each account, and the sample estate behind these screens is on the Deceased Account Processing page.
Questions people ask
How long does FDIC insurance last after death?
The deceased owner’s deposits are insured as if the owner were alive for six months after the death, unless the accounts are restructured sooner. After six months, coverage follows actual ownership. The grace period is never applied if it would reduce coverage.
Is a payable-on-death account FDIC insured?
Yes, as a trust account: up to $250,000 per eligible beneficiary per owner, to a maximum of $1,250,000 per owner across all trust accounts at the same bank. The beneficiaries must be named in the bank’s deposit account records and must be living people, charities or non-profits.
Does naming more beneficiaries increase FDIC coverage?
Only up to five. Since April 1, 2024, an owner with five or more eligible beneficiaries is insured up to $1,250,000 per bank, however many more are named. A beneficiary named on several trust accounts at the same bank counts once.
Are credit union payable-on-death accounts insured the same way?
From December 1, 2026, yes: the NCUA’s trust accounts category insures each owner up to $250,000 per beneficiary, to $1,250,000 per credit union. Until then the older NCUA rules apply, which the NCUA expects to give the same coverage for most members with less than $1,250,000 in trust deposits.
What happens to FDIC coverage on a joint account when one owner dies?
For six months it is insured as though the owner were still alive. After that, or sooner if the account is restructured, it is insured by actual ownership, which for a survivor usually means as a single account added to the survivor’s other single accounts at the same bank.