A loan should be placed on nonaccrual when principal or interest has been in default for 90 days or more, unless the debt is both well secured and in the process of collection — and, separately and at any time, when full payment of principal or interest is no longer expected, however current the payments are. That second trigger is the one that decides most real cases, and it is the one that is hard to operate, because it asks about the future from a file that arrives one document at a time. Botminds' Problem Loan Management is built around that difficulty: it keeps one page per troubled loan, recomputes coverage on the schedule the borrower actually signed as each statement, payment and appraisal lands, and puts the accrual question in front of the committee with every reason cited. The agents propose. The committee votes.
The rules below are the federal banking agencies' own, linked where they appear. The worked examples use the solution's fictional sample data: Calder Plains Bank, its senior-living borrower Tamarack Senior Living and its packaging borrower Brenmar Plastics.
Continuing to accrue income on assets which are in default as to principal and interest overstates an institution's assets, earnings, and capital.
FDIC, RMS Manual of Examination Policies, section 3.2 Loans (March 2026 revision)
When should a loan be placed on nonaccrual? The rule in one paragraph
The regulatory reporting definition has three limbs, and any one of them is enough. A loan is nonaccrual, the agencies write, when it is "maintained on a cash basis owing to a deterioration in the financial position of the borrower", when "payment in full of interest or principal is not expected", or when principal or interest has been in default for 90 days or more and the obligation is not both well secured and in process of collection (2025 Shared National Credit programme charts, appendix A). Banks tend to read the third limb first because it is the one with a number in it. Examiners read the second.
Two carve-outs are worth knowing before anything else. Consumer loans and real estate loans secured by one-to-four family residential property are exempt from the nonaccrual guidelines, though the FDIC adds that such loans "should be subject to other alternative methods of evaluation to assure the institution's net income is not materially overstated". And any state statute, regulation or rule imposing a more stringent standard takes precedence. Everything on this page is about the commercial book, where the guidelines bite.
The four questions, in the order a credit officer should ask them
1Is principal or interest in default for 90 days or more?
YesGo to question 2 — the exception is the only thing that keeps accrual alive.
NoGo straight to question 4. The 90-day clock is not the only trigger.
2Is the debt well secured?
YesCollateral or a financially responsible guarantee with a realisable value sufficient to discharge the debt in full. Go to question 3.
NoStop accruing. The exception needs both halves.
3Is it in process of collection?
YesCollection proceeding in due course, by legal action or by efforts reasonably expected to repay or restore the loan to current. Accrual may continue — and is re-tested every month.
NoStop accruing. A file with no collection effort in it fails this half.
4Is full payment of principal and interest still expected?
YesAccrual continues, and the answer is documented with the analysis behind it.
NoStop accruing, whatever the payment record says. This is the trigger that catches current loans.
Why the rule exists: accrued income the bank will not collect overstates its capital
Accrual accounting books interest as it is earned, not as it arrives, which is the right answer for a borrower who pays. For a borrower who does not, it quietly manufactures three numbers at once. The receivable grows on the balance sheet. The interest runs through the income statement. And retained earnings — capital — rises on the back of cash nobody received. The FDIC's sentence above states it without hedging.
This is why nonaccrual is an accounting decision with a credit trigger rather than a credit decision with an accounting consequence. It does not forgive anything, it does not reduce the borrower's obligation, and it does not stop the bank pursuing the debt. It stops one thing only: the recognition of income the bank has no reasonable basis to expect. A bank that resists the decision to protect its quarter is borrowing the income from a later one, with interest.
It also explains why the grades and the accrual status move together without being the same thing. The OCC's handbook says that some substandard assets belong on nonaccrual because full collection of principal and interest is in doubt, and that doubtful assets, given their high probability of loss, require nonaccrual treatment (Comptroller's Handbook, Rating Credit Risk). Substandard raises the question; doubtful answers it. What those grades mean, and who assigns them, is set out in the guide to the four grades.
The 90-day test, and the exception that often swallows it
The 90-day limb is the easiest to apply and the easiest to misapply. The Call Report instruction is that where the period of default of principal or interest equals or exceeds 90 days, accrual of income should be discontinued unless the asset is well secured and in process of collection. Note the structure: 90 days does not put a loan on nonaccrual, it removes the presumption that accrual is appropriate. The bank then has to earn the exception, and it has to earn both halves of it.
In the sample bank's file, Tamarack Senior Living reached 90 days past due on 8 October with $11.35 million outstanding, and it is proposed for non-accrual at the next committee for that reason. The proposal is not automatic. Before it is written, the exception is tested on the evidence actually in the file — the current value of the collateral, whether a guarantee stands behind it, and what collection effort is under way and documented. If both halves held, the proposal would be to continue accrual and say why.
Where banks get into trouble is treating the exception as a status rather than a test. "Well secured" rests on a realisable value, and a realisable value rests on a valuation that has not aged past the facts. "In process of collection" rests on activity that is actually happening this month. Both decay. A credit that qualified for the exception in April on a 2022 appraisal and a demand letter does not qualify in October because the April answer is still in the file.
What does well secured and in the process of collection mean?
The FDIC defines both in one passage, and the definitions are narrower than their everyday sense. "A debt is well-secured," it reads, "if collateralized by liens on or pledges of real or personal property, including securities that have a realizable value sufficient to discharge the debt in full; or by the guarantee of a financially responsible party. A debt is in process of collection if collection is proceeding in due course either through legal action, including judgment enforcement procedures, or, in appropriate circumstances, through collection efforts not involving legal action which are reasonably expected to result in repayment of the debt or its restoration to a current status" (FDIC RMS Manual, section 3.2).
Three words do the work. Realizable means what the bank could actually get, after the costs and the time of getting it — not an appraised value, and certainly not a book value. In full means the whole debt, including the arrears and the accrued interest, not the part the collateral happens to cover. And in due course means collection that is moving: a suit filed and progressing, a forbearance being performed, a sale under contract. A file with a demand letter from eleven months ago and nothing since is not in process of collection.
The OCC's accounting staff add a caution about leaning on collateral alone: collateral values "are not sufficient, by themselves, to eliminate the issue of ultimate collectibility of the cost basis in the loan, especially when there is not a high degree of confidence in the accuracy of the estimated collateral value", and without a credit analysis supporting the borrower's capacity to repay "there should be sufficient collateral margin before the bank can conclude that doubt has been eliminated" (OCC Bank Accounting Advisory Series, topic 2B). A thin margin on a stale valuation is not an exception; it is an argument.
The second trigger: when full payment of principal or interest is not expected
This limb has no clock, no exception and no threshold. If the bank does not expect to be paid in full on the contractual terms, interest stops, and the payment record is not a defence. The OCC's staff response to a bank that had charged off the uncollectible portion of a delinquent loan and expected to collect the rest is the sharpest illustration: no, the loan may not return to accrual, because "the call report instructions preclude the accrual of interest for any asset for which full payment of contractual interest or principal is not expected".
Read that twice, because it decides a common argument. Full payment means full payment of what was contracted, not of the balance that survives a charge-off. A bank cannot write the loan down to the amount it expects, then accrue on the remainder as though the shortfall never existed.
The same section settles a second argument, about where the test is applied. "Loans should be evaluated individually," the staff write, but "the borrower's total exposure must be considered, however, before concluding that doubt has been removed over the collectibility of either loan." Two facilities to the same borrower are two decisions — and neither can be made as though the other one does not exist.
Can a loan be current and still belong on nonaccrual?
Yes, and the manual says so in a single sentence: "Nonaccrual loans may include both current and past due loans." It is the sentence that separates a credit function from a delinquency report.
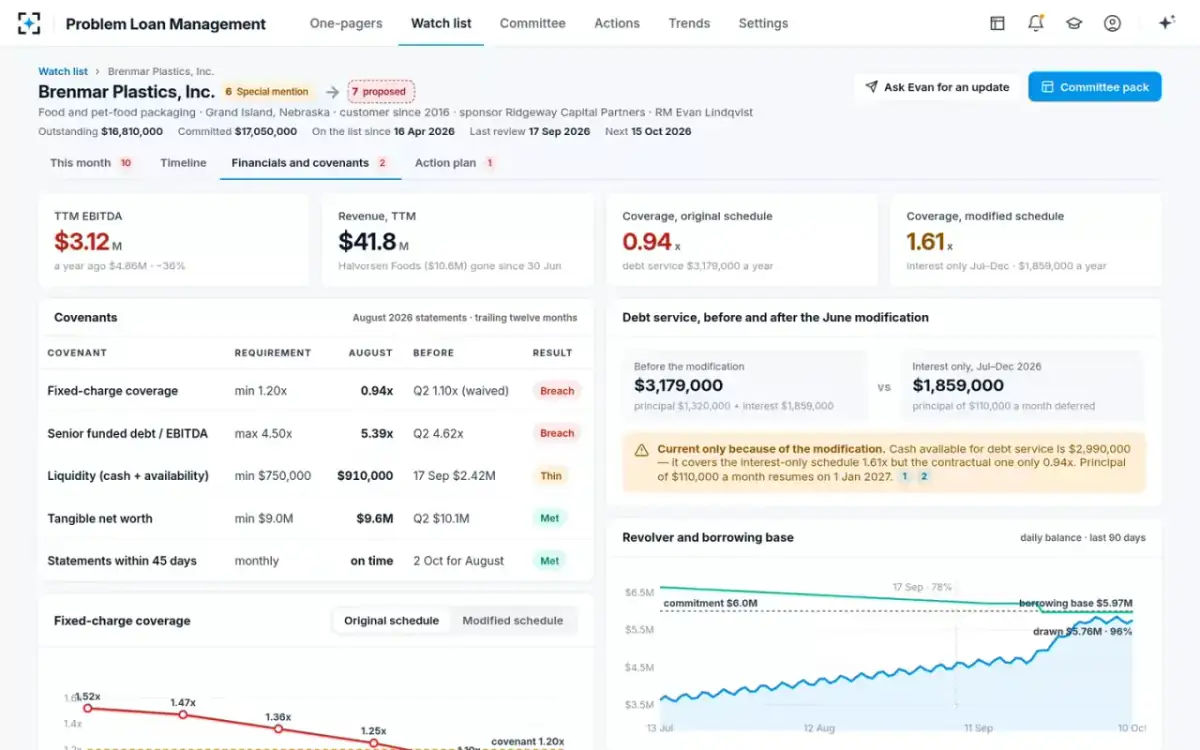
Brenmar Plastics is the sample bank's case of it. Since July its term loan has paid interest only, with $110,000 a month of principal deferred to December, so every payment has arrived on the day it was due under the amendment. On the schedule the borrower signed, the third quarter's payments were $465,000 against $795,000 contractually due. Cash available for debt service of $2,990,000 covers the modified schedule 1.61x and the original one 0.94x, against a 1.20x fixed-charge covenant. The delinquency report shows nothing. The contractual test shows a borrower who cannot service its own loan.
The same quarter on two schedules, and the different question each one answers
On the modified schedule: $465,000, every one on time
On the schedule the borrower signed: $795,000 was contractually due
On the modified schedule: 1.61x on $2,990,000 of cash available
On the schedule the borrower signed: 0.94x on the same $2,990,000
On the modified schedule: Reads as met, at 1.61x — if the reduced payments are allowed to stand in for the debt service
On the schedule the borrower signed: Breached, at 0.94x
On the modified schedule: Current
On the schedule the borrower signed: Current, and still not able to pay
On the modified schedule: Nothing: a schedule the bank wrote to accommodate the borrower proves only that the bank wrote it
On the schedule the borrower signed: Whether full payment of contractual principal and interest is still expected
A modification does not change which schedule the second trigger asks about. It changes the cash flow, and it is evidence about the borrower — usually evidence that supports the conclusion rather than rebutting it. Why the accounting label for that changed in 2022 while the credit question did not is the subject of what defines a troubled debt restructuring.
Financials and covenants in Problem Loan Management, tested on the original terms
What happens to the interest already booked, and to the payments that arrive after
Two separate questions, and banks blur them. The first is the interest already accrued and unpaid at the moment the loan goes on nonaccrual. The FDIC directs that the reversal "should be handled in accordance with generally accepted accounting principles", and names the acceptable treatment: "reversal of all previously accrued but uncollected interest against appropriate income and balance sheet accounts". The receivable comes off, and the income comes out of the period it is reversed in.
The second is what to do with cash that arrives afterwards, and it turns on a single question: does doubt exist about the ultimate collectibility of principal? If it does, every payment reduces principal. The OCC's staff response is unambiguous — when doubt exists, wholly or partially, "payments received on a nonaccrual loan must be applied to reduce principal to the extent necessary to eliminate such doubt". Only when the bank can demonstrate that the doubt no longer exists may subsequent interest payments be taken into income, and then on a cash basis as they arrive.
Where a payment on a nonaccrual loan goes, and the test behind each answer
| The situation | Where the cash goes | What the bank has to be able to show |
|---|---|---|
| Doubt exists about ultimate collectibility of principal | All of it reduces principal — cost recovery. No interest income. | Nothing: this is the default. Doubt is presumed while the loan is on nonaccrual and the analysis has not removed it. |
| Doubt has been demonstrably removed | Interest received may be recorded as interest income on a cash basis as it arrives. | A credit analysis supporting repayment capacity, and sufficient collateral margin where the case rests on collateral. |
| The loan has been partially charged off and a contractual payment arrives | May be allocated among interest income, reduction of principal and recovery of prior charge-offs — or reported entirely as one of them. | A written accounting policy that conforms to GAAP, applied consistently to the condition of the loan. |
| Interest accrued and unpaid at the moment of transfer | Reversed against income and the receivable, per GAAP. | That the reversal hit the right period. It is a charge to the current period, not a restatement of the last one. |
When can a loan be returned to accrual status?
When two conditions are met together, and six months is only one of them. The FDIC sets out both for a borrower who has resumed paying the full scheduled amounts: first, "all principal and interest amounts contractually due (including arrearage) are reasonably assured of repayment within a reasonable period", and second, "there is a sustained period of repayment performance (generally a minimum of six months) by the borrower, in accordance with the contractual terms involving payments of cash or cash equivalents".
Each phrase is load-bearing. Including arrearage means the missed payments count, not just the current ones. In accordance with the contractual terms means the schedule the borrower owes, which is why six months of performance on a restructured schedule is a different claim and has to be argued separately. Cash or cash equivalents excludes capitalised interest, a payment funded by the bank's own new advance, and interest paid in kind. A loan that is current because the bank lent it the money to be current has not demonstrated anything.
Two practical points follow. Previous charge-offs do not have to be fully recovered before the loan goes back on accrual — the test is about expectation, not restitution. And a loan restored to accrual continues to be disclosed as past due, as appropriate, until it has been brought fully current, so the past-due report and the accrual status will legitimately disagree for a while.
Three months down, six months up: the clock is not symmetrical
- Payment misseddays 1–30
- 60 days past duedays 31–60
- 90 days: accrual stops unless well secured and in process of collectiondays 61–90
- Sustained repayment performance on the contractual terms, in cash — generally a minimum of six months6 months
What the file has to show before a nonaccrual loan goes back on accrual
- Six months of payments, in cash, on the contractual terms
Dated payment records, not a summary. Capitalised interest and payment-in-kind do not count, and neither does a payment funded by a new advance.
- The arrearage addressed, not ignored
A written path by which the missed principal and interest are repaid within a reasonable period, and the evidence that the borrower can follow it.
- A current cash flow analysis
Spread from the borrower’s own statements, showing capacity to service the whole contractual schedule, not the part being paid now.
- A collateral value the bank would stand behind
Dated, and tested against the debt in full. If the argument rests on collateral, say what the margin is.
- The grade reconsidered at the same time
Accrual status and risk rating answer different questions. A loan can return to accrual and remain substandard; the committee should say both out loud.
- The reasoning written down, with its sources
The examiner reads the decision, not the outcome. An undocumented restoration is the one that gets reversed on review.
A modified loan: which schedule is the test applied to?
The contractual one, until a formal restructuring makes the new terms the contractual terms — and even then, the restructured loan has to earn its own period of performance before it accrues. The OCC's staff refused accrual on a renegotiated loan with new collateral and new funds on exactly that ground: the loan "should remain on nonaccrual status until the borrower has demonstrated the ability to comply with the new loan terms".
This is the discipline that a monthly committee most easily loses, because the amended schedule is the one in the loan system and the original one is in a document somebody has to read. In Problem Loan Management the modification screen looks back twenty-four months for every amendment, extension, deferral, rate concession, interest-only period and payment-in-kind feature, and computes debt service on both schedules every time new figures land. When a loan is current only because of a modification, the page says so in those words, and so does the committee pack.
It matters for the grade as well as the accrual decision. A restructured credit that later meets the nonaccrual criteria on its modified terms goes back on nonaccrual; the restructuring is not a one-way door. And the allowance follows: at the sample bank, if Thursday's proposals all pass, non-accrual rises to $71.9 million and the allowance by about $1.7 million. Those are the solution's sample figures for one fictional bank, and nothing more.
One loan, one decision, with the test shown on the page
When a nonaccrual decision goes wrong, the cause is seldom that somebody misread the rule. It is that the facts the rule needs — a current collateral value, this month's collection activity, the contractual schedule, the cash flow — live in four systems and a shared drive, and get assembled by hand the week before a committee. By then the decision is being made on April's answer to an October question.
What a current page changes is the order of the work. The monitor reads each new document as it arrives and logs it against the name with its source. The spreader recomputes the covenants as the agreement defines them. The modification screen recomputes debt service on both schedules. The recommender then proposes — accrual or non-accrual, with each reason cited to a document and the allowance effect stated — and stops there. At the meeting the Chief Credit Officer, the Chief Risk Officer, the Chief Lending Officer and the CFO vote, and the chair signs the minutes. The software never sets an accrual status, and it should not: this is a judgement a bank's officers answer for.
The proposal, every reason cited, in Problem Loan Management
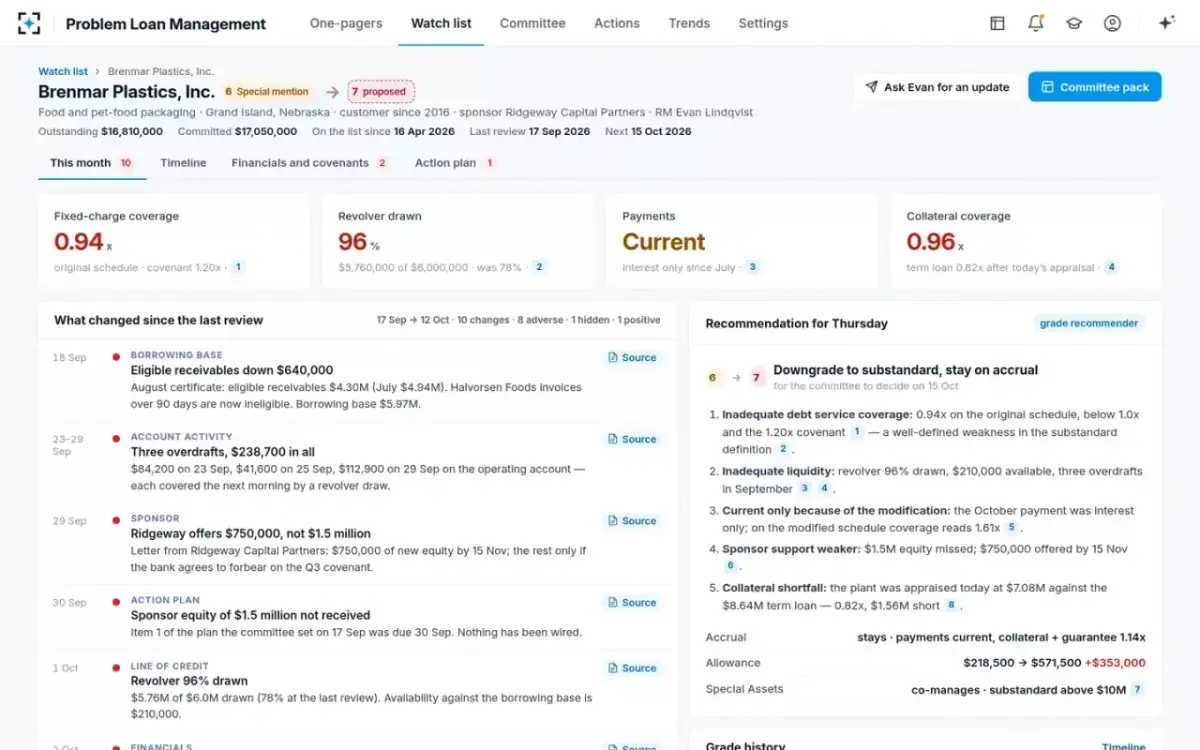
The recommender proposes. The committee votes the accrual status.
Where a non-accrual name goes next — and the threshold at which it leaves the lending line altogether — is covered in what a special assets department is. How the totals reach the board is in the criticized asset report. To see the pages and the committee together, start from Problem Loan Management.
Questions people ask
What is a nonaccrual loan?
A loan on which the bank has stopped recognising interest income as it is earned, because collection of the full contractual amount is in doubt. It is a reporting and accounting status, not a legal one: the borrower still owes everything, and the bank may still collect, sue or foreclose. For regulatory reporting a loan is nonaccrual if it is maintained on a cash basis because of the borrower's deteriorated condition, if payment in full of principal or interest is not expected, or if it has been in default 90 days or longer without being both well secured and in process of collection.
How is interest handled on a nonaccrual loan?
Interest stops accruing from the date of transfer. What happens to cash received afterwards depends on whether doubt exists about ultimate collectibility of principal: while it does, every payment reduces principal and none is income. Once the bank can demonstrate the doubt is gone, interest received may be recognised on a cash basis as it arrives. On a partially charged-off loan a contractual payment may instead be allocated among interest income, principal and recovery of prior charge-offs under a consistent written policy.
Is a nonaccrual loan automatically classified substandard or doubtful?
Not automatically, but the two travel together and a mismatch is a question an examiner will ask. The OCC's handbook expects nonaccrual treatment for doubtful assets and says some substandard assets should be on nonaccrual because full collection of interest and principal is in doubt. A pass-rated loan on nonaccrual, or a doubtful loan still accruing, is a grading system disagreeing with itself.
Does a modified loan have to go on nonaccrual?
Not by virtue of being modified. The test is whether full payment of what is contractually due is still expected and whether the loan is in default 90 days or more without qualifying for the exception. In practice a concession granted because the borrower could not pay is evidence about the answer. A renegotiated loan that was already on nonaccrual stays there until the borrower has demonstrated the ability to comply with the new terms, and performance has to be in cash.
Who decides to put a loan on nonaccrual?
Inside the bank, management decides and the decision is governed by credit policy — typically proposed by the credit or portfolio function and voted by a committee chaired by the Chief Credit Officer, with loan review present independently of the lending line. Examiners can and do require a change on review. No software should make the call: in Problem Loan Management the recommendation is proposed with every reason cited to a document, and the committee votes it.
What is the difference between nonaccrual and charge-off?
Nonaccrual stops future income; a charge-off removes a balance the bank no longer considers an asset. They answer different questions and often happen at different times — a loan can be on nonaccrual for a year before any part of it is charged off, and a partially charged-off loan commonly remains on nonaccrual. Restoring a loan to accrual does not require previous charge-offs to be recovered first; the criteria are about what is now reasonably assured.