The FHA guidelines for 2026 are HUD Handbook 4000.1, the FHA Single Family Housing Policy Handbook, as revised by Update 17 on 26 November 2025 and Update 18 on 12 August 2026, together with the mortgagee letters HUD issues between updates. Update 18 folds in eight mortgagee letters and a list of other changes; HUD says most of them "may be implemented immediately, but must be implemented no later than November 10, 2026". So for three months of 2026 two texts of the Handbook were both correct for some loans, and which one governs a particular file depends on a date in that file. That is the question Botminds' Mortgage Guideline Search is designed to settle on every answer: it searches HUD Handbook 4000.1 and the mortgagee letters in the version in force on the date that decides the loan, and cites the passage, so an underwriter, and later QC, can see which text was applied.
FHA guidelines in 2026, in four numbers
1,872pages
in the Update 18 edition of Handbook 4000.1, issued 12 August 2026
8
mortgagee letters superseded in whole by Update 18
39
Handbook sections now dated 11/10/2026, the deadline for applying the update
11
mortgagee letters numbered in 2026 by October, single-family and multifamily
What are the FHA guidelines for 2026?
One book, consolidated, plus what has not yet been folded into it. HUD describes Handbook 4000.1 as "a consolidated, consistent, and comprehensive source of FHA Single Family Housing policy", into which "hundreds of FHA Handbooks, Mortgagee Letters, Housing Notices, and other policy documents have been consolidated", which "eliminates the need for mortgagees and other stakeholders in FHA transactions to search through multiple stand-alone policy documents" (HUD, Handbook 4000.1 information page). It follows the life of a loan in five sections: doing business with FHA, origination through endorsement, servicing and loss mitigation, claims and disposition, and quality control.
The consolidation is real, but it runs behind. A mortgagee letter takes effect on its own terms, often months before the Handbook update that absorbs it, and between updates the rule a loan must meet lives in the letter. The 2026 loan limits are an example: Mortgagee Letter 2025-23 set them "for case numbers assigned on or after January 1, 2026", with a one-unit floor of $541,287 and ceiling of $1,249,125, and said the updates "will be incorporated into a forthcoming update" of the Handbook (ML 2025-23). Update 18 then replaced the printed limits with a standing link, so future limits will not wait for an update at all.
What changed in FHA Handbook 4000.1 Update 18?
Update 18 incorporates mortgagee letters issued since the previous edition and makes a set of refinements HUD lists section by section in its transmittal (Update 18 transmittal). For origination, the changes that reach an underwriter's or processor's day include the removal of the Important Notice to Homebuyers form, refined rules for reusing an appraisal and ordering an appraisal update, refined flood-zone requirements, a single definition of manufactured housing, new definitions for written, electronic and re-verification of employment, and the end of HUD's own underwriting of HUD employee loans.
Handbook 4000.1 Update 18: selected origination changes and their source
| Change | Handbook section | Source |
|---|---|---|
| Form HUD-92900-B, Important Notice to Homebuyers, no longer required | II.A.1.a.ii(A)(2) | ML 2026-07 |
| Refined requirements for reusing an appraisal and ordering an update | II.A.1.a.iii(B)(6), (10) | Update 18 |
| Refined requirements for properties in Special Flood Hazard Areas | II.A.1.b.iv(A)(1) and II.B.2.b.iii(A)(4) | Update 18 |
| One definition of manufactured housing throughout the Handbook | II.A.1.b.iv(B)(7)(a) and four other sections | Update 18 |
| Loan limits replaced by a standing link instead of annual figures | II.A.2.a.ii | Update 18 |
| HUD employee loans no longer submitted to FHA for underwriting | II.A.4.a.i, II.A.5 and others | Update 18 |
| Definitions of written, electronic and re-verification of employment | II.A.4.c.ii, II.A.5.b.ii, II.B.5.e.ii(A) | Update 18 |
| More draw requests for Limited 203(k) | II.A.8.a.vii(B) and related | ML 2026-06 |
| Fewer requirements for mortgagee approval and quality control | I.A.3.c.iv(B)(2)(b), V.A.2 and related | ML 2026-09 |
When must lenders implement Handbook 4000.1 Update 18?
By 10 November 2026 for most of it. The transmittal gives two effective-date rules. Changes that incorporate a mortgagee letter are "effective as previously announced in the corresponding Mortgagee Letter". All other changes "may be implemented immediately, but must be implemented no later than November 10, 2026" (Update 18, section 3). In the Handbook itself the deadline shows up as a date: 39 sections in Update 18's table of contents carry "(11/10/2026)", among them Underwriting with an Automated Underwriting System and the FHA Defect Taxonomy in Appendix 8.0.
Which Handbook text governs: 2026 in three phases
- Update 17 text26 Nov – 11 Aug
- Update 18 out; most changes optional12 Aug – 9 Nov
- Update 18 requiredfrom 10 Nov
The amber window is where guideline answers drift. A training note written in July describes Update 17. A lender that adopted Update 18 on 12 August and one that waited until 10 November were both compliant through October, so an answer that says "FHA requires" without saying which text, and from when, is ambiguous for a loan underwritten in that window. After 10 November only one text is right for new work, but loans underwritten in the window are still judged by the text that applied to them.
FHA mortgagee letters 2026: the eleven so far
HUD's list shows mortgagee letters 2026-01 to 2026-11 by October, a mix of single-family and multifamily policy (HUD Mortgagee Letters). For single-family lending: 2026-02 on selling a beneficial interest in a group of mortgages; 2026-03 on bidding at foreclosure; 2026-06 on Limited 203(k) draws; 2026-07 rescinding the Important Notice to Homebuyers; 2026-08 on loss mitigation; 2026-09, "Eliminating Unnecessary Requirements for FHA Mortgagee Approval and Quality Control"; 2026-10 on quality control for appraisal field reviews; and 2026-11, "Updated Minimum Decision Credit Score Methodology for the Implementation of Alternative Credit Scores". Letters 2026-01, -04 and -05 are multifamily.
Update 18 superseded eight letters in whole: 2025-24 and 2026-02, -03, -06, -07, -08, -09 and -10. Mortgagee Letter 2026-11, on credit score methodology, is not on that list, so for that subject the letter itself is the text to read until a later update absorbs it.
FHA credit score requirements in 2026
The Handbook ties maximum financing to the borrower's Minimum Decision Credit Score. "At or above 580" the borrower is "eligible for maximum financing"; "between 500 and 579" the borrower is "limited to a maximum LTV of 90%"; and borrowers with non-traditional or insufficient credit can have maximum financing but must be manually underwritten (Handbook 4000.1, II.A.2). For purchases, the maximum LTV is 96.5% of the adjusted value. Those floors are FHA's; many lenders and investors set higher ones, which the guide to lender overlays explains.
How the decision score is worked out is changing. Mortgagee Letter 2026-11 updates the methodology to implement alternative credit scores, which is why a 2026 answer on FHA credit has to read the letter as well as the Handbook, and say which it relied on.
The FHA rules underwriters look up most, as they read in 2026
Most guideline questions on an FHA desk come back to a handful of sections, and each has its own wording and date. The table gives the 2026 text in short, with the section to cite; the 2026 mortgage guidelines cheat sheet sets the same points beside Fannie Mae, Freddie Mac and VA.
Six FHA rules in Handbook 4000.1, 2026 text
| Question | Handbook 4000.1 says | Where |
|---|---|---|
| Minimum credit score | 580 or above for maximum financing; 500 to 579 limited to 90% LTV | II.A.2, LTV by Minimum Decision Credit Score |
| Maximum LTV on a purchase | 96.5% of the Adjusted Value | II.A.2, Purchase |
| Student loan shown at $0 | 0.5% of the outstanding balance, whatever the payment status | II.A.4.b.iv(H) (TOTAL) |
| How long self-employed | At least two years; one to two years only with two years before in the same or a related line of work | II.A.4.c.x (TOTAL) |
| Falling business income | A decline of more than 20% over the analysis period requires a downgrade to manual underwriting | II.A.4 (TOTAL), downgrade rules |
| Age of documents | No more than 120 days old at the disbursement date, with separate rules for appraisals | II.A.1, Maximum Age of Mortgage Documents |
The rows look stable, but the paragraphs around them move. Update 18 added definitions of written, electronic and re-verification of employment beside the income sections, and Mortgagee Letter 2026-11 changes how the decision score in the first row is determined. A desk reference that copies the table without the dates will be right until the next update and wrong after it, with nothing on the page to say so.
Which version of the FHA handbook applies to my loan?
The version in force for that section on the date the change counts from. The Handbook's own quick guide explains the mechanism: "Effective dates are shown at the end of heading titles, at the 4th level (e.g., I.A.1.a) in parentheses", and "yellow highlighted text indicates the most recent updates" (Handbook 4000.1, User Quick Guide). Sections are dated independently: in Update 18, 69 sections still carry 09/14/2015, the date the Handbook's first sections took effect, while 50 carry a 2026 date.
Each mortgagee letter states its own basis, and case number assignment is a common one: the 2026 loan limits apply "for case numbers assigned on or after January 1, 2026". To answer "which version applies", then, the person answering needs three things at once: the section's date, the letter's effective basis, and the loan's own dates. HUD keeps every previous version: they are "available on the HUD Archives website" (HUD), so an answer can always be checked against the text that applied.
"FHA requires" is not an answer in 2026. "Handbook 4000.1, Update 18, section II.A.4.b, in force for this case number" is.
How do I document which guideline I used?
Write the citation into the file at the time, with enough detail that a reviewer can open the same text. FHA does not review a loan before endorsing it under the Direct Endorsement program; the lender's own underwriting and quality control are the control (U.S. Department of Justice, 2016). When FHA does review later, in fiscal 2022 it found net material defects in 11.26% of 27,405 underwriting reviews (HUD, FHA Quality Assurance Update, 2023), and each finding is judged against the requirements that applied to that loan. The guide to the FHA indemnification agreement follows what happens after a finding.
A defensible FHA guideline answer records
- The section and its own date
For example II.A.4.b.iv(H), Student Loans (TOTAL), in the Update 18 text.
- The edition of the Handbook
Update 17 or Update 18, and for the optional window, which one the lender had adopted.
- Any mortgagee letter not yet absorbed
Its number, its effective basis, and why it governs or does not.
- The loan’s deciding date
Case number assignment, application or another date the letter names.
- The lender’s or investor’s overlay
If a stricter rule applies to the loan, both rules and which governs.
- Who decided
The DE underwriter’s name on the note, and any exception’s approver.
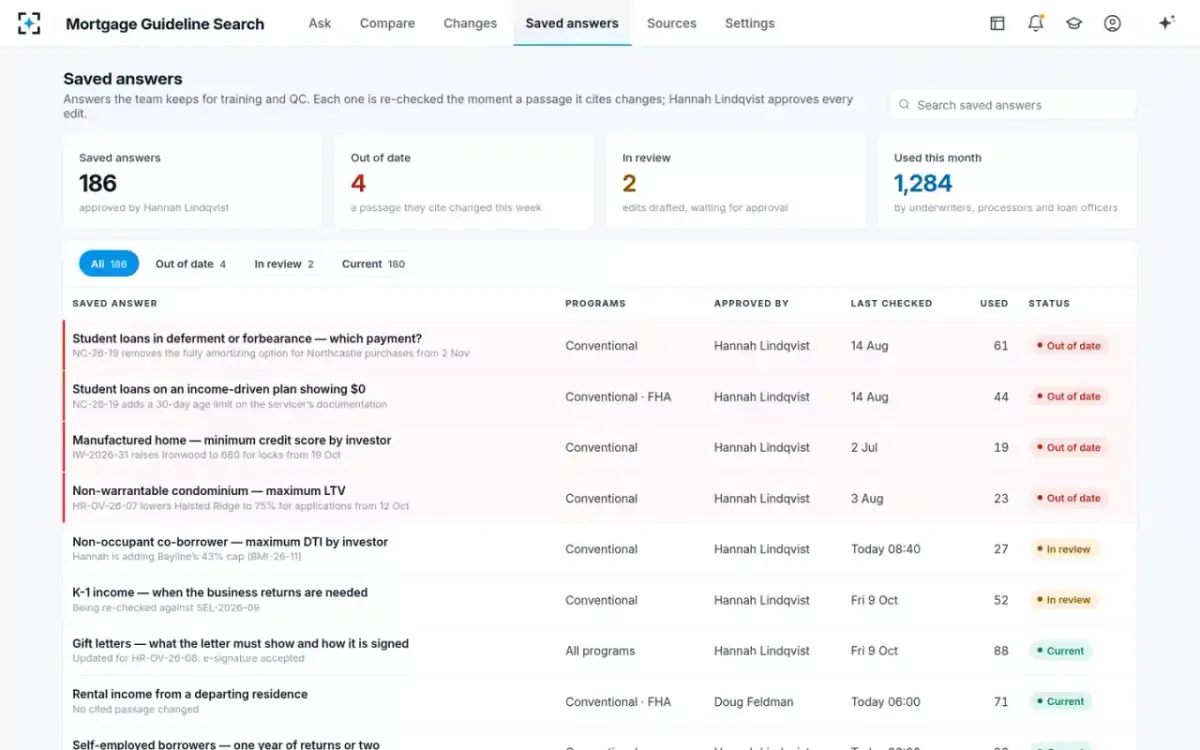
In Mortgage Guideline Search, each saved answer the training team keeps is re-checked the moment a passage it cites changes, and QC reads it as it read on the day the file was underwritten. In the sample library, 186 saved answers are kept for training and QC; four were marked out of date in one week because a passage they cite had changed, with the edits drafted for the policy lead to approve.
Saved answers, re-checked when a cited passage changes
Questions people ask
What is the latest version of the FHA handbook?
As of October 2026 it is Handbook 4000.1 Update 18, issued on 12 August 2026, which follows Update 17 of 26 November 2025. HUD publishes a redline version alongside it, and previous versions stay available on HUD's archives website.
Is the FHA minimum credit score still 580?
For maximum financing, yes: Handbook 4000.1 allows maximum financing at a Minimum Decision Credit Score of 580 or above and limits borrowers between 500 and 579 to 90% LTV. Mortgagee Letter 2026-11 updates how the decision score is determined to implement alternative credit scores, and many lenders set higher floors as overlays.
Where can I get an answer to an FHA guideline question?
HUD's FHA Resource Center takes questions at answers@hud.gov or (800) CALL-FHA, 8 a.m. to 8 p.m. Eastern on federal business days. For a cited answer that also reads your investors' overlays and your loan, the guide to mortgage guidelines AI sets out what to look for.
Do mortgagee letters still matter now that there is one handbook?
Yes. A mortgagee letter takes effect on its own terms, often before the Handbook update that absorbs it, and a letter not yet absorbed, such as ML 2026-11 after Update 18, is the governing text on its subject until it is.
What are the FHA loan limits for 2026?
For case numbers assigned on or after 1 January 2026, Mortgagee Letter 2025-23 set the one-unit limit at $541,287 in low-cost areas and $1,249,125 in high-cost areas, 65% and 150% of the $832,750 conforming limit. Limits for each county fall between those figures.