The difference between a passive NFE and an active NFE is a test of what a non-financial entity does with its money: under the Common Reporting Standard (CRS), an entity that is not a financial institution is an active NFE if it passes one of a short list of tests, most often that less than half its income and less than half its assets are passive, and a passive NFE if it passes none. The answer matters because a passive NFE brings its controlling persons into the report, so a fund that accepts "active" when the entity is passive leaves the people who own it unreported. FATCA has the same distinction under nearly the same names, which is why the tree has to be run twice and the two answers compared. Botminds' FATCA/CRS Self-Certification runs that comparison on every entity investor's forms and puts any disagreement in front of an analyst.
The examples use the solution's sample data on a fictional fund manager, Quillfield Capital, and its fictional investors. The rules are quoted from HMRC's International Exchange of Information Manual and the IRS instructions, which follow the CRS and FATCA texts closely.
Passive NFE vs active NFE, as the rules apply it: six questions in order
- 1
Does it conduct, as a business, investing or managing money for customers, with at least half its gross income from that over three years?
If yesInvestment entity: a financial institution
- 2
If not, is it managed by a financial institution with discretion over its assets, and is at least half its gross income from investing in financial assets?
If yesInvestment entity: a financial institution, unless resident in a non-participating jurisdiction, where it is treated as a passive NFE
- 3
Is it listed, or related to a listed company, or a government entity, international organisation or central bank?
If yesActive NFE
- 4
Was less than half its gross income passive last year, and were less than half its assets held for passive income?
If yesActive NFE: both halves must pass
- 5
Is it a holding company of a non-financial group, a start-up in its first 24 months, an NFE liquidating or reorganising, a group treasury centre or a tax-exempt non-profit?
If yesActive NFE, with the conditions each category carries
- 6
None of the above?
If yesPassive NFE: identify every controlling person and obtain their self-certifications
What is a passive NFE?
A passive NFE is a non-financial entity that does not qualify as active, and the rules build it as the default. HMRC's manual says so directly: "The Passive NFE category is effectively a default category, any NFE that does not meet the criteria to be an Active NFE will be a Passive NFE" (HMRC IEIM404040). An investor does not have to do anything to become passive; it has to show that one of the active categories applies.
Typical passive NFEs among fund investors are family holding companies whose only assets are portfolio interests, personal investment vehicles with no manager holding discretion, foundations living on investment income, and companies that have sold their business and kept the cash. One more group is passive by rule rather than by fact: a professionally managed investment entity resident in a jurisdiction that does not participate in the CRS is treated as a passive NFE, so that its owners cannot escape reporting by choosing where to set it up (HMRC IEIM403480).
What is the difference between an active and a passive NFE?
An active NFE passes at least one of the active tests; a passive NFE passes none. The test most fund investors rely on is the income-and-assets test, and it has two halves that must both pass: less than 50% of gross income for the preceding calendar year was passive, and less than 50% of the assets held in that period produced or were held for passive income (HMRC IEIM404040).
Passive income is defined broadly: dividends and other distributions, interest, rents and royalties not earned in an active trade carried on by the entity's own employees, annuities, gains on financial assets and income from relevant crypto-assets, among others (HMRC IEIM404020). The asset half catches entities that have no income yet. HMRC notes that "cash will generally be regarded as a type of asset held for the production of passive income even if held in a non- interest bearing account". A company that sold its operating business for cash in March and invested in a fund in June may pass the income half on last year's trading accounts and fail the asset half the day the sale closed.
The numbers inside the active tests
<50%
of last year’s gross income may be passive for the income half of the test
<50%
of assets may be held for passive income: both halves must pass
24
months from formation that a start-up can claim active status
5
years without being a financial institution, for a liquidating NFE to stay active
Step one: is the entity a financial institution? The managed-by test
Before an entity can be active or passive it must not be a financial institution, and the question fund operations get wrong most often is whether an investor is an investment entity because someone manages its money. Under the CRS an entity is an investment entity if it is managed by a financial institution and its gross income is primarily from investing, reinvesting or trading in financial assets, measured as at least half its gross income over the shorter of three years or its life (HMRC IEIM400770).
The test turns on discretion. HMRC's wording: "An entity is not regarded as managed by a financial institution if that Financial Institution does not have discretionary authority to manage the entity's assets either in whole or in part" (HMRC IEIM400770). A holding company whose bank merely holds its securities is not managed by the bank; one that has handed a licensed asset manager full discretion over its portfolio is, and it becomes a financial institution in its own right, with no controlling persons on its CRS form.
The IRS says the same thing in FATCA terms, inside the passive NFFE part of the W-8BEN-E. An entity that "would be a passive NFFE but for the fact that you are managed by certain types of financial institutions" should not tick the passive NFFE box, "as you would be considered a financial institution and not a passive NFFE" (IRS, Instructions for Form W-8BEN-E, Part XXVI). The managed-by entity then needs a FATCA status of its own, for example as a sponsored FFI with its manager as sponsor, which is the status that collides with "passive NFE" on a CRS form in the case at the heart of the entity form against its W-8BEN-E.
When is an entity an investment entity under CRS?
On either of two routes: it conducts investment activities as a business for customers, or it is managed by a financial institution and earns mainly investment income. The activity route covers trading in money market instruments, foreign exchange, transferable securities and commodity futures, individual and collective portfolio management, and "otherwise investing, administering or managing funds or money on behalf of other persons", when at least half the entity's gross income comes from those activities (HMRC IEIM400770).
Most fund vehicles meet the definition on sight: HMRC says an entity is generally an investment entity "if it functions or holds itself out as a collective investment vehicle, mutual fund, exchange traded fund, private equity fund, hedge fund, venture capital fund, leveraged buy-out fund or any similar investment vehicle". That matters for funds of funds and feeder structures, where the investor on the register is itself a fund. It also explains a common error: a feeder fund that ticks "active NFE" because it has a real business is not an NFE at all.
Two carve-outs keep the definition from swallowing everything. An entity that primarily invests in, administers or manages direct, non-debt interests in real property for others is not an investment entity. And where an entity meets both routes, its status as an activity-based investment entity takes precedence. From 1 January 2026 the activity list and the financial assets test also include relevant crypto-assets.
Is a holding company a passive NFE?
Often, but not always. A holding company is an active NFE if, in HMRC's words, it is a holding company "for NFEs that are members of a non-financial group". HMRC adds the exception that decides most fund-investor cases: "It will not qualify as an Active NFE where these holdings are part of a business as an investment fund or vehicle whose purpose is to acquire or fund companies and then hold interests as capital assets for investment purposes" (HMRC IEIM404040).
So the family holding company of a manufacturing group is active; the family holding company that sold the group and now holds fund interests is not, and it fails the income-and-assets test too. The holding companies that invest in private funds are usually the second kind. A holding company that certifies "active NFE" on the strength of its corporate form, with annual accounts showing mostly fund units, is the classic contradiction the cross-check catches: at the sample manager, the work list's first item was an entity whose W-8BEN-E and CRS form both said active NFE while its annual accounts showed 92% of assets in fund units.
Five sample investors, and where the tree puts them
| Investor | What the file shows | Where the tree lands | What changes |
|---|---|---|---|
| Hanseatic Lindenhof Stiftung | Passive income 71% of gross income in 2025 (annual accounts, p. 14) | Passive NFE: fails the income half | Two controlling persons reportable to Germany through Luxembourg; no US reporting |
| Bellmont Ridge Holdings S.A. | 92% of total assets in fund units (2025 accounts, p. 6) | Passive NFE: fails the asset half | Controlling persons to be documented, then reportable to France and Luxembourg |
| Norvik Maritime Holdings AS | Discretionary management agreement with a Norwegian bank | Investment entity: managed by a financial institution | No longer reportable as an account holder; controlling-person records closed |
| Tamarind Bay Investments Ltd | Its manager is not a financial institution (registry, p. 2) | Passive NFE: the managed-by test fails | Three controlling persons resident in Canada and the UK become reportable |
| Kestrel Ridge Investments Ltd | Full discretion over its assets given to a fund management company | Investment entity, which its W-8BEN-E says in FATCA terms | Its CRS form says passive NFE: the investor must cure one form or the other |
How does CRS 'passive NFE' map to FATCA 'passive NFFE'?
Closely, but not exactly. In the IRS's words, "A non-financial foreign entity (NFFE) is a foreign entity that is not a financial institution" (IRS, Form 8966 instructions), and the ADGM regulator's decisions define "Passive NFE" as having the CRS meaning for CRS and as "a Passive NFFE (as that term is defined in the IGA)" for FATCA (ADGM FSRA, ADS decision, Annexure A). What the two regimes ask of a passive entity differs.
The same entity under two regimes: what each asks of a passive investor
CRS: passive NFE: Controlling persons resident in any reportable jurisdiction
FATCA: passive NFFE: Substantial US owners, or controlling US persons where an IGA applies
CRS: passive NFE: The entity form plus a self-certification for each controlling person
FATCA: passive NFFE: W-8BEN-E Part XXVI, with owners listed in Part XXIX or a certification that there are none
CRS: passive NFE: Investment entity, not an NFE (managed-by test)
FATCA: passive NFFE: Not a passive NFFE: a financial institution needing its own chapter 4 status
CRS: passive NFE: Unreported controlling persons; per-account penalties, for example in the UK and in ADGM
FATCA: passive NFFE: 30% withholding on withholdable payments if the owner information is not given
CRS: passive NFE: Treats a managed investment entity in a non-participating jurisdiction as passive
FATCA: passive NFFE: A direct reporting NFFE reports its own US owners to the IRS and holds a GIIN
The IRS instructions also allow one deliberate asymmetry: an NFFE that may qualify as active "may still check line 40a and disclose your substantial U.S. owners or certify that you have no substantial U.S. owners" (IRS, W-8BEN-E instructions). A W-8BEN-E that says passive NFFE next to a CRS form that says active NFE is therefore not automatically a contradiction. A W-8BEN-E that says sponsored FFI next to a CRS form that says passive NFE is, because one says a financial institution manages the entity and the other says nobody does.
Why the classification decides whether controlling persons are reported
Because the CRS looks through only one kind of entity. For each new entity account the institution must determine whether the holder is itself reportable and whether it "is held by one or more entities that are Passive NFEs with one or more Controlling Persons who are Reportable Persons" (HMRC IEIM403420). Classify the holder as active, or as a financial institution, and the owners drop out of the report entirely; classify it as passive, and each of them needs a self-certification with residence and TIN.
That asymmetry is why a wrong "active" is the expensive error. A wrong "passive" reports people who need not have been reported, which the fund must correct; a wrong "active" leaves reportable people out of the exchange, and a regulator who finds it treats the account as reported incompletely. It is also why classifications go stale: an entity that was active on last year's trading accounts can be passive this year, and HMRC's example of a start-up whose 24 months ran out shows that a lapse is a change in circumstances that invalidates the form (HMRC IEIM402183). How such a change sends a form back, and the 90 days that follow, is in the KYC change that sends a form back.
Running the tree twice, and comparing the answers
A fund's control is not the tree; it is running the tree for both regimes and comparing the answers with each other and with the file. Two 2025 decisions of the Abu Dhabi Global Market's regulator turned on exactly that comparison. In one, an account holder was an investment entity on its CRS form and a passive NFE on its FATCA form, and the regulator found the institution had failed to validate the self-certification and confirm its reasonableness (ADGM FSRA, OAC notice, 13 June 2025). In the other, a client was a passive NFE for CRS and a sponsored FFI on its W-8BEN-E, with nothing on file to reconcile them (ADGM FSRA, ADS decision, 3 October 2025).
In both, each form could be read as complete on its own. The failure was the missing comparison: nobody had set the two classifications side by side, or against the management agreement that would have settled which was right. A field-by-field reading of what each form must contain is in the self-certification form, annotated.
A classification changes only with three signatures
In FATCA/CRS Self-Certification the agents propose a classification and cite the evidence; three people decide. The analyst prepares the reclassification with its reason and what it changes in FATCA and CRS reporting, the tax operations checker checks it, and the head of fund tax signs it. Nobody approves their own work, and the agents never change a classification.
Reclassifications with the reason, the reporting impact and three signatures
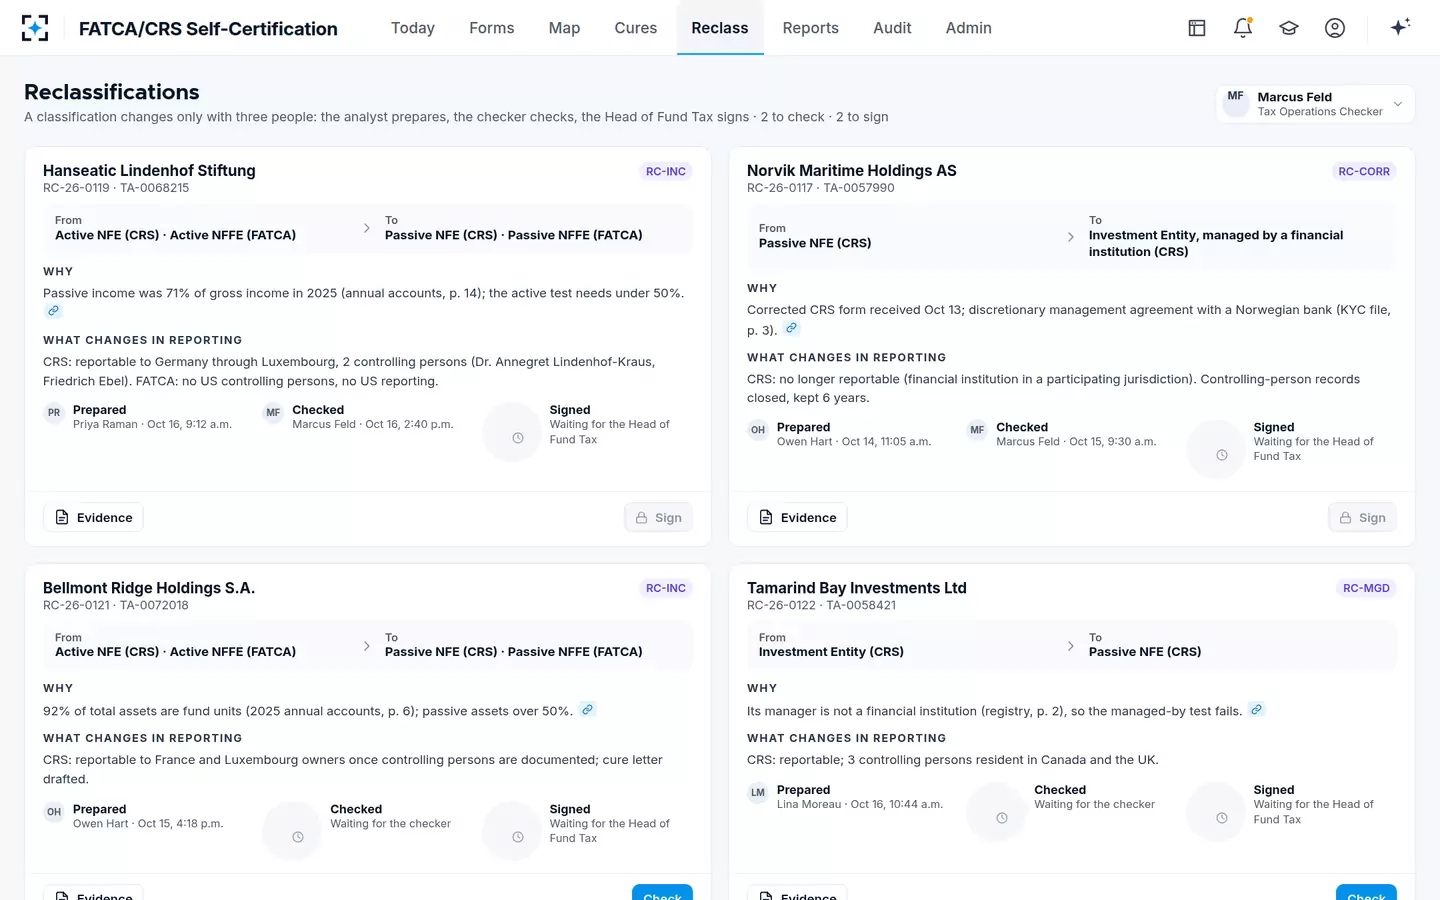
The design target is that no conflicting classification stays on file: every entity investor's CRS form, W-8BEN-E and KYC file agree, or the disagreement is in a letter to the investor with a clock running. To see the tree applied to your own entity investors, start from FATCA/CRS Self-Certification.
Questions people ask
Is cash a passive asset for the active NFE test?
Generally yes. HMRC's manual says cash is usually regarded as an asset held for the production of passive income even in a non-interest-bearing account. A company holding the proceeds of a business sale can fail the asset half of the test the day the sale completes.
Can an entity be active under CRS and passive under FATCA?
It can certify that way without contradiction. The IRS lets an NFFE that may qualify as active still check the passive NFFE box and disclose its substantial US owners or certify it has none. The reverse pairing, or a financial-institution status on one form and an NFE status on the other, needs an explanation.
What is a direct reporting NFFE?
A FATCA-only category: a passive NFFE that reports information about its substantial US owners directly to the IRS instead of through the withholding agent. It must register and obtain a GIIN, so a fund documenting one should find it on the IRS FFI list.
How long can a start-up claim active NFE status?
Only during the first 24 months after the entity was formed, and only if it is investing to operate a business other than that of a financial institution. When the 24 months end, the classification changes and the fund needs a new self-certification.
Who decides the classification, the investor or the fund?
The investor certifies it; the fund must test it. HMRC allows an institution to determine that an entity is active or a financial institution from information it holds or that is publicly available, but to decide whether a controlling person is reportable it may rely only on a self-certification.
Is a fund of funds an active NFE?
No. An entity that functions or holds itself out as a collective investment vehicle, private equity fund, hedge fund or similar vehicle is generally an investment entity, which makes it a financial institution rather than an NFE of either kind. A feeder or fund-of-funds investor that ticks "active NFE" has picked the wrong branch of the tree.