A premium finance notice of intent to cancel insurance is the letter a premium finance company must mail to an insured who has missed a loan payment, warning that the company will cancel the insurance it financed unless the payment arrives within the time the notice states. It is the first of two notices. Only after the waiting period has run can the finance company send the insurer a request for cancellation, and only then does the insurer cancel. The waiting period is set by state law: at least 10 days in Florida, no earlier than the 10th day after mailing in Texas, and in New York at least 10 days plus at least three days for mailing. The insurer's part is easy to underestimate: in Texas it must notify mortgagees and other third parties within two business days of receiving the request, and in every state it must return the unearned premium on a deadline. Botminds' Insurance Billing Exception Management reads each finance company notice, matches it to the policy, counts the days since the notice of intent, and holds any request that came too early for a premium finance coordinator to decide.
The examples use the solution's sample data: a fictional carrier, Kestrel Point Mutual, and fictional finance companies and insureds. The statutes are quoted from the states' official sites.
What is a premium finance notice of intent to cancel?
It is the finance company's warning to its own borrower. The premium finance agreement usually contains a power of attorney that lets the finance company cancel the policy for the insured if the loan goes into default. Because that cancellation ends someone's insurance without the insured asking, the states require the finance company to warn first, give a cure period, and only then act.
The notice goes to the insured, not the insurer, so the insurer usually never sees it. What reaches the insurer is the second document, the request for cancellation, sometimes with a copy of the notice of intent and sometimes only with its date. That is the asymmetry at the heart of the work: the insurer acts on a request whose lawfulness depends on a letter it may never have read.
The rule in plain words, sentence by sentence
Florida's section is the most detailed of the three and shows every part of the process, so it is the one to read closely. Each row below takes one provision of the statute, says it in plain words and names who has to act.
Florida's premium finance cancellation rule, Fla. Stat. §627.848, in plain words
| The statute says | In plain words | Who acts |
|---|---|---|
| "Not less than 10 days' written notice shall be mailed to each insured shown on the premium finance agreement of the intent of the premium finance company to cancel" | Every insured on the agreement gets a written warning at least ten days before the finance company can act. Paying the missed installment within those ten days stops it. | Finance company |
| "the premium finance company shall mail to the insurer a request for cancellation, specifying the effective date of cancellation and the unpaid premium balance due under the finance contract" | After the ten days, the request goes to the insurer with a date and the loan balance; a copy goes to the insured. | Finance company |
| the policy "shall be canceled as of the date specified in the cancellation notice ... whether or not the premium finance company has complied with the notice requirement" | The insurer cancels on the date given, even if the warning was short. | Insurer |
| restrictions requiring notice to "a governmental agency, the insurance carrier, a mortgagee, an individual" still apply; the insurer "shall determine and calculate the effective date of cancellation from the day it receives the copy" | Any notice a mortgagee or agency is owed still has to be given, by the insurer, and the effective date allows for it. | Insurer |
| the insurer returns the unpaid loan balance to the finance company within 30 days of the cancellation date (the order of payees is worked through in the unearned premium refund guide) | The refund goes to the finance company up to the loan balance, and the rest to the agent or insured, within 30 days. | Insurer |
| "the insured shall have a cause of action against the premium finance company for damages caused by such failure to provide notice" | If the warning was short, the insured's claim is against the finance company. | Insured |
| "The commission shall adopt a standard cancellation notice for use by premium finance companies" | Florida standardises the notice by rule, down to its colour. | Regulator |
The third row is the one that surprises people, and it gets a section of its own below. The fourth is the one billing teams miss: a financed homeowners policy with a mortgagee cannot simply be cancelled on the finance company's date if the mortgagee is owed notice first.
The premium finance cancellation notice requirement in Texas and New York
Texas and New York set the same basic sequence with different details, and the details are where a request becomes too early. In Texas, the finance company "must mail to the insured a written notice that the company will cancel the insurance contract because of the insured's default in payment unless the default is cured at or before the time stated in the notice. The stated time may not be earlier than the 10th day after the date the notice is mailed", and must also mail a copy to the agent or broker named in the agreement (Tex. Ins. Code §651.161).
The same request, read under Florida's rule and New York's
Florida §627.848: "Not less than 10 days' written notice" to each insured on the agreement.
New York Banking Law §576: "Not less than ten days written notice" to the insured's last known address, "and that at least three days for mailing such notice is added to the ten day notice."
Florida §627.848: Not required by the notice-of-intent provision.
New York Banking Law §576: "A copy of the notice of intent to cancel shall also be mailed to the insurance agent or broker."
Florida §627.848: The insured shown on the agreement; the request's copy goes to the last known address on the agreement.
New York Banking Law §576: The finance agency's "records ... shall be presumptive evidence as to the correctness of such address."
Florida §627.848: States the effective date and the unpaid balance.
New York Banking Law §576: A notice of cancellation "stating when thereafter the policy shall be cancelled"; a copy to the insured.
Florida §627.848: The policy cancels anyway; the insured may sue the finance company.
New York Banking Law §576: The ten days and the three mailing days are part of the agency's power to cancel.
Florida §627.848: Within 30 days of the cancellation date.
New York Banking Law §576: Within a reasonable time, and no later than 60 days after the cancellation takes effect.
New York's three mailing days are the detail most often lost. A finance agency that mails its notice of intent on the 1st cannot act until the 14th: ten days plus three. A carrier that loads one notice period for every state will apply ten days to New York requests and act three days early, or thirteen to Florida and Texas requests and hold lawful ones. The sample carrier's settings apply the stricter ten-plus-three test to every request, a conservative choice that holds some lawful Florida and Texas requests for review.
Request for cancellation: what the premium finance company sends the insurer
A request for cancellation, called a notice of cancellation in Texas and New York, is the finance company's instruction to the insurer to cancel under its power of attorney. In Texas, after the time stated in the notice of intent, the company "may cancel each applicable insurance contract by mailing a notice of cancellation to the insurer", and each contract "shall be canceled as if the insured had canceled the contract" (Tex. Ins. Code §651.161(d)). It must also mail a notice of cancellation to the insured and to the agent or broker.
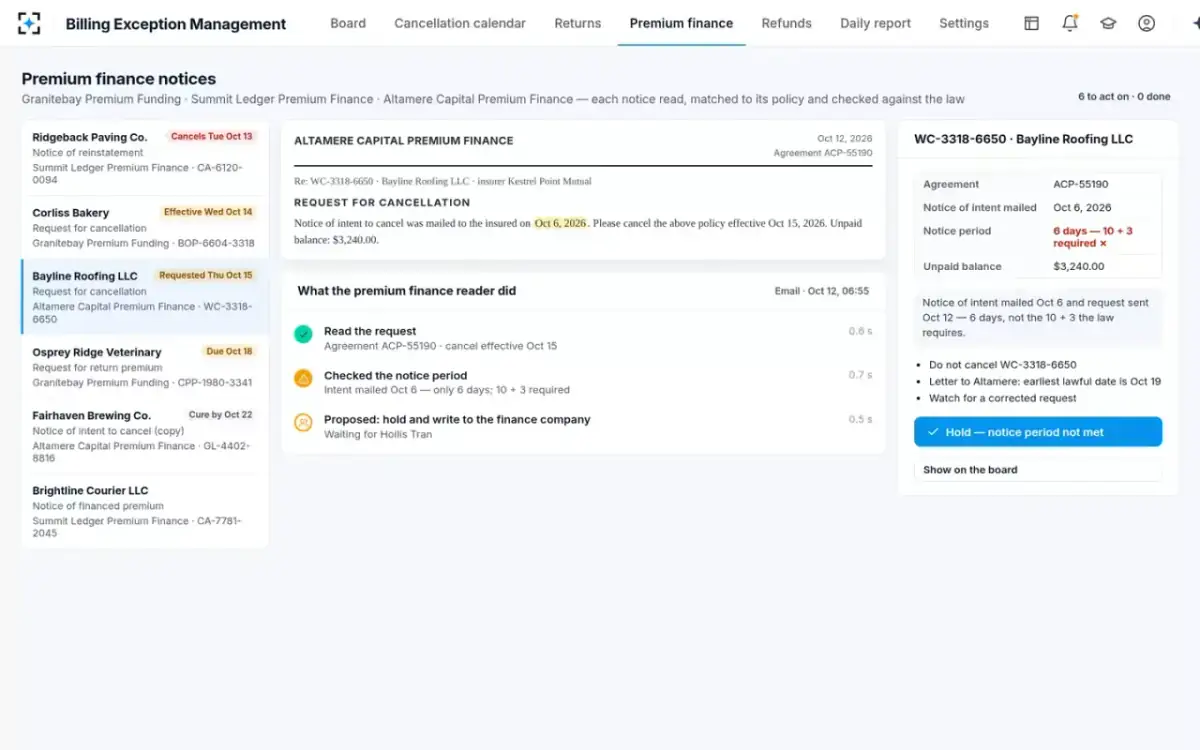
A good request carries five things: the agreement number, the policy, the date the notice of intent was mailed, the effective date of cancellation the finance company wants, and the unpaid balance. Requests from different finance companies carry them in different places, and some leave out the date of the notice of intent, which is the one fact the insurer needs to check the waiting period. A request without that date cannot be checked and should be treated as one that came too early until the finance company supplies it.
A request held in Insurance Billing Exception Management: six days' notice where ten plus three are required
Florida cancels the policy even when the notice was short
In Florida, the insurer does not have to check the notice of intent before cancelling, and if it cancels on a short notice the policy is still cancelled. That is the plain meaning of the statute's third provision, and it is the one place where Florida's rule is looser for the insurer than New York's.
Upon receipt of a copy of the cancellation notice by the insurer or insurers, the insurance contract shall be canceled as of the date specified in the cancellation notice with the same force and effect as if the notice of cancellation had been submitted by the insured herself or himself, whether or not the premium finance company has complied with the notice requirement of this subsection.
Fla. Stat. §627.848(1)(c)
The policy reason is clear: the insurer is not a party to the loan and cannot know whether the insured was warned. The consequence is that the insured's protection against a short notice is a lawsuit against the finance company, under subsection (1)(f), not an uncancelled policy. An insurer may still choose to hold an early request and ask the finance company to confirm its dates, which costs a few days and protects a customer from a gap in coverage. Whether to hold is a policy decision for compliance, not something a billing system should decide by default.
How premium finance company cancellation processing works at the insurer, day by day
At the insurer, a request for cancellation becomes four tasks with three clocks: check the waiting period, give the third-party notices, cancel on the right date, and return the unearned premium. The timeline compares two sample requests that arrived the same week, one lawful and one too early.
Two sample requests: seventeen days of notice, and six
- Notice of intent running10 + 3 d
- Past the waiting period4 d
- Request in; cancel Oct 145 d
- Notice running when the request came6 d
- Still owed under 10 + 37 d
On the lawful request, the work after the check is arithmetic and notices. The premium finance reader worked out the unearned premium on Corliss Bakery's business owners policy, 182 of 365 days of an annual $4,780.00 premium, or $2,383.45, and split it: $1,106.40 to the finance company, which was its unpaid balance, and $1,277.05 to the insured. The due date of that refund depends on the policy's state, 30 days in Florida and up to 60 in New York, which is why the clock comes from the state table rather than a single setting. On the early request, the work is a letter: the finance company is told the earliest lawful date and the request is watched for a corrected version.
A third kind of notice reverses the process. When an insured catches up with the finance company after a request has gone in, the company may send a notice of reinstatement withdrawing it. On the sample Monday, one arrived by email at 07:58 for a commercial auto policy whose cancellation was on file for 12:01 a.m. the next day. The billing team had a day to rescind it, and how to reinstate a policy cancelled for nonpayment covers what changes when that day is missed.
Is there a premium finance notice of intent to cancel form or template?
In Florida, yes: the statute directs the Financial Services Commission to "adopt a standard cancellation notice for use by premium finance companies in canceling insurance policies" and to "specify the color of the notice so as to promote usability and standardization" (Fla. Stat. §627.848(3)). In Texas and New York the statutes set what the notices must do rather than prescribe one form, so each finance company drafts its own within those rules.
For an insurer, the useful template is not the finance company's letter but the list of facts the insurer needs out of it. The checklist below is that list, and a request missing any item is the one to call about before acting.
What an insurer needs from every premium finance cancellation request
- The agreement number, and the policy it covers
Match both to the notice of the agreement you received; a request for a policy you never saw financed is a red flag.
- The date the notice of intent was mailed
Without it the waiting period cannot be checked. Count ten days in Florida and Texas, ten plus three in New York.
- The effective date requested
It must fall after the waiting period, and leave room for any notice a mortgagee or agency is owed.
- The unpaid balance under the agreement
This caps the finance company's share of the unearned premium.
- The finance company's license
A request is an exercise of a power of attorney; a licensed company is the start of a valid one.
- Third parties on the policy
Mortgagees, loss payees and agencies owed notice; Texas gives the insurer two business days.
- Money already received
A check in unapplied cash or a finance company remittance may already have cured the default.
What Insurance Billing Exception Management checks on every request
In the solution, the premium finance reader reads each notice as it arrives, by email or mail scan, matches the agreement to the policy, and runs the checklist: the notice period against the carrier's setting, the unpaid balance, the third parties on the policy and the money on the board. A lawful request becomes a proposal to cancel on the requested date and split the refund; an early one becomes a proposal to hold and write to the finance company with the earliest lawful date. The reader never cancels or reinstates a policy; the premium finance coordinator confirms each proposal, and the solution's audit trail keeps who did.
The last item on the checklist is why the premium finance lane sits on the same board as unapplied cash. A finance company's withdrawal and an insured's check can both cure the same default, and the cancellation clock keeper compares every pending cancellation with both each morning. The refund that ends a lawful cancellation is followed through in the premium finance unearned premium refund, and the go-live work for the whole lane in insurance premium finance software: an eight-week plan.
Questions people ask
Can a premium finance company cancel my insurance?
Yes, if your finance agreement gives it a power of attorney and you default, but only after it mails you a notice of intent to cancel and the waiting period runs: at least 10 days in Florida and Texas, and in New York 10 days plus at least three days for mailing. Paying the missed installment within that time stops the cancellation.
How many days' notice must a premium finance company give before cancelling?
In Florida, at least 10 days' written notice; in Texas, a cure time no earlier than the 10th day after the notice is mailed; in New York, at least 10 days with at least three more added for mailing. Other states set their own periods.
What happens if I pay after the notice of intent but before the policy cancels?
The finance company can withdraw its request, often with a notice of reinstatement to the insurer, and the insurer should rescind any cancellation still on file. Ask the finance company to confirm the withdrawal to the insurer in writing, and check with the insurer that the policy shows no gap.
Does the insurer notify my mortgage company when a finance company cancels?
Yes, where the mortgagee is owed notice. Texas requires the insurer to give those notices on or before the second business day after it receives the finance company's notice of cancellation, and Florida requires the insurer to give them and to set the effective date with them in mind.
Is a premium finance notice of intent to cancel the same as a cancellation notice from the insurer?
No. The notice of intent comes from the finance company and warns that it will cancel unless you pay the loan. A notice of cancellation for nonpayment from the insurer is a separate document under different rules, used when you owe the insurer directly, as on an installment plan with the insurer.