An asset location strategy decides which of a household's accounts holds each asset, so that the household as a whole matches its model allocation while paying less tax. The classic finding is that heavily taxed assets, such as taxable bonds, belong in tax-deferred accounts and equity in taxable accounts, with exceptions for tax-inefficient funds and municipal bonds. For a firm that runs model portfolios, the hard part is that the model is usually built and rebalanced one account at a time, so each account gets the same 60/40 and the location benefit is never captured. Botminds' Model Portfolio Rebalancing reads every account in a household, carries each model change into the account where it costs least, and keeps a reason for every account that differs from the model.
The research on this page is peer-reviewed or published by the National Bureau of Economic Research, linked where it is used. The household below is illustrative arithmetic, not a client's; the screens show the solution's fictional sample firm, Quillfield Private Wealth. Nothing here is tax advice to any client.
One household on a 60/40 model: copied into every account, or located
Copied · taxable $1.0M
- Equity · 60%
- Bonds · 40%
Copied · traditional IRA $0.7M
- Equity · 60%
- Bonds · 40%
Copied · Roth IRA $0.3M
- Equity · 60%
- Bonds · 40%
Located · taxable $1.0M
- Equity · 90%
- Bonds · 10%
Located · traditional IRA $0.7M
- Bonds · 100%
Located · Roth IRA $0.3M
- Equity · 100%
Asset location vs asset allocation: what each one decides
Asset allocation decides how much of a household's wealth goes into each asset class; asset location decides which account each holding sits in. The first is a risk decision; the second is a tax decision that, done well, leaves the risk unchanged. Bergstresser and Poterba put the difference simply: households with money in both kinds of account "must decide where to hold them", in addition to "deciding which assets to hold" (NBER Working Paper 9268, later published in the Journal of Public Economics).
The two get confused because a model portfolio collapses them. A 60/40 model applied to every account produces a 60/40 household, which is the right allocation and an arbitrary location. Shoven and Sialm, who derived optimal locations for a saver, concluded that "Locating assets optimally can significantly improve the risk-adjusted performance of retirement savings" (NBER Working Paper 7192). The model committee owns the allocation. Somebody has to own the location.
What the research says goes where
The general answer is taxable bonds in the tax-deferred account and equity in the taxable account. Dammon, Spatt and Zhang modelled a lifetime of saving across both account types and wrote: "We show a strong preference for holding taxable bonds in the tax‐deferred account and equity in the taxable account, reflecting the higher tax burden on taxable bonds relative to equity" (Journal of Finance, 2004). For most investors, they add, the policy holds up when tax-exempt bonds and liquidity shocks are introduced.
The tax code supplies the reason. Qualified dividends are "subject to the same 0%, 15%, or 20% maximum tax rate that applies to net capital gain", and unrealized gains on equity are not taxed until sale (IRS Publication 550). Bond interest gets neither treatment. Inside a traditional IRA, "Tax on your traditional IRA is generally deferred until you take a distribution", and in a Roth IRA "qualified distributions are tax-free" (IRS Publication 550; IRS, Roth IRAs). A bond's interest is taxed every year it sits in a taxable account; in the IRA it is not.
Where each asset tends to belong, and the tax reason
| Asset | Taxable account | Traditional IRA | Roth IRA |
|---|---|---|---|
| Taxable bonds | Interest taxed each year | Usual home: tax deferred until withdrawal | Possible, but uses tax-free room on a low-return asset |
| Broad equity, held long | Usual home: gains deferred until sale, qualified dividends at capital gain rates | Gives up those preferential rates | Strong candidate: growth and qualified withdrawals tax-free |
| Tax-inefficient equity funds | Distributions taxed each year | Often better here | Often better here |
| Municipal bonds | Usual home: interest generally not taxable | Wastes the exemption | Wastes the exemption |
| Cash for withdrawals | Where the withdrawals are paid | Only if the withdrawal comes from the IRA | Rarely |
The exception: tax-inefficient funds and municipal bonds
The rule of thumb reverses when the equity is held through tax-inefficient funds or the bonds can be municipal. Poterba, Shoven and Sialm tested two strategies on actual returns from 1962 to 1998 and found that high-income savers "would have accumulated a larger stock of wealth if they had held their equity mutual fund in their tax-deferred account" (NBER Working Paper 7991). Their explanation has two parts: "many equity mutual funds impose substantial tax burdens on their investors", and taxable investors can hold fixed income as tax-exempt bonds.
Municipal bond interest is the second half of that. Publication 550: "Interest on a bond used to finance government operations generally is not taxable if the bond is issued by a state, the District of Columbia, a U.S. territory, or any of their political subdivisions." A household in a high bracket can hold its bond allocation in the taxable account as municipals and use the IRA for something else. The asset location strategy therefore depends on the model's actual instruments, not its asset classes.
How much households leave on the table
Many households hold the opposite of the textbook pattern. Using the Survey of Consumer Finances, Bergstresser and Poterba found that "Many households hold equities in their tax-deferred accounts but not in their taxable accounts, while also holding taxable bonds in their taxable accounts", and that "Most of these households could reduce their taxes by relocating heavily-taxed fixed income assets to their tax-deferred account" (NBER WP 9268).
Households with a location choice, and how small the fix often is
45%
of US households had some assets in a tax-deferred account in 1998
10M+
households held at least $25,000 in both a taxable and a tax-deferred account
<$10K
shift that would make the portfolio tax-efficient for nearly three quarters of the inefficient ones
The last figure is the encouraging one. For most inefficient households the fix was a shift of less than $10,000, a matter of where the next purchases go rather than a wholesale restructuring. That is exactly the kind of decision a rebalancer makes every time a model changes, and exactly the kind it makes badly when it treats each account as if the others did not exist.
Should bonds be in a taxable account or a Roth IRA?
Usually neither: the research points taxable bonds to the traditional, tax-deferred account. The Roth question is subtler. Because qualified Roth distributions are tax-free, the Roth's tax-free room is worth most on the assets expected to grow most, which in a stock-and-bond model is equity. Putting bonds there is not wrong in tax terms, since the interest escapes tax either way, but it spends the most valuable space on the lowest-returning asset.
Taxable bonds in the taxable account are the costly case, interest taxed every year at the client's rate, unless the bonds are municipal. A model that holds Treasury notes, as the sample firm's balanced model now does, raises a further detail. "Interest income from Treasury bills, notes, and bonds is subject to federal income tax but is exempt from all state and local income taxes," in Publication 550's words (IRS Publication 550), which shifts the comparison for a client in a high-tax state. That is a fact the firm's tax policy should state, not one the rebalancer should infer.
Location changes the risk you think you hold
A located household is 60/40 by market value, but not necessarily 60/40 in what the client will actually keep. A dollar in a traditional IRA carries a future tax bill; a dollar in a Roth does not. Dammon, Spatt and Zhang found that "the proportion of total wealth allocated to equity is inversely related to the fraction of total wealth in tax‐deferred accounts" (Journal of Finance, 2004): location and allocation interact, so the committee and whoever owns location need to agree on whether the model's weights are measured before or after the tax each account carries.
Most model programs measure before tax, on market value, because that is what statements show and what clients understand. That is a defensible choice. What is not defensible is the drift that comes from location going unmanaged: when every account is rebalanced to 60/40 on its own, each one sells winners and realizes gains in the taxable account that a household-level view would have rebalanced inside the IRA for free.
Rebalancing a located household without undoing it
Rebalancing a located household means trading where it is cheapest while restoring the household total. If equity has rallied, the household is overweight equity; the obvious trade sells equity in the taxable account and realizes gains. The located trade does the selling inside the IRA or Roth instead: sell equity and buy bonds there, where sales are not taxed, and leave the taxable account alone. The household returns to 60/40 and nothing is realized.
The same rebalance, run account by account or across the household
Account by account: Every account sells equity to get back to 60/40, the taxable one included.
Across the household: The IRA or Roth sells equity and buys bonds; the taxable account does not trade.
Account by account: Gains in the taxable account.
Across the household: None, if the tax-deferred accounts are large enough to absorb the trade.
Account by account: Invested 60/40.
Across the household: Invested in whatever the household is short of, equity first if the location calls for it.
Account by account: Checked against that account only.
Across the household: Checked against IRA and Roth purchases too: they can make the sale a wash sale.
The last row of that comparison is the trap. Trading inside the IRA is free of tax, which is why a location-aware rebalancer prefers it, and an IRA purchase within 30 days of a taxable loss sale disallows the loss for good under Rev. Rul. 2008-5. A household rebalancer that does its buying in the IRA must check those buys against the taxable account's harvests. The household wash-sale test sets out that check line by line.
What will examiners ask about allocation across account types?
They will ask why an investment sits in the account it does. In its fiscal 2027 examination priorities, published in October 2026, the SEC's Division of Examinations names among its areas of interest "allocation of investments where an investor has more than one type of account" (SEC Division of Examinations, FY2027 priorities). The passage sits in the section on retail sales practices and dual registrants, and its concern is conflicts of interest, not tax efficiency.
The evidence that answers both concerns is the same: for each account, what the household-level plan put there and why. A firm whose location decisions live in an adviser's head, or nowhere, cannot show an examiner that the choice served the client rather than the fee schedule. A firm that writes the reason beside each account can.
Six decisions an asset location policy for model portfolios should settle
- Who owns location
The model committee sets the allocation; name the person or group that sets the location rules and approves exceptions.
- Which accounts form a household
Spouses, joint accounts, IRAs and Roths at the firm, and whether held-away accounts are counted.
- Pre-tax or after-tax weights
Whether the household is measured against the model on market value, as most programs do, or adjusted for embedded tax.
- The location order
Which assets go first to tax-deferred and tax-free space, using the model's actual funds, including tax-inefficient funds and municipal bonds.
- Where rebalancing trades go
Tax-deferred accounts first where they can absorb the trade, with a check of IRA purchases against taxable loss sales.
- What the client sees
Account statements that differ from the model by design, explained at household level.
How Model Portfolio Rebalancing places trades by account
Botminds' Model Portfolio Rebalancing works at the household level from the start. Positions, lots and cash come from portfolio accounting each morning; outside IRAs and spouse accounts come from the custodians' held-away feed. When the committee changes a model, the Rebalance Planner proposes trades for every account in the model and groups them by why each must differ, while the Tax agent chooses lots and checks every sale against the household's purchases. In the sample firm, tax logic is skipped for IRAs and tax-exempt trusts, because their sales have no tax effect, but their purchases are still read for the wash-sale check.
One model change in Model Portfolio Rebalancing, grouped by why each account must differ
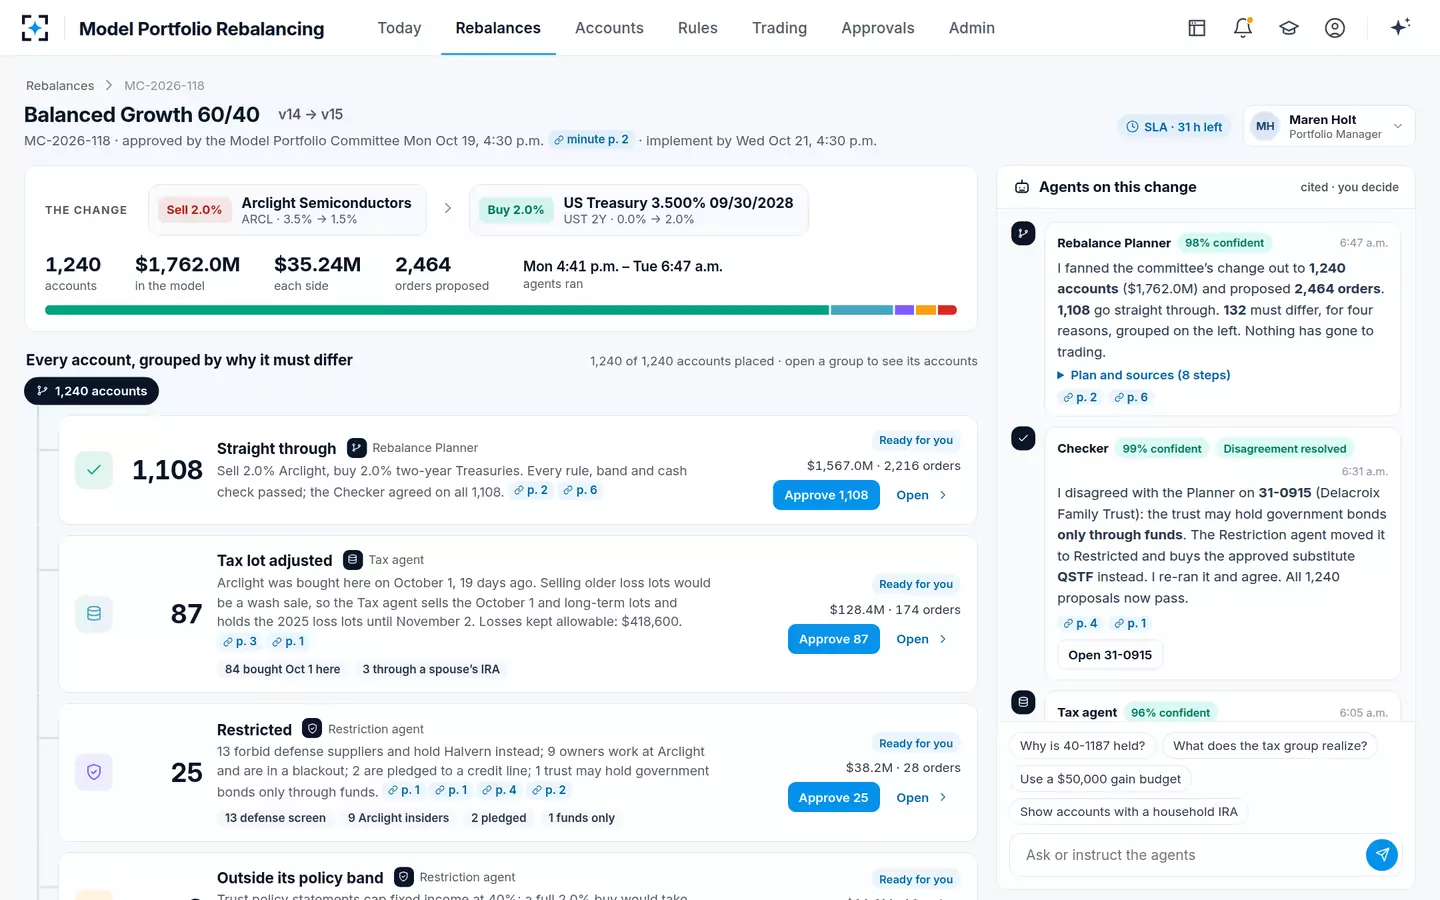
What the sample shows is the mechanism, not a measured location benefit: the solution does not claim a tax saving for any real household. The useful test for a firm is to run one past model change through it and compare, household by household, what was realized against what a located trade would have realized. What one model change costs the client sets out that comparison by account type.
Questions people ask
What is the difference between asset location and asset allocation?
Allocation is how much of the household is in each asset class; location is which account holds each asset. A household can have the right 60/40 allocation and a poor location, for example taxable bonds in the taxable account and equity in the IRA, which Bergstresser and Poterba found was common.
Should bonds be held in a taxable account?
Taxable bonds generally belong in a tax-deferred account, per Dammon, Spatt and Zhang's 2004 study, because their interest is taxed each year. Municipal bonds are the exception: their interest is generally not taxable, so they belong in the taxable account if they are held at all.
What should go in a Roth IRA?
Assets with the highest expected growth, usually equity, because qualified Roth distributions are tax-free and the room is limited. That is our reading of the tax treatment the IRS describes, not a rule; the right choice depends on the household's horizon and funds.
Does asset location work with a model portfolio?
Yes, if the model is applied to the household rather than copied into each account. Each account then differs from the model by design, so the program needs a written reason for each, and a rebalancer that restores the household total rather than each account's.
Is asset location worth it for small accounts?
It matters only for households with meaningful money in both taxable and tax-advantaged accounts. Bergstresser and Poterba counted more than ten million households in 1998 with at least $25,000 in each kind, and found that for most inefficient ones a shift of under $10,000 would fix it.
Can rebalancing in an IRA cause a wash sale?
Yes. An IRA purchase of substantially identical stock within 30 days of a loss sale in a taxable account is a wash sale, and under Rev. Rul. 2008-5 the IRA's basis is not increased, so the loss is lost rather than deferred.