A lender's procedure for loan application fraud involving a falsified pay stub or bank statement has six parts: hold the file without a decision, preserve the document exactly as received, have a fraud analyst decide whether the signs amount to a finding, decide the credit on what is proved or decline with a specific reason a second person co-signs, assess suspicious activity reporting on its own clock, and charge off any loan already funded within the period the classification rules allow. The law behind it is severe (a false statement to a federally insured lender carries up to $1,000,000 and 30 years under 18 U.S.C. § 1014), which is exactly why the procedure has to be careful: a tamper signal establishes that a figure is inconsistent, not that anyone meant to deceive. Botminds' Income and Document Verification raises each signal with the figures behind it, holds the file, and leaves every consequence to a named person.
The files, applicants and figures in the examples are fictional sample data from the solution; the statutes and rules are real and linked where they appear.
One sample lender's verification desk since the agents took over the checks
1,148
files verified
23
altered documents confirmed by a fraud analyst
14min
median from a complete file to a decision, against 2.6 days by hand
What the law makes of a falsified income document
Two federal statutes reach it, and both turn on knowledge. Section 1014 covers whoever "knowingly makes any false statement or report ... for the purpose of influencing in any way the action of" a listed federal or federally insured institution "upon any application ... loan, or insurance agreement", with a maximum of a $1,000,000 fine, 30 years, or both. Bank fraud under 18 U.S.C. § 1344 covers whoever "knowingly executes, or attempts to execute, a scheme or artifice" to defraud a financial institution or obtain its money by false pretences, with the same ceiling. State fraud and forgery laws apply alongside them.
The elements of § 1014, and what a document check can establish about each
| Element | What it means | What a tamper check establishes |
|---|---|---|
| Knowingly | The person knew the statement was false | Nothing: arithmetic cannot tell a forgery from a payroll correction the applicant never read |
| False statement or report | The document or assertion is untrue | A great deal: a net figure that is not gross less deductions is wrong as arithmetic |
| For the purpose of influencing | It was made to move a credit decision | Partly: a stub sent with an application was sent to support it |
| The institution | A listed federal or federally insured lender | Nothing: it is a fact about the lender |
For a lender the statutes matter less as a threat to the applicant than as a discipline on its own staff. An accusation of a federal felony should not rest on a font. The evidential standard for a decline is the lender's own and lower than a criminal one, and nobody writing in a file, a letter or a call note should confuse the two.
Why a tamper signal holds the file instead of declining it
Because every integrity test checks consistency, and inconsistency has innocent causes. Gross to net, statutory tax rates, year-to-date against the pay calendar, balances carried from page to page and a re-save by an editing tool each test whether figures agree. A payroll correction, a retroactive adjustment, a reprinted stub, a partly scanned page or a photographed document can each fail one of them.
So a signal in Income and Document Verification does one thing: it stops the file where it stands and sends it to the fraud analyst with the evidence. No decision is issued and nothing goes to the applicant until fraud decides. Clearing a signal takes a written reason a second person can read, and the fraud analyst reviews every clearance. The checks themselves and the arithmetic each runs are set out in how to identify fake pay stubs.
The path a held document takes, and who decides at each step
Agent
CheckRuns the integrity checks on every page and raises a signal naming the figure or date each sign rests on.
Never: Declines a file or calls it fraud.
Agent
HoldStops the file. No decision is issued and no communication goes to the applicant.
A person decides
Fraud analystReads every sign against the pages behind it and decides: finding, or clearance with a written reason.
A person decides
Verification analystDecides the credit on what is proved, or declines on a specific stated reason.
A person decides
Underwriting team leadCo-signs every decline for altered documents, and any decision above the analyst's limit.
A person decides
BSA teamDecides separately whether suspicious activity reporting thresholds are met, on the reporting clock.
Hold, refer or clear: what each outcome must leave behind
A held file has three futures, and each must produce its own evidence. A hold that produces nothing is the state to avoid, because it cannot be told apart from a file nobody opened.
The three outcomes for a held file
| Outcome | What it requires | What the applicant experiences | What stays on the file |
|---|---|---|---|
| Cleared | A written reason, reviewed by the fraud analyst | A short delay, then the file proceeds | The reason, the reviewer and the date, so clearances can be counted |
| Declined on the documents | A fraud finding and the team lead's co-signature | A decline with a specific principal reason | The finding, both signatures, the evidence and the reason given |
| Decided on the merits instead | Enough verified information to decide without the disputed page | An ordinary decision at verified figures | Why the disputed document was not relied on |
Clearances deserve counting for the same reason policy exceptions do. The OCC's retail lending guidance expects exceptions to be "controlled, with appropriate reporting to identify and track exceptions and appropriate analysis to determine causes, impact, and any need for corrective action" (OCC Comptroller's Handbook, Retail Lending). A rising clearance rate on one product or one analyst's files is the pattern that reporting exists to show.
One flagged file, five signs, referred with the evidence
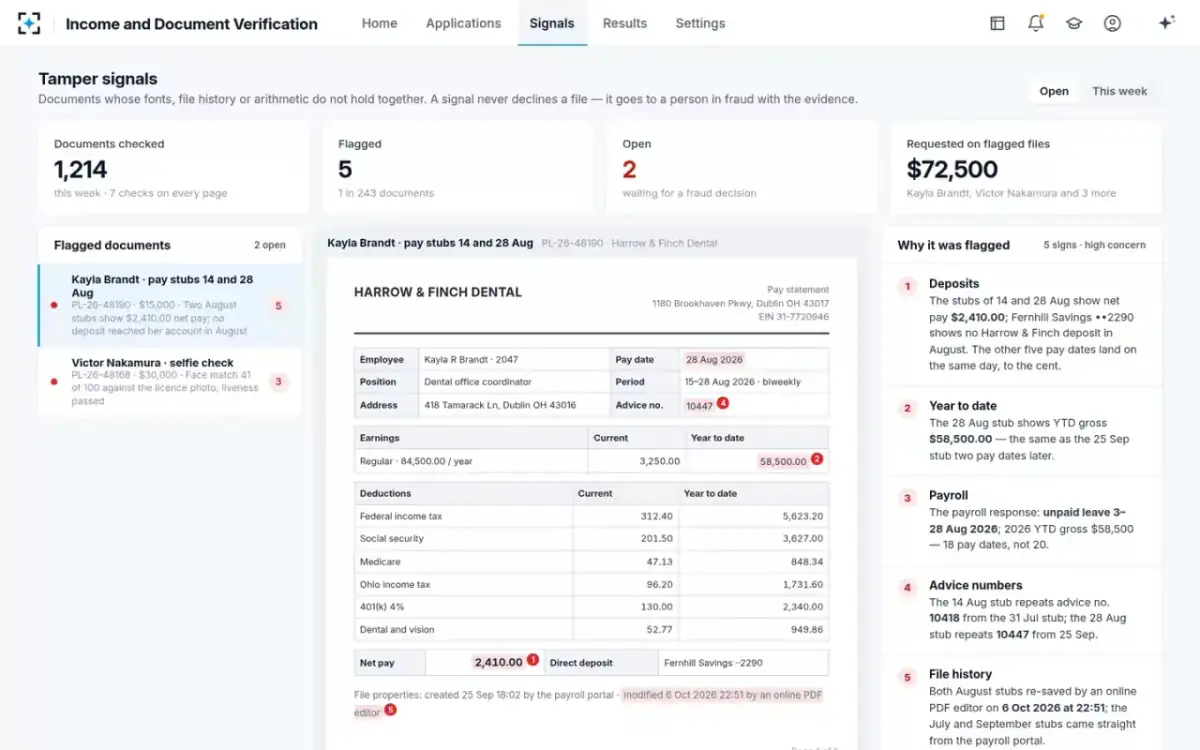
On the sample lender's second personal loan file, a biweekly net of $2,410.00 lands in savings on five of seven pay dates, but the two August stubs have no deposit behind them: $4,820.00 of pay on the stubs, $0.00 in the bank. The signal names five signs. No deposit in August; the late-August stub shows year-to-date gross of $58,500.00, the same as the September stub; the payroll response records unpaid leave for most of August; advice numbers repeat from July and September; and both August stubs were re-saved by an online PDF editor in October, late at night.
Three of the five come from outside the document, which is what makes the combination actionable where any one sign alone would be a question for the applicant. The analyst referred the file to fraud; it was held, and no notice went to the applicant until fraud decided. Why the deposit behind each stub is the hardest thing in a file to fake is covered in pay stub verification against bank deposits.
Five signs in Income and Document Verification, each naming the figure or date it rests on
How should the decline be worded?
With a specific principal reason, and never with anything that hints at a report. Regulation B requires that a statement of reasons for adverse action "must be specific and indicate the principal reason(s) for the adverse action", and that statements resting on "the creditor's internal standards or policies" are insufficient (12 CFR § 1002.9(b)(2)). A decline for a document the lender could not verify should say what could not be verified, in terms the applicant can act on if there is an innocent explanation.
The stated reason is also the only thing the applicant will ever be given, so it has to stand on its own. That is a further argument for deciding on what is proved where possible: a decline that rests on verified income below the policy minimum is easier to state, defend and explain than one that rests on a judgement that a page was altered.
When does loan application fraud require a suspicious activity report?
When the bank's thresholds under the SAR rule are met, and the decision runs on its own clock. For a national bank the OCC rule requires a report for a known or suspected federal criminal violation aggregating "$5,000 or more where a suspect can be identified", or "$25,000 or more regardless of potential suspects", filed "no later than 30 calendar days after the date of the initial detection of facts that may constitute a basis for filing a SAR"; where no suspect was identified, filing may be delayed 30 more days, and "in no case shall reporting be delayed more than 60 calendar days" (12 CFR § 21.11). The other banking agencies keep parallel rules for the institutions they supervise.
Two clocks that start the same morning and never meet
- Hold and fraud review
- Decision, co-signed
- Notice with a specific principal reason
- Initial detection
- 30 calendar days to file
- 30 more only if no suspect was identified
Confidentiality binds everyone who touches the file: "No national bank, and no director, officer, employee, or agent of a national bank, shall disclose a SAR or any information that would reveal the existence of a SAR." Management must "promptly notify its board of directors, or a committee of directors or executive officers designated by the board", and the bank must keep a copy of the SAR and the supporting documentation "for a period of five years from the date of the filing". For a verification desk the practical rule is short: front-line staff never mention a report in a call, an email or a decline letter, and the original document is preserved as supporting documentation from the moment the file is held.
What if the loan has already funded?
Then the finance function has a clock too. The OCC's retail classification guidance is that "fraudulent loans should be classified loss and charged off no later than 90 days from discovery or within the time frames specified in the classification policy, whichever is shorter." A falsified stub found in a post-funding quality review, or after an early payment default, starts that clock on discovery, alongside the SAR clock.
Post-funding discovery is also the case for checking every file before decision rather than sampling after. A lender that finds altered documents only when a loan defaults finds them after the money has gone, with a charge-off deadline and a report to file, instead of before, with a hold and a question.
Six controls a lender should be able to show for falsified documents
- The original document preserved as received
Not a printed copy or a re-saved file; re-saving overwrites the history that raised the question.
- Every sign recorded with the figure behind it
"Year-to-date gross identical on two stubs a month apart" is evidence; "tamper suspected" is not.
- No decline by a check
A signal holds the file; a named fraud analyst decides; a second person co-signs a decline for altered documents.
- Clearances with written reasons, counted
By product and by analyst, so a drift in clearing is visible.
- A specific adverse action reason that stands alone
Never resting on internal standards, never hinting at a report.
- SAR assessment on its own clock
Thresholds, 30 or 60 days, board notification and five-year retention, decided by the BSA team.
Who signs, and why the decline needs a second signature
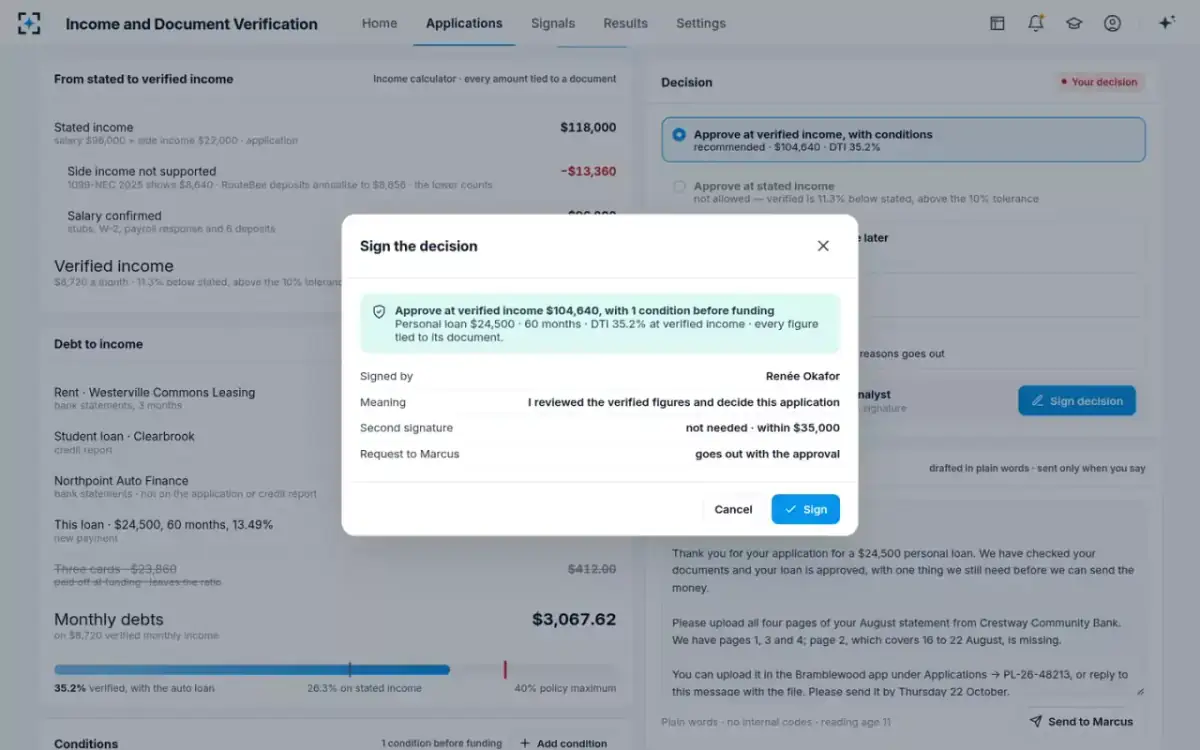
At the sample lender the underwriting team lead co-signs above the analyst's $35,000 limit and on every decline for altered documents, whatever the amount. The two conditions have different reasons. A large approval is co-signed because the money at risk is large; a decline for altered documents is co-signed because the consequence to a person is severe and the evidence is interpretive.
The error that costs most in this work is not the forgery that gets through, a credit loss the lender can size and price, but the honest applicant refused on a misread document, a harm the lender cannot see and the applicant cannot easily appeal. A second reader is the cheapest control against it and the only one that works on a judgement rather than a number. Every signature in the solution records its meaning with the signer's name, which is what lets a reviewer months later tell the person who decided from the person who processed.
Signing the decision, with the meaning recorded
Where Income and Document Verification fits
The solution's agents line up every document in a file, tie each pay stub to its deposit, check the arithmetic and file history of each page, match identity and employer across sources, and raise a signal with the evidence when something does not add up. They hold the file and route it; they never decline, call anything fraud or contact the applicant. Approval limits, the co-signature rule, how tamper signals are handled and the time to answer a request are settings the lender owns. How often the checks flag documents that turn out to be genuine is measured in automated income verification.
What changes for a fraud or verification leader is the starting point and the evidence. Every held file arrives with its signs, the figures behind them and the pages they came from, and every outcome, cleared, declined or decided on the merits, leaves its reason and its signatures. To see the procedure on your own files, start from Income and Document Verification.
Questions people ask
What should a lender do first when it suspects a falsified pay stub?
Hold the file without a decision and preserve the document exactly as received. Then route it to a fraud analyst with every sign and the figure behind it; nothing goes to the applicant until fraud decides.
Can a lender decline for a suspected fake document?
Yes, on a fraud finding and with a specific principal reason, as Regulation B requires. Often the cleaner route is to decide on what is proved, such as verified income from deposits and a payroll response, so the decision does not rest on the disputed page.
What are the SAR thresholds for loan application fraud?
For a national bank, $5,000 or more where a suspect can be identified and $25,000 or more regardless of suspects, filed within 30 calendar days of initial detection, or up to 60 where no suspect was identified. The other banking agencies keep parallel rules.
Can a lender tell the applicant it filed a SAR?
No. The rule prohibits the bank and its staff from disclosing a SAR or any information that would reveal its existence. The applicant receives only the credit decision and its specific reason.
What happens to a funded loan later found to be fraudulent?
The OCC's guidance is to classify it loss and charge it off no later than 90 days from discovery, or sooner if the bank's classification policy says so. The SAR assessment runs alongside on its own clock.
Why count cleared signals?
Because clearances are exceptions to a control, and the OCC expects exceptions to be tracked and analysed for causes. A rising clearance rate on one product or one analyst's files is the signal that the checks, the training or the judgement need attention.