Hot powers in a power of attorney are the powers an agent has only when the document grants them expressly, because each can change who ultimately receives the principal's property: making gifts, creating or changing rights of survivorship, creating or changing a beneficiary designation, and creating or revoking a trust, among others. Under the Uniform Power of Attorney Act as Virginia has enacted it, a general grant of banking authority, or even authority to do "all acts" the principal could do, does not carry them. For a bank, that means an agent's request to name a payable-on-death beneficiary, add a joint owner or move money into a trust cannot be processed like an address change: the desk has to find the clause, check who gains and decide within a statutory clock. Botminds' Account Maintenance Requests is account maintenance request software whose agents never accept a power of attorney for a beneficiary change without an express grant and route the request to a person when one is missing.
Statutes are quoted from the Code of Virginia and the Utah Code as published on the states' own sites in November 2026; other states' versions of the act differ in detail, and a bank should read its own. The worked case uses a fictional bank and fictional customers.
Two states' hot powers lists: the same core, a different last item
| Power the document must grant expressly | Virginia § 64.2-1622(A) | Utah § 75A-2-201(1) |
|---|---|---|
| Create, amend, revoke or terminate an inter vivos trust | Yes | Yes |
| Make a gift | Yes | Yes |
| Create or change rights of survivorship | Yes | Yes |
| Create or change a beneficiary designation | Yes | Yes |
| Delegate authority granted under the power of attorney | Yes | Yes |
| Waive the right to be a beneficiary of a joint and survivor annuity | Yes | Yes |
| Exercise fiduciary powers the principal may delegate | Yes | Yes |
| Authority over the content of electronic communications | Yes | Not on this list |
| Disclaim property or exercise a power of appointment | Not on this list | Yes |
What are hot powers in a power of attorney?
They are the acts an agent may do "only if the power of attorney expressly grants the agent the authority and exercise of the authority is not otherwise prohibited or limited by another statute, agreement, or instrument" (Va. Code § 64.2-1622(A)). Practitioners call them hot because each one can move the principal's estate plan, not just the principal's bills. A power that changes who inherits is a different kind of authority from one that pays the electric company.
The statute's second sentence about general authority is the one a bank relies on. Where a document grants authority to do "all acts that a principal could do", the agent has the general authority the act describes, subject to the hot-power list. So a broad, impressive-looking grant is not an express grant. The desk needs a clause that names the power, such as authority to create or change beneficiary designations, and it should be able to quote it on the file.
Gifts carry a Virginia wrinkle a bank should know. Where the document grants all-acts authority, the agent may make gifts "in accordance with the principal's personal history of making or joining in the making of lifetime gifts" (§ 64.2-1622(H)), and general gift authority is otherwise capped per recipient at the annual federal gift tax exclusion (§ 64.2-1638(B)). That is a rule about gifts. It does not extend to beneficiary designations, which still need the express grant.
Which maintenance requests engage a hot power?
Four common requests do: naming or changing a payable-on-death beneficiary, adding a joint owner with survivorship, retitling an account into a trust, and a large transfer from the principal's account to the agent or the agent's family. Each looks like routine maintenance or a routine transfer, and each is in law the exercise of a power the document may not contain.
The request on the form, and the hot power behind it
| Request from the agent | Hot power engaged | What the desk looks for |
|---|---|---|
| Name or change a payable-on-death beneficiary | Create or change a beneficiary designation | The express clause; who the new beneficiary is |
| Add a joint owner, or change a joint account's survivorship | Create or change rights of survivorship | The express clause; whether the new owner is the agent |
| Retitle the account to a revocable trust | Create, amend or revoke a trust; often survivorship as well | The clause, the trust document and the trustee's authority |
| Transfer to the agent or the agent's family | Make a gift | Gift authority, its limits and the principal's gift history |
| Close the account and open one in the agent's name | Make a gift, in substance | Treat as a transfer to the agent |
| Pay bills, deposit income, move money between the principal's own accounts | None: general banking authority | Ordinary acceptance of the power of attorney |
The size of what moves is often larger than the form suggests. The FDIC insures payable-on-death and other trust deposits at $250,000 per eligible beneficiary, up to five, which caps one owner's trust deposits at a bank at $1,250,000 since April 1, 2024 (FDIC, Your Insured Deposits). And in states that follow the common rule, a will does not override the designation on the account: Virginia puts payable-on-death payees beyond the reach of a will (Va. Code § 6.2-608). A wrong designation is not cured later by the principal's estate plan; it has to be challenged.
Can an agent use a hot power to benefit himself?
Only if the agent is the principal's ancestor, spouse or descendant, or the document expressly allows it. The uniform act's self-dealing limit applies even when the hot power is granted: "unless the power of attorney otherwise provides, an agent that is not an ancestor, spouse, or descendant of the principal may not exercise authority under a power of attorney to create in the agent, or in an individual to whom the agent owes a legal obligation of support, an interest in the principal's property, whether by gift, right of survivorship, beneficiary designation, disclaimer, or otherwise" (§ 64.2-1622(B)).
The same request, from two kinds of agent
Agent is an ancestor, spouse or descendant: Needs the express grant
Any other agent: nephew, friend, caregiver, professional: Needs the express grant
Agent is an ancestor, spouse or descendant: Allowed with the express grant
Any other agent: nephew, friend, caregiver, professional: Not allowed, even with the grant, unless the document says so
Agent is an ancestor, spouse or descendant: Allowed with the express grant
Any other agent: nephew, friend, caregiver, professional: Not allowed unless the document says so
Agent is an ancestor, spouse or descendant: Needs the express survivorship grant
Any other agent: nephew, friend, caregiver, professional: Not in the agent's favour unless the document says so
Agent is an ancestor, spouse or descendant: General authority, if granted
Any other agent: nephew, friend, caregiver, professional: General authority, if granted
The family exception is not a safe harbour for the bank. FinCEN's review of elder exploitation reports found that filers named adult children as the perpetrators of elder theft in nearly 40 percent of cases, and that elder theft "is likely to be underreported and can go undetected because the perpetrators are typically individuals who are trusted by the victim" (FinCEN Financial Trend Analysis, April 2024). A son with the express grant may lawfully name himself; whether this request reflects his mother's wishes is a separate question the desk should still ask.
How fast must the bank decide, and what protects it?
In Virginia, a bank presented with an acknowledged power of attorney must accept it, or request a certification, translation or opinion of counsel, within seven business days, and then accept within five business days of receiving what it asked for (§ 64.2-1618(A)). A wrongful refusal exposes the bank to a court order and the presenter's reasonable attorney fees. The same section lists the lawful grounds, and one is written for hot powers: the bank "in good faith believes that the power is not valid or that the agent does not have the authority to perform the act requested."
The clock a Virginia bank runs on an acknowledged power of attorney
7business days
to accept, or to request a certification, translation or opinion of counsel
5business days
to accept after receiving what the bank requested
6
grounds on which the bank may lawfully refuse, including a good-faith belief the agent lacks the authority
The bank's protection runs through its procedures. A person that accepts an acknowledged power of attorney in good faith, without actual knowledge that the agent is exceeding or improperly exercising the authority, may rely on it as genuine (§ 64.2-1617(B)), though that reliance does not reach a document with a forged principal's signature. The statute then tells an organisation how actual knowledge is measured: a person that "exercises commercially reasonable procedures to communicate information concerning powers of attorney among its employees" is without actual knowledge if the employee handling the transaction followed them (§ 64.2-1617(F)).
That subsection is a design requirement for the desk. If the elder protection team knows the agent is under suspicion and the maintenance specialist does not, the question in a later dispute is whether the bank's procedures should have carried that fact to the specialist. A request routed with the account's history, open protection cases and prior refusals attached is the commercially reasonable procedure, in practice.
Where the exploitation risk concentrates
A hot-power request from an agent combines the two features exploitation cases share: a trusted person and a quiet change that pays out later. Banks are where most of these cases surface: "Banks filed 72 percent of the total EFE-related BSA reports received in the review period," FinCEN found, out of 155,415 reports tied to more than $27 billion in reported suspicious activity.
The regulators name agents directly. The December 2024 interagency statement on elder financial exploitation says "Customer-facing employees may be trained to identify transactional and behavioral red flags when conducting transactions for older adults, including via powers of attorney or other agents," and that employees "may also benefit from detailed escalation processes and written procedures" (Interagency Statement, reprinted in Consumer Compliance Outlook, Fourth Issue 2024). A request to redirect a principal's estate to the agent is the clearest case for both.
The bank's identification rule points the same way on the question of whose account it is. Where an agent opens an account for a competent principal, the interagency guidance says "the 'customer' will be the named owner of the account rather than the individual with a power-of-attorney over the account" (interagency CIP guidance). The agent acts for the customer; a request that makes the agent the beneficiary turns that relationship around, and the desk should see it that way.
A sample case: an agent asks to name himself
At the fictional sample bank, a durable power of attorney dated April 2, 2024 named Gerald Fontaine agent for Mabel Fontaine, 88. He asked to name himself payable-on-death beneficiary on her savings account of $62,400. The Authority agent found general banking authority in the document and no express grant to change a beneficiary designation. That settles the request whatever his relationship to her: without the grant, no agent may make the change, and had he been a nephew or a friend, even a grant would not have let him name himself unless the document said so.
The agents find no express grant and say what they may not decide
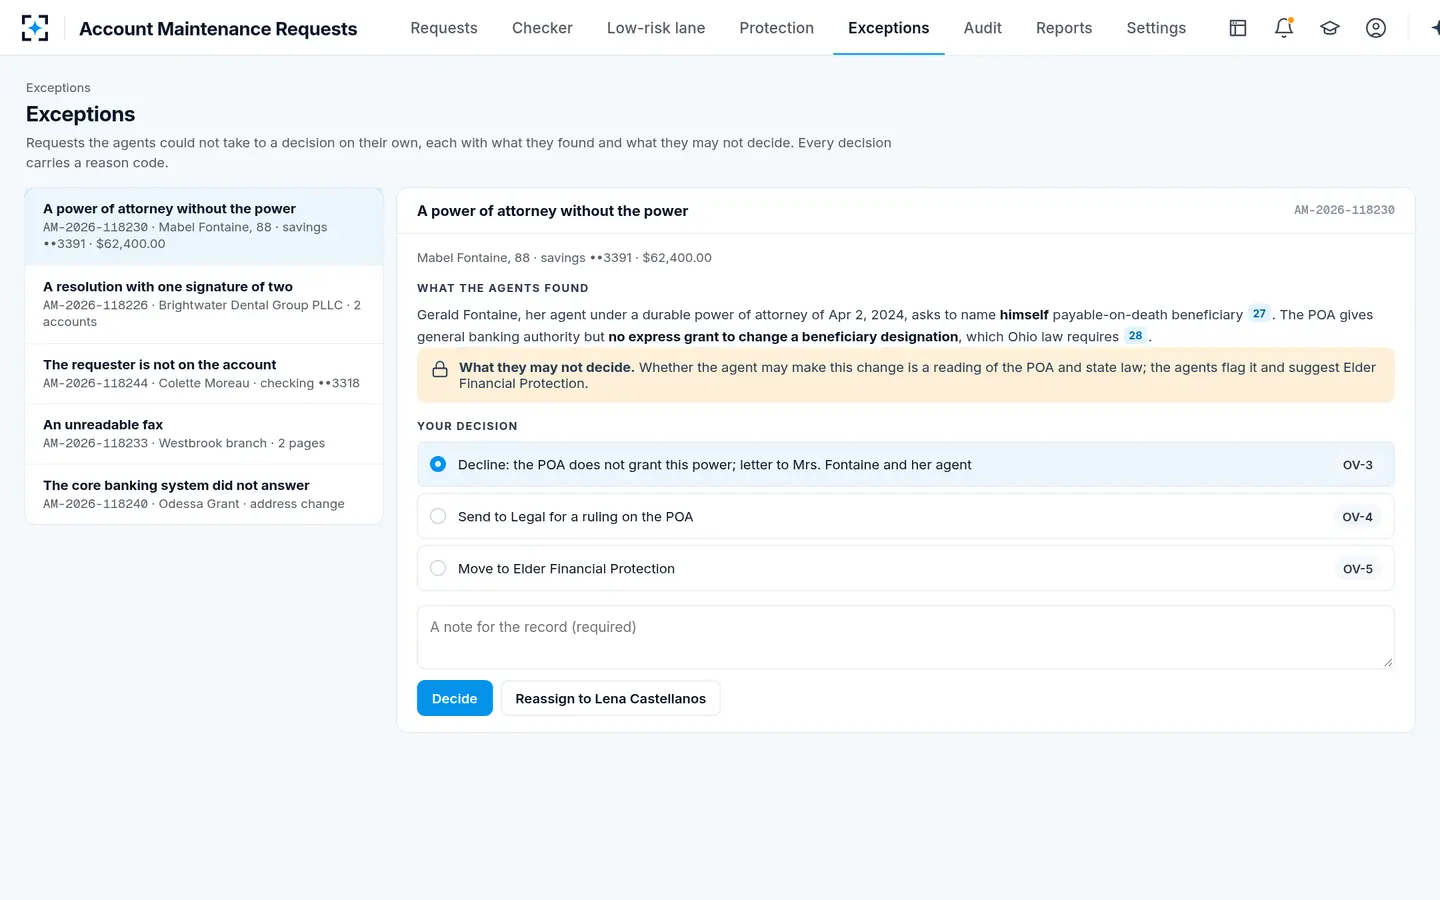
The specialist's options were three: decline on the statutory ground that the agent lacks authority for the act requested, with a letter to both principal and agent; send to legal for a ruling; or move the case to elder financial protection with the account unchanged. Each choice carries a reason code and a note, and a second specialist checks it. The decline is a lawful refusal with its ground on file. A decline with no reason is an argument waiting to happen.
The desk procedure for hot-power requests
A bank asked by an agent to exercise a hot power should find the express grant, check who gains, confirm the document is genuine and in force, consider a call to the principal, and decide inside the statutory clock, with suspected exploitation routed before anything changes. The checklist turns the statutes into steps a specialist can follow and an auditor can test.
Before acting on a hot-power request under a power of attorney
- Classify the request
Beneficiary, survivorship, trust, gift or general banking. Only the first four need the express grant.
- Find and quote the express clause
An all-acts or general banking grant is not enough. Record the page and wording relied on.
- Check who gains
If the agent or someone the agent supports gains, the agent must be an ancestor, spouse or descendant, or the document must allow it.
- Check the document is acknowledged, current and not revoked
Good-faith reliance does not protect a forged principal's signature. Authority ends when the principal dies.
- Request a certification or opinion where the reading is unclear
Virginia lets the bank rely on an agent's certification under oath without further investigation.
- Call the principal on a number of record where possible
Ask about the change without reading it back. A principal with capacity can sign the change personally.
- Decide inside the clock, with the ground on file
Seven business days in Virginia to accept or request more; a refusal names its statutory ground.
- Route suspected exploitation with the account unchanged
Nothing said to the agent about a referral.
The call to the principal deserves a note. If the principal has capacity and wants the change, the cleaner route is for the principal to sign the beneficiary form personally, which needs no power of attorney at all. A callback that confirms the agent's request is useful evidence, but it does not supply a grant the document lacks. Callback verification when the phone on file has just changed explains why the number dialled matters as much as the answer.
Who decides: routing a hot-power request
The specialist decides the route; the reading of the document and state law belongs to someone qualified to give it, and exploitation belongs to the protection team. Agents can find the clause, compare the parties and show what approval would let someone do, but whether an agent may make the change is a legal judgment the software should flag, not make.
A hot-power request, from the form to a checked decision
Agent
Read and classifyReads the request and the power of attorney, classifies the change, and finds any express grant and the parties' relationship.
Never: Never accepts a power of attorney for a beneficiary change without an express grant
Agent
Show what approval would doStates in plain words and dollars who would gain, and sweeps 90 days of history for signals.
Never: Never decides
A person decides
Choose the routeDecline on the statutory ground, send to legal, or move to elder protection, each with a reason code and a note.
A person decides
Second checkA different specialist checks the route, the ground and the letters.
Agent
Draft the noticeDrafts the letter to the principal and the agent from a template, checked for any mention of a referral before it is sent.
The second check matters most when the request is declined, because a refusal is the decision the presenter is most likely to challenge. Segregation of duties on the maintenance desk covers the maker-checker split in full, and CIP requirements when an ownership change adds a customer covers the joint-owner case from the identification side.
Questions people ask
Does a durable power of attorney include hot powers?
No. Durable means the power survives the principal's incapacity; it does not widen what the agent may do. A durable power of attorney with general banking authority and no express grant still cannot change a beneficiary designation or add a joint owner with survivorship.
Can a power of attorney change a beneficiary after the principal dies?
No. Under Virginia's version of the act a power of attorney terminates when "The principal dies" (Va. Code § 64.2-1608(A)), and the agent's authority ends with it. After death the payable-on-death designation on file controls the account.
Are gifts under a power of attorney limited?
In Virginia, general gift authority is limited per recipient to the annual federal gift tax exclusion, or twice that with a spouse's consent to split the gift, unless the document provides otherwise. An all-acts grant allows gifts in line with the principal's history of lifetime giving. A large transfer to the agent outside those limits needs an express grant.
Can the bank ask the agent to certify facts about the power of attorney?
Yes. Virginia lets the bank request and rely, without further investigation, on an agent's certification under oath of any factual matter, an English translation, or an opinion of counsel on a matter of law if the bank gives its reason in writing. Asking within seven business days of presentation keeps the bank inside the statute's clock.
Do hot powers apply to retirement accounts and life insurance?
The express-grant rule covers beneficiary designations generally, not only deposit accounts, and the list separately names waiving a joint and survivor annuity benefit. The plan or insurer applies its own procedures on top of the statute.
What if the bank refuses a valid power of attorney?
In Virginia a refusal outside the statutory grounds can lead to a court order mandating acceptance and liability for the presenter's reasonable attorney fees and costs. A refusal of a specific hot-power act, on a good-faith belief that the agent lacks authority for it, is one of the listed grounds, which is why the clause relied on, or its absence, should be on the file.